
Quick Take
- Aave’s consumer app adds recovery and authentication services around its self-custodial accounts.
- Horizon pairs open stablecoin liquidity with issuer checks on tokenized collateral.
- Wider adoption could strengthen DeFi’s political influence without removing existing regulatory powers.


The Senate gave DeFi a policy setback on Sept. 15. Then Aave founder Stani Kulechov used it to frame a new product challenge. Aave is a decentralized-finance lending protocol surrounded by consumer and institutional products built by Aave Labs.
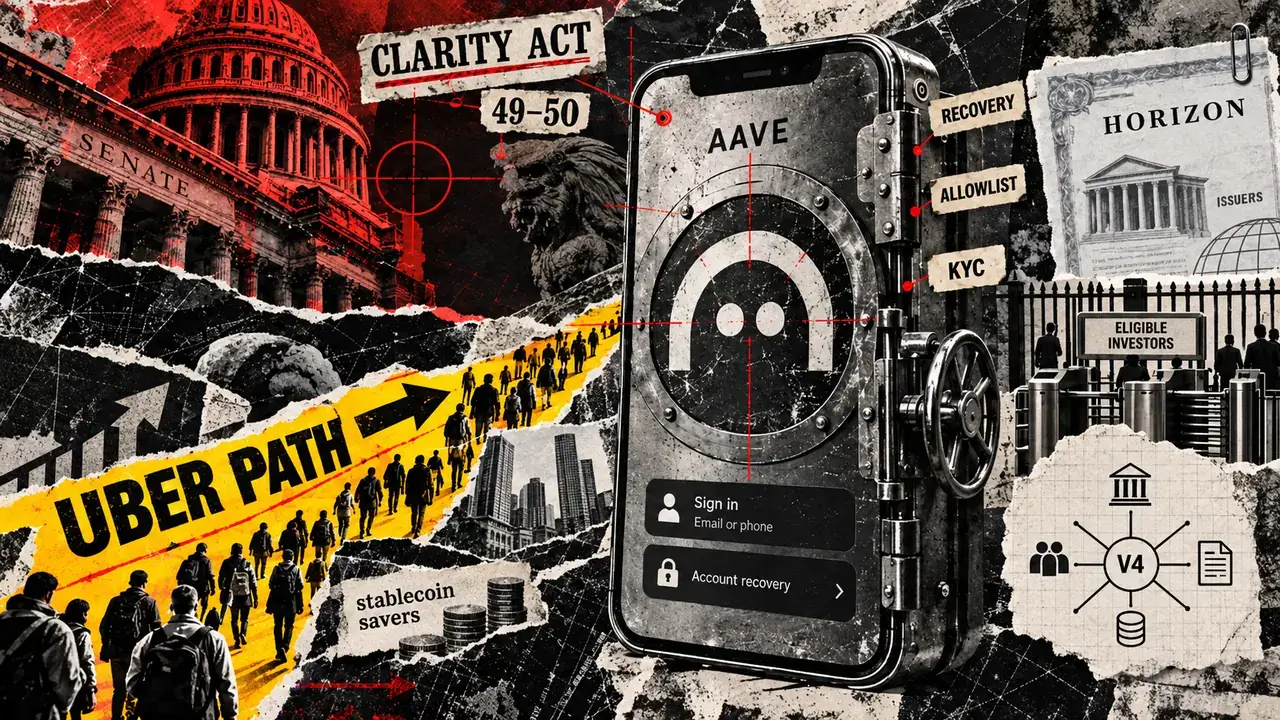
At 2:19 p.m. Eastern time, senators rejected cloture on the motion to proceed to H.R. 3633, the CLARITY Act, a federal digital-asset market-structure bill, by 49-50. The procedural vote required three-fifths, so the result blocked the bill's immediate route to floor consideration. It was not a final-passage vote and did not erase the authority regulators already have.
About 46 minutes later, Kulechov wrote on X that DeFi should respond by building products millions want and becoming “too important to ignore.” He called it “The Uber path.”
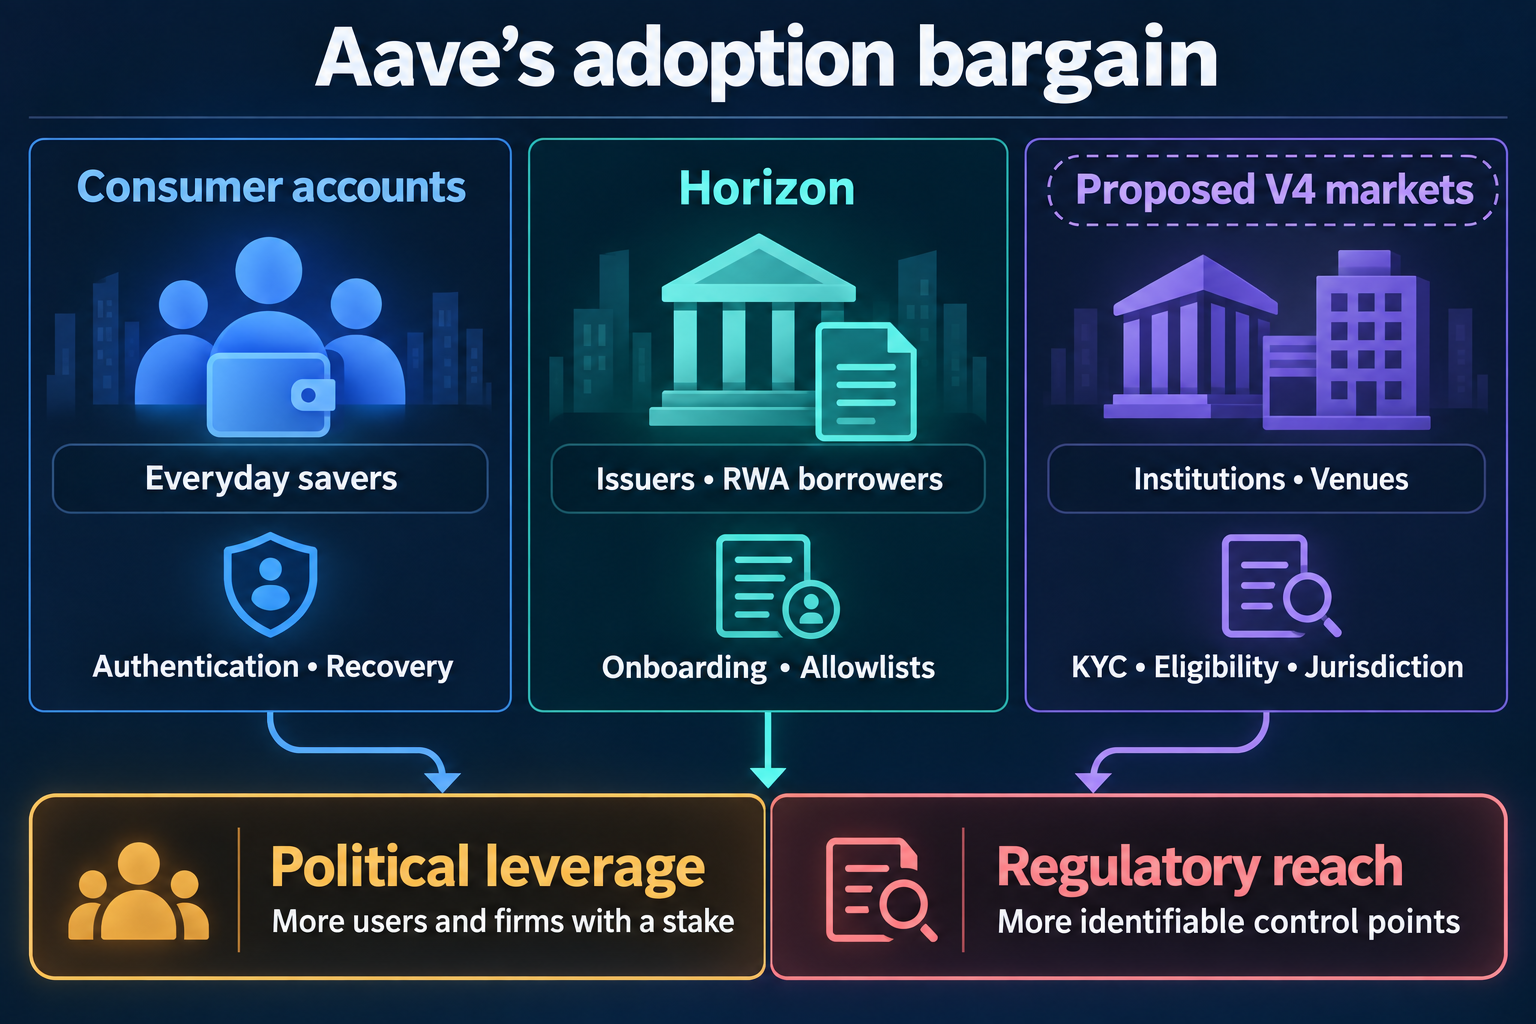
The analogy is a strategy for political leverage, not a claim that popularity changes the law. Aave's own product roadmap shows why the distinction matters. Consumer-friendly accounts, institutional lending against tokenized assets and a proposed securities-finance architecture could expand the number of people and firms with a stake in DeFi. Yet each growth path also assigns important functions to identifiable companies, issuers, service providers and permissioned venues.
Aave may be able to make DeFi harder for Washington to dismiss. Its regulated edges could also make the system easier to reach.
The consumer path adds a service layer
Aave Labs is trying to make onchain saving feel less like operating a crypto wallet and more like using a modern financial app. Its account design supports sign-in with an email address or phone number and a password, with optional passkeys. Smart accounts can sponsor gas, batch transactions and require users to pre-authorize withdrawal destinations.
Recovery is the clearest example of the tradeoff. Aave says the app remains self-custodial, but convenience depends on infrastructure beyond the underlying protocol. A password- and authentication-encrypted signer result is stored on Aave's backend. A user who still has a previously authenticated device can recover access from that device. For optional lost-device recovery, encrypted private-key material is divided between CoinCover and Aave; after biometric verification and a one-time-password check, the two services release the material needed for recovery.
That arrangement does not show that Aave Labs can unilaterally reconstruct a user's key, seize assets or reverse a blockchain transaction. Aave's app disclosures say users remain in control and warn that losing every credential and recovery option can permanently lock them out.
Still, the product has an operational perimeter. The smart account grants Aave a limited permission to move received stablecoins into a vault so deposits can begin earning without another user action. Email and phone authentication, the backend, CoinCover recovery and withdrawal allowlists are identifiable services. They are part of what makes the product useful to mainstream customers, and they are easier for policymakers to see than autonomous smart-contract code.
The corporate and protocol layers also need to remain separate. Aave Labs' terms describe the Aave Protocol as open-source, self-executing infrastructure that the company does not own, operate or control. Aave Labs builds software, interfaces and services around that infrastructure, while Aave DAO governance and third-party integrations have their own roles.
That separation limits how much control can be attributed to any one actor. It does not make every layer equally unreachable.
Horizon widens the coalition and defines the gatekeepers
Aave Horizon applies the same tension to institutions. The market lets eligible borrowers use tokenized securities or other real-world assets as collateral for stablecoin loans. Its published architecture pools stablecoin liquidity while keeping compliance specific to each collateral asset.
The stablecoin side is open: anyone can supply stablecoins, and a wallet holding an approved asset can interact with the lending contracts under the market's parameters. The collateral side is deliberately gated. Asset issuers onboard and verify investors, set eligibility rules and manage the wallet allowlists that determine who can hold the token.
Other responsibilities are similarly explicit. LlamaRisk conducts asset diligence and maintains or recommends loan-to-value ratios, liquidation thresholds and supply or borrow caps. Chainlink provides onchain net-asset-value validation. Smart contracts execute the lending logic.
That allocation of duties could help bring asset managers, issuers and qualified investors into DeFi without requiring them to abandon compliance. It could also expand the constituency that would resist a policy designed to shut tokenized-asset lending out of the United States.
But the political constituency and the regulatory perimeter grow together. Issuer onboarding, KYC decisions, allowlists, price validation and risk parameters are not abstract features of a decentralized network. They are functions attached to identifiable actors.
| Aave initiative | Constituency it could widen | Controlled function | Practical point of contact |
|---|---|---|---|
| Aave App accounts | Everyday stablecoin savers | Authentication, recovery and withdrawal allowlists | Aave Labs and recovery providers |
| Horizon | Issuers and qualified RWA borrowers | Investor eligibility, asset allowlists and risk settings | Issuers and risk-service providers |
| Proposed V4 securities finance | Brokers, lenders and tokenized-asset venues | Venue rules, jurisdiction and collateral eligibility | Permissioned venue operators |
Aave Labs' June 2026 research on securities finance using V4 goes further. It proposes a hub-and-spoke design for lending against tokenized securities, repo and securities lending.
One option would place a single deep liquidity hub beneath multiple specialized spokes. Each spoke could have its own assets, risk parameters and rules while drawing from the same pool. A second option would use several hubs divided by asset category and risk, allowing a Treasury market to remain structurally separate from a higher-risk equities market.
The proposal presents the choice as a tradeoff. One hub maximizes depth but requires risk isolation to be configured at the spoke level. Multiple hubs make isolation structural but split liquidity. Spokes could still connect to more than one hub.
For regulation, the important feature is at the edge. A permissioned spoke or jurisdiction-specific hub could enforce KYC, eligible-asset and location rules while using shared liquidity underneath. This is a proposed market structure, not evidence that Aave has already deployed a complete securities-finance network. But it shows that institutional scale would not arrive by making regulated functions disappear. It would translate those functions into software parameters and defined operator roles.
That could make compliance more efficient. It could also make responsibility easier to locate.
CLARITY's failure did not create a legal vacuum
The Senate vote left digital-asset market structure without the bill's immediate path forward. It did not leave interfaces, issuers or intermediaries outside existing law, and the relevant authority follows the function at issue.
The Securities and Exchange Commission can apply federal securities laws when an asset or arrangement is a security. In April, SEC staff issued a conditional statement on certain self-custodial crypto interfaces. The statement is nonbinding and limited to broker-dealer registration under Section 15 of the Exchange Act, but its conditions make the policy point: solicitation, routing, fees, defaults and disclosures can matter at the interface layer. A separate staff statement on tokenized securities says putting a security on a blockchain does not change the securities-law analysis.
The Commodity Futures Trading Commission has a different lane. It says it retains anti-fraud and anti-manipulation enforcement authority in spot digital-commodity markets and full regulatory and enforcement authority over derivatives. That is not general supervision of every spot lending product, but it is an existing route when conduct or instruments fall within the agency's remit.
FinCEN's virtual-currency guidance is also activity-based. Merely developing software does not make a person a money transmitter. A business that uses or operates software to accept and transmit value can face Bank Secrecy Act obligations, depending on the facts.
State law adds another layer. Licensing varies by jurisdiction and activity. The Conference of State Bank Supervisors offers a model framework for modernizing money-transmission rules. New York's virtual-currency rules cover activities such as transmission, custody, customer exchange and issuing or administering virtual currency, while also containing exemptions.
None of that means Aave App, Horizon or a future V4 venue automatically falls into every category. It means the absence of CLARITY does not reduce the analysis to protocol code alone.
Kulechov's “Uber path” describes a real political mechanism. A product used by millions creates voters, customers, counterparties and businesses that may press lawmakers for workable rules instead of prohibition. Institutional adoption can add issuers and financial firms to that coalition.
Aave's product strategy is well suited to test that proposition because it reaches for both sides: consumer savings and institutional collateral markets. If those products scale, policymakers would face a larger set of interests when deciding how DeFi should be treated.
Yet adoption does not decide whether a tokenized instrument is a security, whether a derivative falls under CFTC rules, whether a service is transmitting value or whether a state license is required. Those questions attach to functions and facts.
Aave's most usable products make that reality visible. Recovery systems, corporate interfaces, issuer allowlists, risk managers and permissioned venues can help DeFi serve people and institutions that would not use a bare protocol. They also give regulators places to require disclosures, qualifications, controls or registration where existing law applies.
The likely outcome is not that Aave becomes too important to regulate. It is that Aave can become important enough to shape what regulation targets. The protocol may remain distributed, while the consumer and institutional layers negotiate with Washington because those are the layers where adoption, responsibility and political leverage meet.

Aave is +12.30% over the past 24 hours and currently sits at rank #39 by market cap.
Mentioned in this article

Editorial credits