
Quick Take
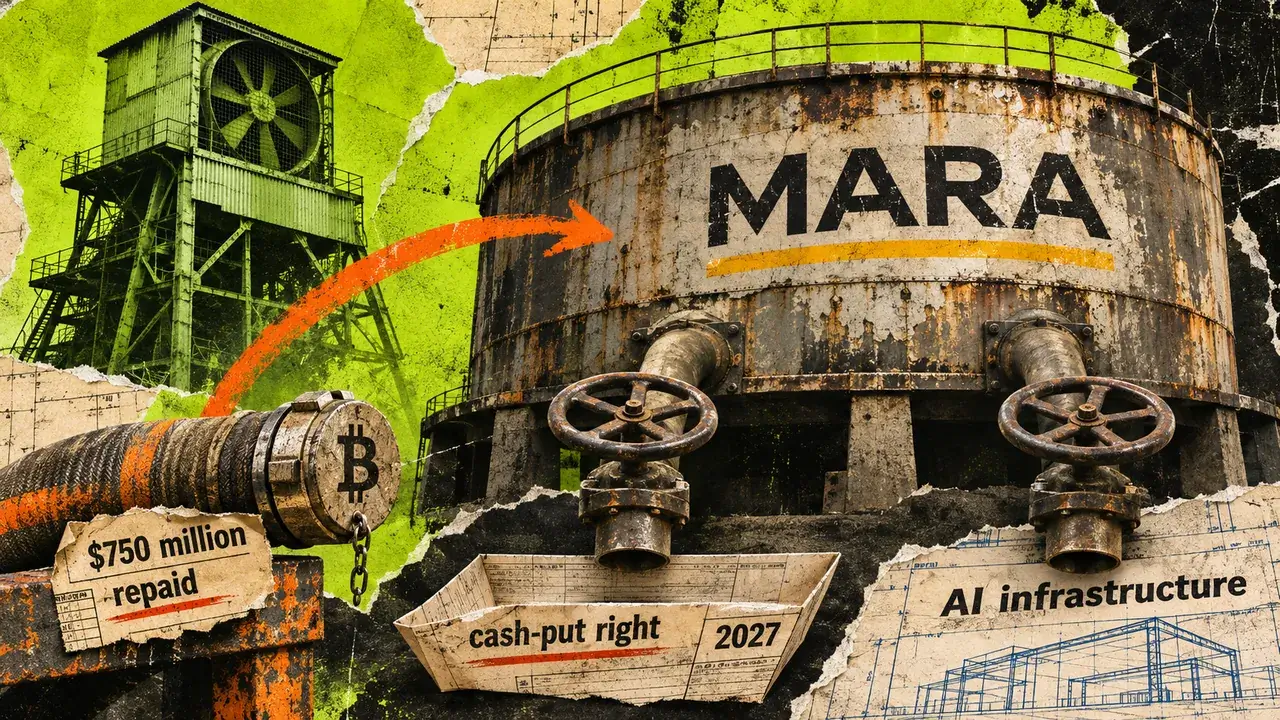
- MARA disclosed post-September sales of 13,597 BTC and a $750 million loan payoff that released pledged Bitcoin collateral.
- Sept. 30 balances show $924.1 million of note principal with 2027 cash puts, payable if holders exercise their rights.
- Management still plans Bitcoin monetization for infrastructure, potential buybacks and bond puts, while dated cash and financing provide options.


Bitcoin miner MARA Holdings has repaid its $750 million of Bitcoin-backed loans, ending the collateral-liquidation exposure attached to those facilities.
Further coin sales could now serve to build cash for bondholder demands, AI infrastructure, and possible share buybacks.
The company's Nov. 9 filing disclosed that it sold 13,597 Bitcoin after Sept. 30 for approximately $1.1 billion and used $750 million to repay the loans in full.
Management's quarterly letter says it intends to use Bitcoin to build cash for AI infrastructure opportunities, convertible-note puts exercisable next year and potential repurchases of its own shares.
Two 2027 dates keep cash in focus
As of Sept. 30, MARA had $291.6 million of June 2031 notes carrying a June 4, 2027 cash-put right, and $632.5 million of March 2030 notes carrying a December 1, 2027 right. Together, those September balances total about $924.1 million.
A cash put lets a bondholder require the company to buy back all or part of the notes for cash at face value, plus any applicable unpaid special interest.
The notes' contractual maturity dates remain in 2030 and 2031, and the eventual cash bill depends on which holders exercise and how much principal remains outstanding.
A separate obligation of $48 million of notes outstanding at Sept. 30 matures on Dec. 1. The put calendar does not require MARA to sell Bitcoin to meet potential cash demands.
Loans cleared. Cash choices remain.
The 2027 holder-put calendar survives the repayment of MARA's Bitcoin-backed loans. Explore how the potential route to selling changed.
How the selling channel changes
The outstanding Coinbase and Two Prime loans exposed pledged Bitcoin to conditional lender liquidation remedies.
The Nov. 9 disclosures report full repayment after quarter-end. Management still identifies cash uses for continued monetization.
Cash puts are elective holder rights. Repayment removes one liquidation channel while management still plans Bitcoin monetization.
Principal only; applicable accrued unpaid special interest is additional. Payments depend on holder exercise and balances at the dates. Loan payoff occurred after Sept. 30, disclosed Nov. 9; exact transaction dates were not supplied. No current cash balance or inevitable future Bitcoin sale is implied.
Sources and evidence
Sources
Supporting facts
- MARA disclosed on November 9 that after September 30 it sold 13,597 Bitcoin for approximately $1.1 billion and used $750 million of the proceeds to repay all outstanding Bitcoin-collateralized loans; the pledged Bitcoin was returned. [1] [2]
- Repayment ended the collateral-maintenance and lender-liquidation exposure attached to the repaid Coinbase and Two Prime facilities; it does not establish that MARA will stop selling Bitcoin. [1] [2]
- In its November 9 shareholder letter, MARA said it intends to use Bitcoin to build cash for AI infrastructure opportunities, convertible-note puts exercisable next year and potential share repurchases. [2]
- At September 30, MARA had $291.584 million principal of June 2031 notes with a June 4, 2027 holder cash put and $632.540 million of March 2030 notes with a December 1, 2027 cash put. [1]
- The two September 30 principal balances carrying 2027 cash puts total $924.124 million, or about $924.1 million; payment depends on holder exercise and principal remaining outstanding at the relevant dates. [1]
- The put rights let holders require MARA to repurchase all or part of the relevant notes for cash at 100% of principal plus any applicable accrued unpaid special interest; their legal maturities remain 2030 and 2031. [1]
- A separate $48.077 million principal balance of December 2026 notes was outstanding at September 30 and matures December 1, 2026. [1]
- MARA's disclosed resources and alternative funding routes do not by themselves demonstrate an unavoidable Bitcoin sale or a funding shortfall; future sales depend on cash needs, financing, holder choices and management's capital allocation. [1] [2]
Method
Principal inputs are dated Sept. 30, 2026. Verified 291.584 + 632.540 = 924.124 USD million. Stacked bar widths use 291.584/924.124 and 632.540/924.124; labels round to one decimal million. The separate December 2026 maturity is not part of that bar. Panel diagrams are schematic mechanisms, not quantities or sale forecasts.
Scope
Principal only; applicable accrued unpaid special interest is additional. Payments depend on holder exercise and balances at the dates. Loan payoff occurred after Sept. 30, disclosed Nov. 9; exact transaction dates were not supplied. No current cash balance or inevitable future Bitcoin sale is implied.
 CryptoSlate
MARA entered the fourth quarter with $946.5 million of cash and equivalents, excluding $12 million of restricted cash. Approximately 11% of that cash was held in euros by its majority-owned subsidiary Exaion and contractually designated for its operations over the next year.
The subsequent Bitcoin sales brought in approximately $350 million more than the loan payoff. Adding that difference to September cash produces a rough $1.3 billion bridge before other cash movements.
MARA also reported about $1.5 billion of unused capacity under its at-the-market share issuance program as of Sept. 30. Management said existing liquidity resources provided flexibility to meet obligations and fund growth over the next twelve months and beyond.
MARA used $642.7 million of cash in operating activities during the first nine months of 2026. Its Bitcoin-sale proceeds are classified as investing cash flows, so the operating outflow alone cannot establish a funding gap after those sales.
Infrastructure and buybacks compete for capital
The planned acquisition of power business Long Ridge remained pending in the Nov. 9 disclosures. Its approximately $1.5 billion enterprise value includes up to about $900 million of assumed debt.
A bridge commitment of up to $785 million supports a portion of that debt if needed, subject to customary conditions.
The data-center development agreement with Starwood includes MARA funds approved for pre-development pursuit costs, with $136.3 million approved across sites and about $17.7 million incurred by Sept. 30.
Site contributions receive value before MARA adds incremental equity, while project financing is expected to be non-recourse.
The HIF site-development project's price of up to $600 million is tied to post-closing development milestones, with additional payments possible for specified shortfalls.
The board's Nov. 9 authorization permits up to $500 million of common-share purchases, but requires no particular amount and can be suspended or terminated.
The next meaningful supply signal is MARA's disclosure of further Bitcoin sales and how it uses the proceeds. Updated cash and remaining note balances will help distinguish preparation for holder puts from optional infrastructure and buyback spending.
Mentioned in this article

Editorial credits