
Quick Take
- Miners signed $100B+ in AI contracts, but only 550 MW of 4 GW is billing.
- Scarce grid access is lifting valuations while pushing 35 EH/s away from Bitcoin.
- Billions in buildout remain, risking valuations if deployment falls behind.


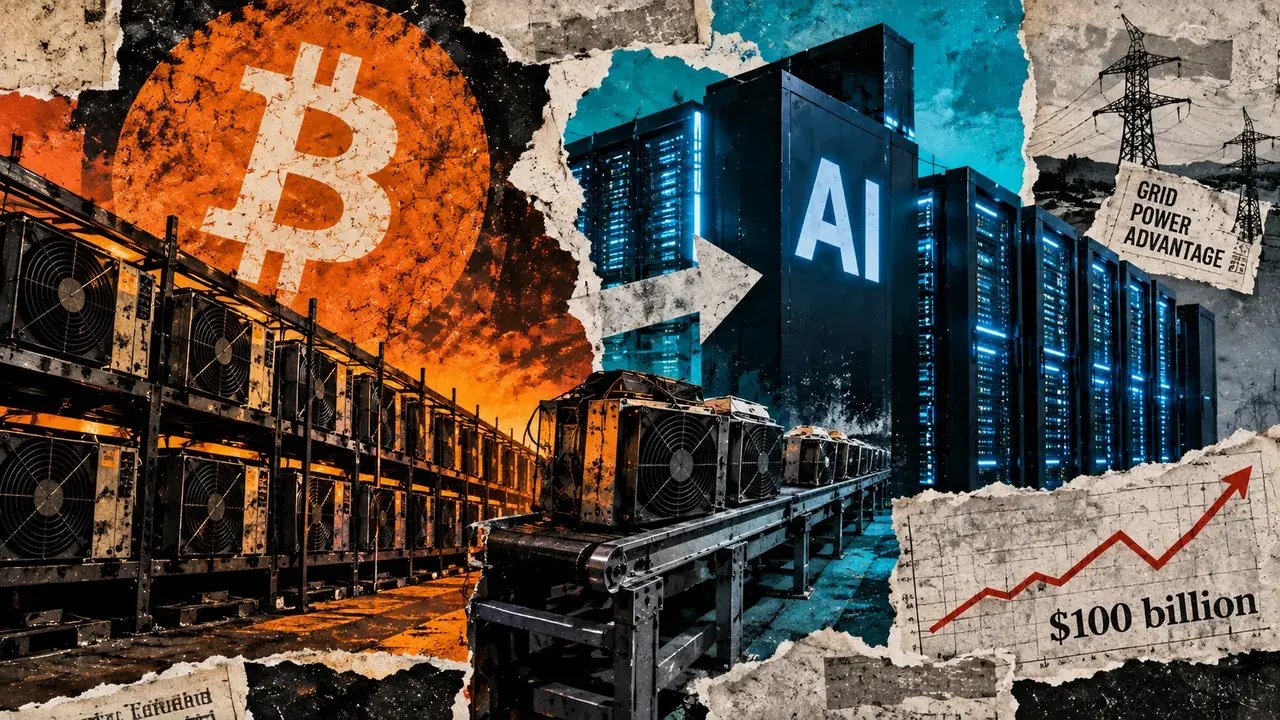
Bitcoin miners have signed more than $100 billion in AI contracts while generating barely $1.1 billion in annualized revenue.
More than 4 gigawatts of artificial intelligence and high-performance computing capacity are under contract across publicly traded miners tracked by CoinShares, but only about 550 megawatts are currently billing.
Still, investors are assigning a steep premium to companies making the AI transition. Miners with contracted AI or HPC capacity trade at an average of 12.9 times enterprise value to next-12-month sales, compared with 3.7 times for miners without such agreements.
However, this premium is increasingly tied to an asset miners accumulated for Bitcoin but AI developers now badly need: grid-connected power.
Scarce power turns mining sites into premium AI assets
The value of existing mining campuses is rising as new data-center projects run into longer permitting processes and increasingly congested power grids across the US.
CoinShares recorded at least 225 moratoriums or restrictions on data-center development across 30 states, with 151 still in force, in its latest industry report. New York has introduced a statewide pause on environmental permits for facilities of 50 megawatts or more, while restrictions have spread at state and county levels elsewhere.
Those constraints are colliding with a US grid interconnection queue of roughly 2,600 gigawatts. Projects completed in 2025 waited a median of more than five years between entering the queue and becoming operational, giving miners with energized land and existing grid connections an advantage over developers starting from scratch.
The potential revaluation is substantial.
A recent transaction cited by CoinShares valued three fully leased Northern Virginia AI data centers at roughly $27 million per megawatt. Some publicly traded miners with energized but unleased capacity are valued below $3 million per megawatt.
That gap exists despite the high cost of turning a BTC mining site into an AI facility. CoinShares estimates retrofits can require about $8 million to $15 million per megawatt, compared with roughly $700,000 to $1 million per megawatt for Bitcoin mining infrastructure.
However, the economics can still justify the expense. AI infrastructure currently generates an estimated $1.5 million in annualized profit per megawatt for miners, roughly three times the $500,000 available from Bitcoin mining under current conditions.
Investors have responded before most of that revenue has arrived. Ten of the 12 mining companies followed by CoinShares gained between 70% and 195% during the second quarter. Keel Infrastructure, formerly Bitfarms, surged 194.4% even as it shut down its Bitcoin mining operations.
Miners are now paying to leave Bitcoin
The financial incentive has become strong enough that some operators are absorbing losses and abandoning equipment to accelerate the transition.
Core Scientific paid $41.9 million during the second quarter to terminate an agreement covering about 15 exahashes per second of next-generation Bitcoin mining equipment as it redirects infrastructure toward AI and HPC customers.
Its remaining self-mining business posted a -56% gross margin during the period. Some machines continue operating partly to offset power obligations while sites are converted to other uses.
Keel has gone further. The company shut down its remaining Bitcoin mining operations on June 29 and is expected to report no mining revenue in the third quarter, making its nearly 200% share-price rally during the second quarter one of the clearest examples of investors rewarding the transition.
IREN plans to substantially complete its move away from mining by Dec. 31 after recording hundreds of millions of dollars in impairments and markdowns on mining equipment.
Its revenue mix has already flipped. AI cloud revenue reached $70.5 million in its latest quarter, surpassing the $66.7 million generated from Bitcoin mining for the first time.
Cipher Digital has stopped planning new mining capital expenditure and expects Bitcoin production to become immaterial ahead of a likely exit by the end of 2027. TeraWulf has also retired mining buildings as HPC leases take a larger share of its business, with those contracts accounting for 71% of quarterly revenue.
CoinShares estimates that at least 35 EH/s is scheduled to leave publicly listed miners as those conversions continue, equivalent to roughly 4.7% of the Bitcoin network's recent 750 EH/s hashrate.
IREN accounts for 23.2 EH/s of installed capacity, while Cipher's Odessa operation contributes another 11.6 EH/s. TeraWulf is separately winding down roughly 145 MW of remaining mining capacity.
Meanwhile, the shift could be harder to reverse even as Bitcoin's recovery improves mining economics.
Bitcoin's rebound to about $77,000 has lifted hash price to roughly $38 per petahash per second per day, pushing most listed operators back above cash breakeven after a difficult second quarter. The weighted average ex-tax cash cost of producing one Bitcoin reached about $75,500 during the period, when the token ended June near $58,400.
A stronger Bitcoin rally could still change capital-allocation decisions for companies that have kept their mining options open. CoinShares expects new mining investment to concentrate among operators including Riot Platforms, MARA Holdings, HIVE Digital and Bitdeer, which retain greater flexibility to expand their fleets if returns improve.
That optionality is shrinking for miners as the AI transition deepens. Several have committed sites to leases lasting as long as 15 years, while Core Scientific's decision to spend almost $42 million canceling mining hardware illustrates how much capital has already been redirected.
$100 billion backlog now faces a buildout test
The same expectations lifting miner valuations are now pressuring operators to turn signed contracts into functioning data centers.
Only about 550 MW of more than 4 GW of contracted capacity is currently billing, leaving most of the sector's $100 billion-plus backlog dependent on future construction, financing and deployment.
The scale of that gap means investors are valuing much of the sector on infrastructure that has yet to produce revenue.
Some of the conversion is underway. Core Scientific is billing 437 MW, Cipher began collecting rent from its Black Pearl facility in August, and IREN is targeting $4 billion in annual operating recurring revenue by December.
CoinShares expects the industry's AI and HPC revenue run rate to more than double by its next report.
That growth would begin narrowing the gulf between the contracts already signed and the roughly $1.1 billion of revenue currently being generated. It would also strengthen the case for miners whose power portfolios are being valued more like future data-center platforms than Bitcoin operations.
The risk is that construction, financing, or power infrastructure fails to arrive quickly enough.
Billions of dollars still need to be deployed to convert contracted megawatts into revenue-producing facilities. Companies that complete those projects on schedule will begin putting cash flow behind the valuations investors have already assigned.
Those that do not could remain priced for an AI business that exists mostly in backlog.

Bitcoin is +0.75% over the past 24 hours and currently sits at rank #1 by market cap.
Mentioned in this article

Editorial credits