Quick Take
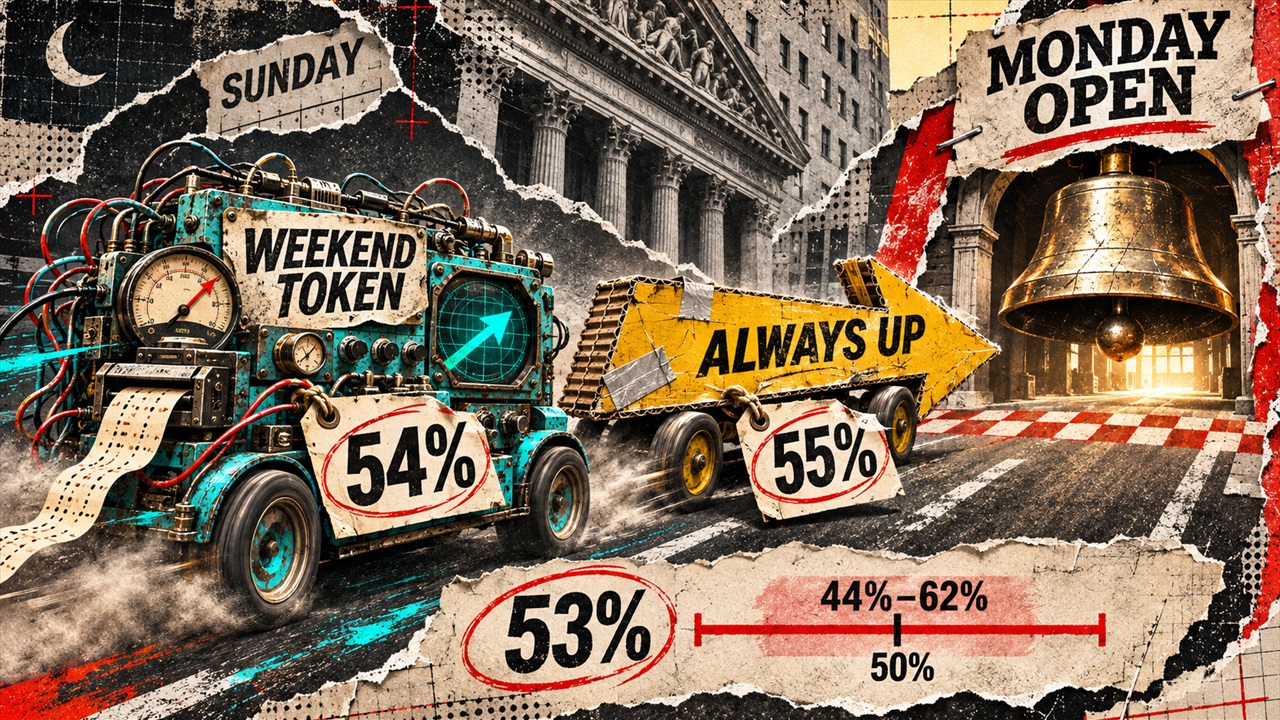
- Bitquery’s stock-token study scored 54% on qualifying opening directions, versus 55% for always predicting a rise.
- A stronger later Sunday result changed timing and sample filters after futures reopened, leaving independent token information unresolved.
- Nasdaq’s conditional 23/5 plan could narrow weekday access differences for investors eligible to use both routes.


Stock tokens kept trading through weekends, but their prices did not reliably guide the next stock-market open in a new study of 121 stocks.
Blockchain data provider Bitquery's Nov. 3 analysis found that Sunday token moves measured before equity-index futures reopened correctly called 54% of qualifying openings, so simply predicting that every stock would open higher scored 55%.
More hours can give investors another opportunity to transact, but they do not show that the resulting prices predict the next opening better.
What the weekend price test measured
Bitquery followed 17 weekends beginning July 10 through Oct. 30, with the final stock opening on Nov. 2. It recorded 791 stock-opening observations across those stocks, and its direction test kept the 533 openings that moved at least 0.5% from Friday's close.
Token moves pointed the right way on 286 of those observations, compared with 291 correct calls for always predicting a rise. Because more openings rose than fell, a 50% coin-toss benchmark alone would flatter the tokens' result.
The study also used balanced accuracy, which averages success on rises and falls. The tokens scored 53%, with a reported 95% interval of 44% to 62%.
Across all 791 observations, including smaller moves, the median error was 1.2% using token moves versus 0.9% assuming the stock opened at Friday's close. Bitquery put the excess error at 0.3%, with a 95% range of 0.2% to 0.5%.
A weekend price is not yet a forecasting edge
Bitquery's study asks different questions about direction and forecast size. The later Sunday reading also changes the information and the sample.
Trading access and useful forecasting information remain separate claims.
- Bitquery's November 3 study of 121 stocks over 17 weekends found no statistically clear directional forecasting advantage in stock-token prices read just before 6 p.m. New York time on Sunday, ahead of the equity-index futures reopening used as its cutoff. Bitquery, November 3, 2026
- Bitquery reports 791 eligible stock-opening observations over weekends beginning July 10–October 30, 2026, ending with November 2's open; its directional test uses only the 533 openings moving at least 0.5% from the previous Friday close. Bitquery, November 3, 2026
- Bitquery reports 53% balanced accuracy, averaging success on rising and falling openings, with a 95% interval of 44%–62%, including the 50% fixed-guess baseline; the hit-rate difference versus always-up spans about minus 20 to plus 16 percentage points. Bitquery, November 3, 2026
- Across all 791 openings, Bitquery reports a median forecast error of 1.2% using token moves, compared with 0.9% using Friday's stock close; its 0.3-percentage-point excess-error estimate has a 95% range of 0.2–0.5 points. Bitquery, November 3, 2026
- The study requires at least $10,000 weekend trading per token listing and a trade in the hour before both cutoffs, excludes split/ex-dividend openings and crypto-sensitive stocks such as MSTR and COIN, then blends issuers into one stock-weekend price weighted by weekend dollar volume. Bitquery, November 3, 2026
- A separate Bitquery sensitivity check using just-before-8 p.m. Sunday prices, a $1 million weekend-volume floor and a changed movement filter reports 59% balanced accuracy, with a 95% range of 53%–65%, on 220 openings; changing timing and eligibility together after futures reopen cannot isolate independent token information. Bitquery, November 3, 2026
Vendor research, not independent raw-data replication. No futures-price benchmark or cost-adjusted strategy. The later cutoff, volume floor and movement filter change together.
Method: Reported study figures only. Main test: 17 weekends beginning July 10–October 30, openings through November 2. Direction filters stock moves below 0.5%; size uses all 791 observations. Panel intervals are reported 95% ranges. Point and interval geometry maps linearly onto the same 40%–70% balanced-accuracy scale; this is an interval plot, not a zero-based bar chart.
The main test read token prices just before 6 p.m. Sunday ET, the futures reopening cutoff used by Bitquery. That timing is important because a later token price could incorporate information already available from equity-index futures.
A separate check using prices just before 8 p.m. returned 59% balanced accuracy, with a 95% range of 53% to 65%, across 220 openings. But it also raised the weekend-volume threshold to $1 million and changed the movement filter.
Listings needed at least $10,000 of weekend trading and a trade in the hour before each cutoff. The study excluded openings affected by stock splits or ex-dividend dates and crypto-sensitive stocks such as Strategy and Coinbase, then combined issuers using weekend-volume weights.
Earlier perpetual-market research reported improved forecasts from final weekend prices in a different sample. Different instruments, liquidity filters and observation times prevent that result from serving as a direct rebuttal to this test.
Nasdaq could narrow the weekday access gap of stock tokens
Nasdaq's Oct. 30 update described Dec. 6 as the expected transition to 23-hour, five-day trading, subject to clearing and market-data infrastructure being ready. Its related market-data proposals also remain subject to regulatory approval.
Its member implementation notice describes an added 9 p.m. to 4 a.m. ET session requiring new member ports.
If the rollout proceeds, wider conventional weekday hours would narrow one stock-token advantage for investors whose brokers and jurisdictions permit both routes. Weekend trading and the ability to hold tokens in a blockchain wallet remain separate benefits to assess.
For example, Kraken's xStocks disclosure excludes the US, Canada, UK and Australia, permits compatible-wallet withdrawals and says holders lack ownership and voting rights in the underlying shares.
The next useful evidence would hold timing and eligibility constant, compare against available market benchmarks, and measure executable results after costs. Until then, an available weekend price should not be mistaken for a demonstrated forecasting advantage.
Mentioned in this article


Editorial credits