Quick Take
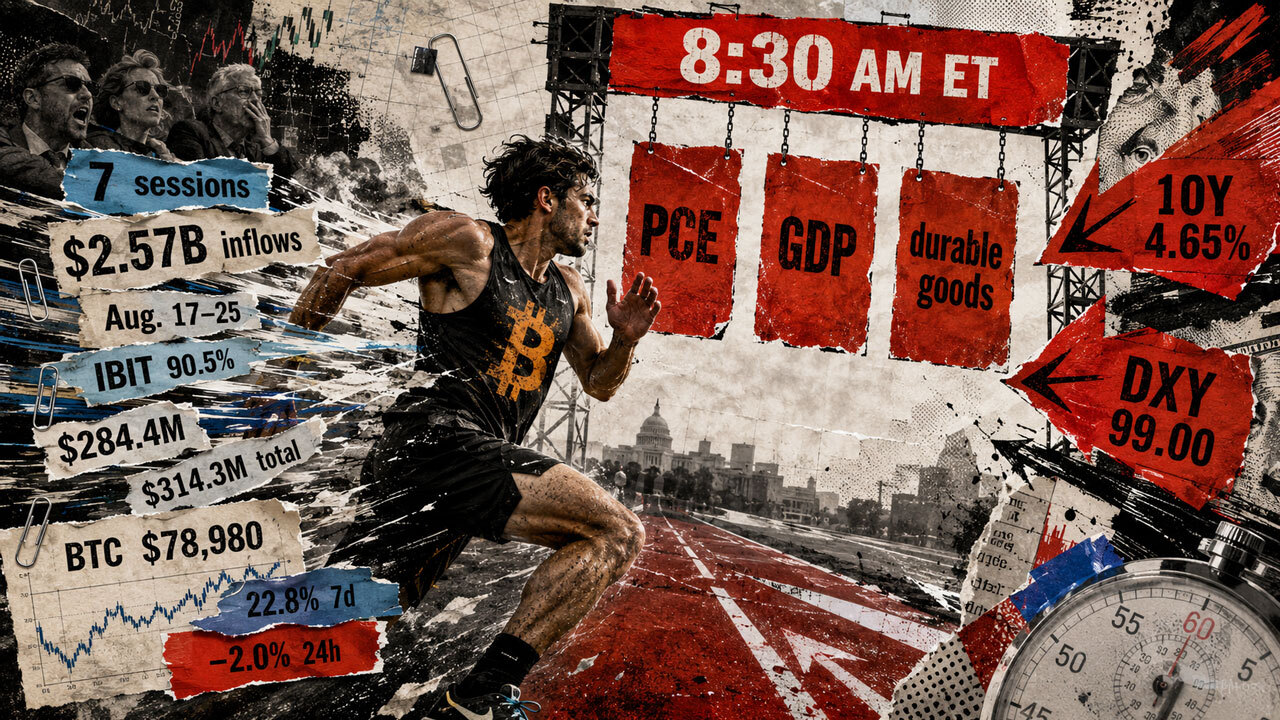
- Seven straight U.S. spot Bitcoin ETF inflow sessions added $2.5697 billion through Aug. 25.
- IBIT supplied $284.4 million, or about 90.5%, of the latest $314.3 million inflow.
- PCE, second-estimate GDP and durable-goods data arrive together at 8:30 a.m. ET.


The U.S. macro package that landed at 8:30 a.m. ET on Aug. 26 was collectively mildly hawkish, but it did not trigger the sharp Bitcoin selloff that was feared ahead of the release.
Bitcoin traded near $78,353 about 36 minutes after the data, compared with roughly $78,500 to $79,000 around the pre-release window. The 10-year Treasury yield was only one basis point higher at 4.65%, while the dollar was nearly unchanged. The muted reaction suggests Bitcoin absorbed the reports with only a small dip rather than a broad risk-off rejection.
The U.S. Bureau of Economic Analysis reported that headline PCE inflation rose 0.2% in July and 3.7% from a year earlier. Core PCE increased 0.2% on the month and 3.3% annually.
Those results were slightly hotter than consensus and the Cleveland Fed’s monthly nowcast for headline inflation, while core PCE was essentially in line with expectations. The release pointed to inflation that remained sticky, not a dramatic reacceleration.
The BEA’s second estimate of second-quarter GDP left growth unchanged at a 1.5% annualized rate. Its composition was firmer than the first estimate: private domestic demand was revised up to 4.2% from 3.9%, while quarterly headline and core PCE inflation were each revised 0.2 percentage points higher.
The clearest upside surprise came from the Census Bureau’s advance durable-goods report. July orders rose 1.1%, more than double the roughly 0.5% consensus expectation. Orders excluding transportation increased 0.4%.
Ahead of the reports, the ETF inflow streak remained measurable. Farside Investors’ daily table showed seven consecutive positive U.S. spot Bitcoin ETF sessions from Aug. 17 through Aug. 25, totaling $2.5697 billion in net inflows. Fund-flow data do not identify end investors, so the aggregate cannot establish broad institutional participation on its own.
The latest available session was also highly concentrated. BlackRock’s IBIT accounted for $284.4 million of the $314.3 million total on Aug. 25, or about 90.5%. That made the streak a strong aggregate net-inflow signal, but not a uniform one across funds.
The outcome of the streak’s next session is not yet known. Finalized fund-flow data for Aug. 26 are due later today, so it remains too early to say whether the macro release ended or extended the run.
The immediate market verdict was therefore restrained: the data package was stronger and modestly more inflationary in composition, but Bitcoin held close to its pre-release range as yields and the dollar moved only slightly. Post-release market snapshots similarly showed a limited cross-asset reaction.

Bitcoin is -2.61% over the past 24 hours and currently sits at rank #1 by market cap.
Mentioned in this article
Editorial credits