
Quick Take
- @ThinkingUSD called Ethereum a “worst asset” contender while sharing a dashboard estimating BitMine’s unrealized loss at about $9 billion.
- The dashboard pairs November holdings with an August average cost; BitMine’s November release provides no updated aggregate cost basis.
- BitMine’s November release gives no updated aggregate purchase cost; Lee’s bullish comments also predated Flood’s post.


Trader Flood, who posts as @ThinkingUSD, called Ethereum a “contender for the worst asset of all time” on Nov. 13, sharing a dashboard that put BitMine’s unrealized loss at about $9 billion.
The image marked the Ethereum treasury company 43% underwater. Its holdings match BitMine’s November disclosure, while its average-cost field is dated August. Applying that older average to the later balance approximately reproduces the dashboard’s displayed cost, leaving its loss figure dependent on that assumption.
Flood cited money lost to hacks, development time spent on inadequate tools and retail losses from betting on Ethereum’s price. He supplied no figures for those categories or comparative data establishing an all-time ranking. His criticism targeted Ethereum, with the BitMine dashboard providing a specific example of treasury exposure.
What sits behind the dashboard’s loss estimate
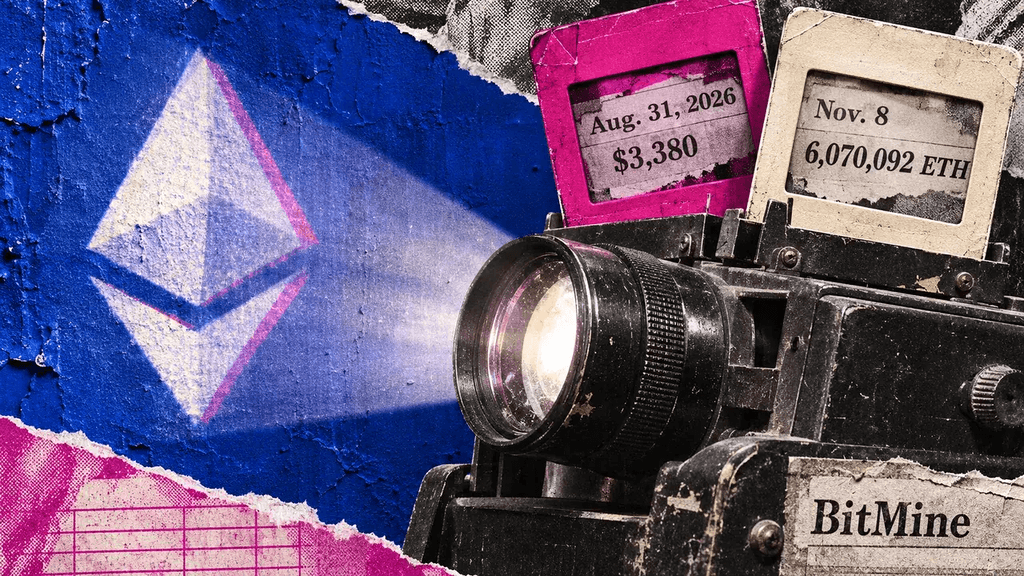
The image Flood shared listed 6,070,092 ETH, a $3,380 average cost, a $20.52 billion total cost basis and an $11.69 billion market value. Its displayed unrealized loss was $8,829,920,029.
The average-cost field is labeled as the filed average for Aug. 31, 2026. BitMine’s annual accounts reported 5,901,837 ETH at that date, with a cost basis of about $19.95 billion and a fair value of about $14.56 billion. Dividing the cost by the quantity gives approximately $3,380 per ETH.
Those accounts were filed on Nov. 10, but the holdings and cost figures describe the August balance.
BitMine’s Nov. 9 release reported a larger holding of 6,070,092 ETH as of Nov. 8 at 2 p.m. ET. Multiplying that quantity by the rounded August average produces roughly the $20.52 billion cost basis displayed on Flood’s dashboard.
That calculation extrapolates across two reporting dates. It reproduces the rounded total without confirming the dashboard’s underlying methodology or establishing what the expanded ETH holding actually cost. The November release supplies no updated aggregate cost basis.
The dashboard’s $8.83 billion loss estimate is therefore an unrealized mark against an assumed cost. It provides no evidence that BitMine sold those holdings and realized the loss in cash.
An older average. A larger ETH balance.
The dashboard shared by @ThinkingUSD matches November holdings with an August average cost. Their product reproduces its rounded cost estimate.
The $8.83B dashboard estimate relies on an older average cost; it is not BitMine’s disclosed current loss.
The Nov. 9 release gives no updated aggregate ETH cost basis. The dashboard does not date its market valuation; its loss is an unrealized estimate, not proceeds from a sale.
Sources and evidence
Sources
Supporting facts
- Reported statement The dashboard shared by @ThinkingUSD shows an unrealized BitMine loss of $8,829,920,029, or 43.0%, alongside 6,070,092 ETH, a $3,380 average cost labelled August 31, 2026, $20.52 billion cost basis and $11.69 billion market value. [3] [4]
- BitMine reported 5,901,837 ETH at August 31, 2026, with a $19.948168 billion cost basis and $14.558881 billion fair value in its fiscal 2026 10-K. [1]
- BitMine’s August 31 cost and holdings imply an average cost of about $3,380 per ETH; applying that rounded average to its later 6,070,092 ETH balance produces about $20.52 billion, the cost basis displayed by @ThinkingUSD’s dashboard. [1] [2] [4] [3]
- BitMine’s November 9 release reported 6,070,092 ETH as of November 8 at 2 pm ET, valued at $2,234 per ETH using Coinbase prices. [2]
- The November 9 holdings release does not supply an updated ETH cost basis, so the dashboard shared by @ThinkingUSD does not establish BitMine’s actual current unrealized loss. [1] [2] [3] [4]
Method
August cost $19,948,168,000 / 5,901,837 ETH = $3,379.993, rounded to $3,380. Multiply by November's 6,070,092 ETH = $20,516,910,960, shown as $20.52B. This reproduces the rounded total, not the dashboard's internal method. Bar width uses its printed 43% underwater; displayed money rounds to billions.
Scope
The Nov. 9 release gives no updated aggregate ETH cost basis. The dashboard does not date its market valuation; its loss is an unrealized estimate, not proceeds from a sale.
 CryptoSlate
The dashboard does not specify when its $11.69 billion market value was measured.
BitMine’s November release used a third observation: $2,234 per ETH from Coinbase for its Nov. 8 snapshot. That was a market valuation price, not an acquisition price.
Lee’s Ethereum thesis predates the post
Lee’s position in the Nov. 9 company release remained bullish. BitMine’s chairman described ETH as trusted collateral and argued that tokenization and AI would support its role as a store of value.
The company also reported 5,227,037 staked ETH as of Nov. 8. That staking position is distinct from the market-price gap illustrated by the dashboard.
Lee’s comments preceded Flood’s Nov. 13 post; they were not a response to it. They set out the investment thesis behind a treasury position that the trader presented as evidence of Ethereum’s poor performance.
CryptoSlate’s earlier coverage of BitMine’s accounts concerned fiscal-year losses and calculated final-quarter earnings through August. The dashboard presents a separate estimate of the gap between cost and market value.
Mentioned in this article

Editorial credits