
Quick Take
- An ETHGas-funded study models a four-minute expected eligible-slot wait when approved operators hold 5% of Ethereum’s proposer weight.
- The April commitment to ETHGas does not establish today’s active stake meeting institutional requirements.
- ETHGas’s relay counts show activity, but do not reveal the current proposer weight eligible for each institution’s requirements.

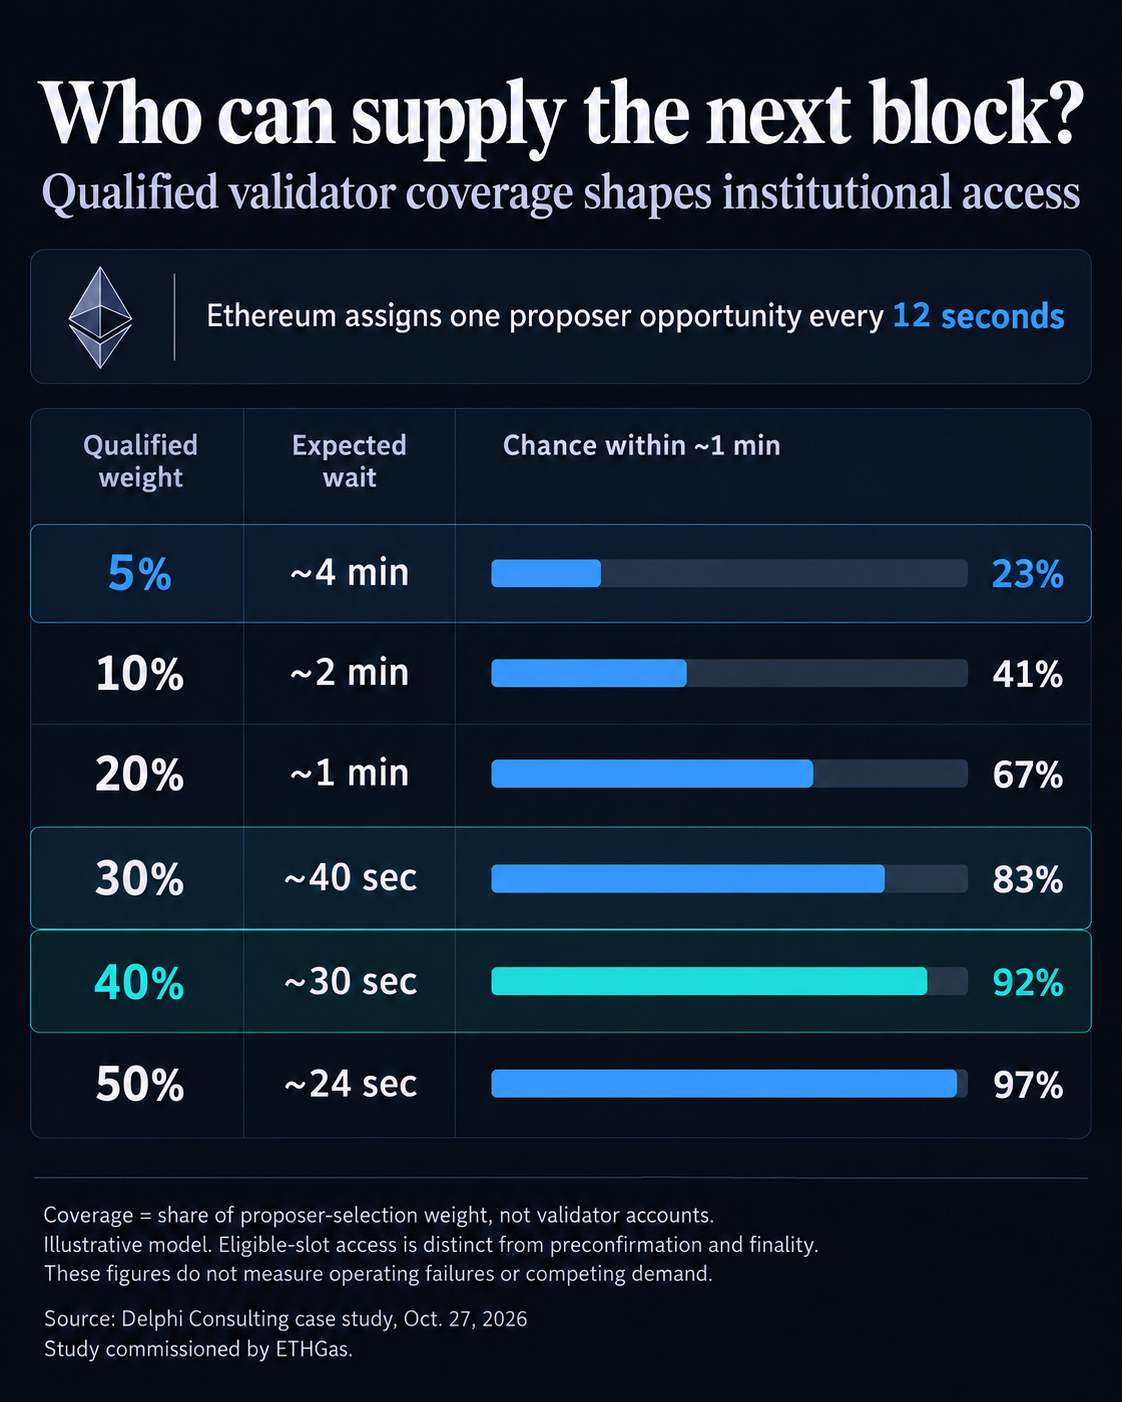
Institutions that restrict Ethereum transactions to approved block producers would face a four-minute average wait for an eligible slot if those operators held 5% of the network’s proposer-selection weight, according to an Oct. 27 case study published by Delphi Digital.
The model identifies a constraint for ETHGas’s opt-in institutional service, which reserves Ethereum blockspace through operators meeting customer requirements: buying capacity does not let a bank choose who produces the next block.
Ether.fi’s April commitment of ETH, then valued at $3 billion, offers potential supply, but the service’s availability depends on how much active stake meets each institution’s requirements.
The case study’s model gives that 5% scenario only a 23% chance of an eligible proposer within roughly a minute. At 40% qualified weight, the expected wait falls to about 30 seconds, and the one-minute probability rises to 92%.
How qualified validators supply blockspace
Ethereum has one proposer opportunity every 12 seconds, and the protocol selects the validator responsible for proposing that slot’s block, with selection weighted by effective stake. A service that accepts only particular operators has access to a subset of those opportunities.
The relevant share is proposer-selection weight, rather than the percentage of validator accounts registered with a relay.
The four-minute expected wait also averages across the model’s opportunities. Ethereum’s known upcoming proposer schedule lets buyers plan reservations against eligible slots. Once a qualifying slot is available, buyers can book it ahead of execution.
For a time-sensitive collateral transfer or portfolio rebalance, the practical question is whether suitable capacity exists when needed.
ETHGas announced the ether.fi agreement on April 15, saying that approximately 40% of ether.fi’s then-current ETH holdings would be committed to its High Performance Staking Service for three years. Ether.fi also agreed to exclusive use of ETHGas’s preconfirmation platform during the term.
ETHGas describes an opt-in institutional route with policy screening, transaction-ordering rules and operator requirements before block inclusion, while keeping settlement on public Ethereum. The intended benefit is access to existing assets and applications with more control over how a transaction reaches them.
Those controls also define the supply available to a particular customer. A validator participating in the wider marketplace may not meet every institution’s identity, jurisdiction, or operating requirements.
Consequently, an overall participation count cannot stand in for the effective stake eligible to serve a specific institution.
The reliability test for public Ethereum
ETHGas advertises confirmations in about 50 milliseconds, which addresses a different stage than finding an eligible proposer. A preconfirmation is a commitment before block inclusion, and Ethereum finality follows its own consensus process.
Fast acknowledgment cannot establish immediate access to a qualifying slot or final settlement.
JPMorgan announced on Oct. 19 that JPM Coin, its dollar deposit token using the ticker JPMD, was live on Ethereum’s main network for institutional clients, extending its availability beyond Base.
That expansion puts institutional money movement on the same public network as tokenized assets and collateral. It also illustrates why execution infrastructure needs to be assessed against financial workflows with defined timing and handling requirements.
The mainnet relay dashboard showed 221,558 all-time validator registrations and 104,728 delivered payloads in an Oct. 27 snapshot. Those cumulative counters show participation and payload delivery, but they don't identify current institution-qualified proposer weight or count institutional transactions.
The next useful capacity measure is the active effective stake eligible for a customer’s requirements, paired with delivery performance against that customer’s deadlines. Turning that opportunity into dependable execution requires both eligible slots and delivery when institutions need them.
Mentioned in this article

Editorial credits