
Quick Take
- EIA forecasts East Coast distillate inventories 20–30% below their seasonal five-year average through winter.
- Limited refining and tight global stocks could sustain heating and freight costs despite expected crude-price relief.
- National diesel prices have already fallen from September’s peak, while East Coast imports and stocks show mixed signs of relief.


The U.S. Energy Information Administration expects East Coast diesel and heating-oil inventories to stay unusually low this winter, potentially keeping transport and household costs elevated. For Bitcoin, that fuel pressure matters if it delays broader inflation and financing relief.
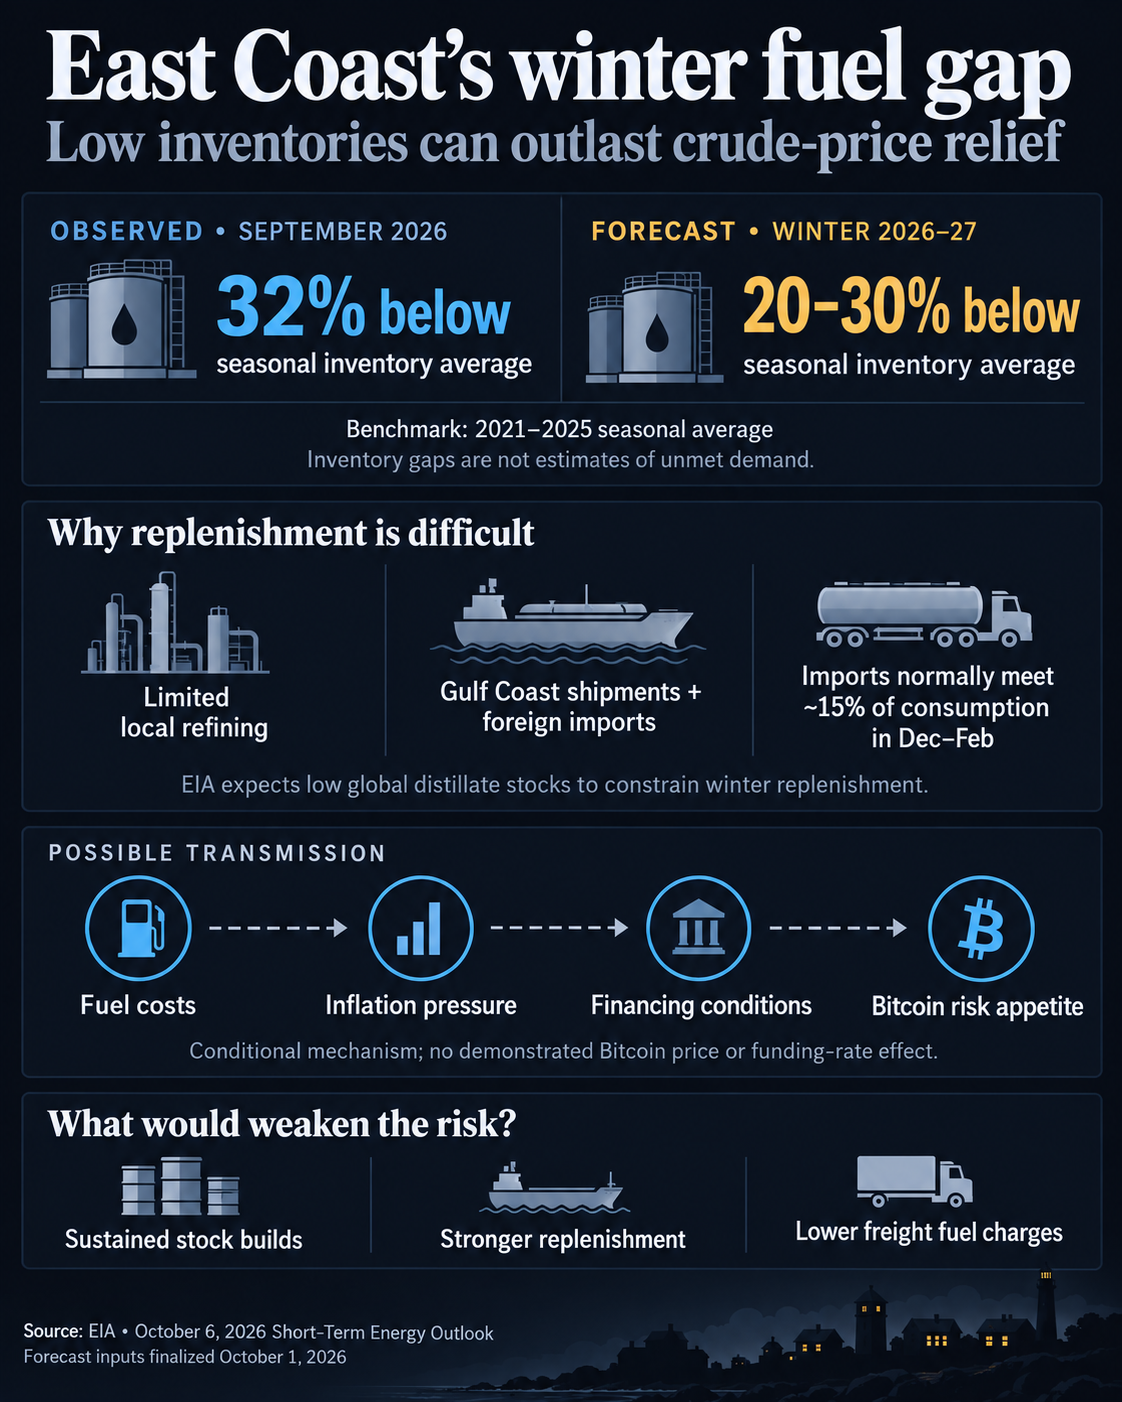
Its October 6 outlook put September distillate stocks 32% below their 2021–2025 seasonal average and forecast a 20–30% gap through winter.
Limited local refining leaves the region reliant on Gulf Coast shipments and foreign fuel. Imports typically cover about 15% of East Coast consumption from December through February. Low global stocks could make replenishment difficult, EIA expects.
Crude-price relief does not guarantee cheaper refined fuel. Daily Brent prices eased late in September, although the monthly average rose. EIA forecasts further declines in 2027, yet projects U.S. retail diesel above $4 a gallon through next year, with low inventories sustaining the wholesale fuel premium over crude, known as the crack spread.
Heating oil serves boilers and furnaces, while diesel powers freight trucks and trains. Persistent fuel costs can squeeze households directly and add to the expense of moving goods.
Why financing relief remains conditional
The Federal Reserve’s October 13 release adds evidence of earlier cost pressure. Its September 9 Board minutes report that most Reserve Bank directors observed oil and fuel among several input-cost pressures, alongside tariffs, healthcare and competition for resources from the AI buildout.
The release covers August and September discount-rate meetings. Regional directors’ recommendations concern discount-window lending to banks, a process distinct from the Federal Open Market Committee’s benchmark-rate decisions.
If fuel costs slow broader inflation relief, they could delay easier financing conditions for Bitcoin investors. Authors of an August 2023 IMF working paper found that Fed tightening reduced a historical price measure covering several crypto assets through investors’ willingness to take risk.
Relief is already visible in some fuel data. National retail diesel fell to $6.199 a gallon on October 5, from $6.529 on September 21, even as EIA forecast low winter inventories.
East Coast imports averaged 84,000 barrels a day in the week ending October 2, above 56,000 in the comparable year-earlier week but below 103,000 the week before. Regional stocks fell to 21.7 million barrels from 21.9 million a week earlier, leaving the supply picture mixed.
The September Cass freight index report attributed spending acceleration to shipments, rates and fuel surcharges. It also noted modest declines in spot trucking rates while the larger contract market continued adjusting higher, showing that freight pressure is uneven.
EIA’s forecast used inputs finalized October 1. Sustained regional stock builds, stronger replenishment and lower freight fuel charges would weaken the winter inflation warning, especially if relief reached broader prices and financing expectations.
Mentioned in this article

Editorial credits