 Released in 2018
- Reusable crypto-backed credit
- Bank and stablecoin payout routes
- No fixed monthly installments
Nexo Credit Line Overview
Key facts
- Product Name
- Nexo Credit Line
- Release Date
- 2018
- Service model
- centralized
- Product status
- available
- Collateral & debt
- BTC · Other assets available; Debt currency: xUSD
- Borrowing rate
- Rate not quoted; variable; Depends on loyalty tier and LTV
Additional details
- Offer scope
- Nexo Classic Credit Line; Classic rest-of-world credit line against BTC and other accepted assets. Excludes the US, UK, EEA, Canada, Switzerland, Australia, New Zealand, the UAE, and other markets, where separate regional offers have their own terms. Booster, card borrowing, Private, and Zero-interest Credit are separate.
- Amount & term
- $50 internal / $500 bank minimum · 12 months · Renewable; Loan structure: Revolving credit line; Minimum: xUSD 50; Maximum: Not disclosed; $50 internal / $500 bank minimum · Up to $2 million in new draws per day · Limit set by collateral and LTV; Term: 12 months
- LTV & liquidation
- Automatic repayment at 83.33% LTV (crypto-only) · Warnings at 71.4%, 74.1%, and 76.9% · Other contractual triggers · 2% to 3.5% liquidation fee on crypto, 1% on stablecoins; Maximum initial LTV: 50%
- Fees
- 0.26% crypto repayment (stablecoins and FIATx exempt) · 45-day early-repayment interest at 17.9% · 2% to 3.5% liquidation fee
- Repayment
- Flexible · Partial or full · Early-interest conditions
- Availability
- Rest of world · US, UK, EEA, and others excluded; KYC: Required; Credit check: Not required
- Payout
- Bank / stablecoins · Minutes to 5 business days by route
- Custody
- Custodial · Lending and re-pledging allowed
Nexo Credit Line Screenshots
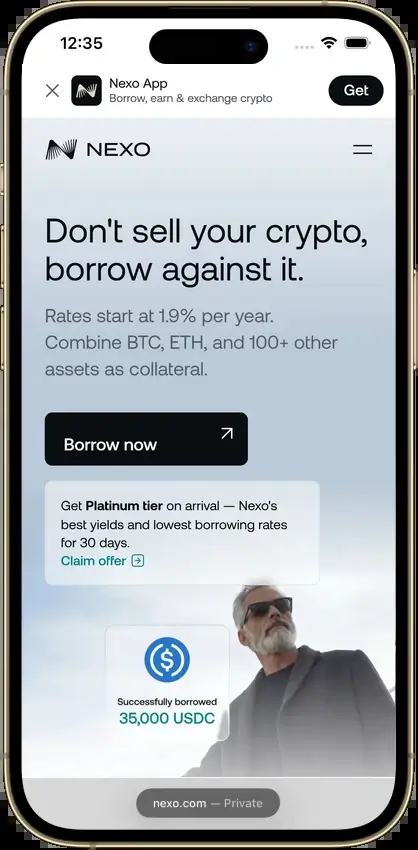
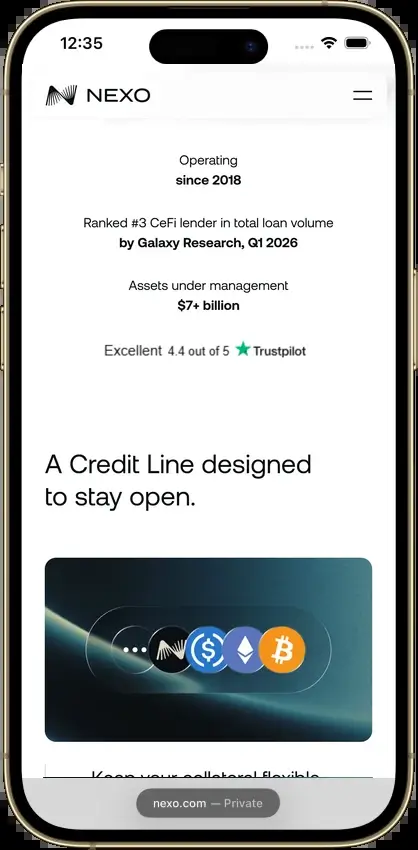
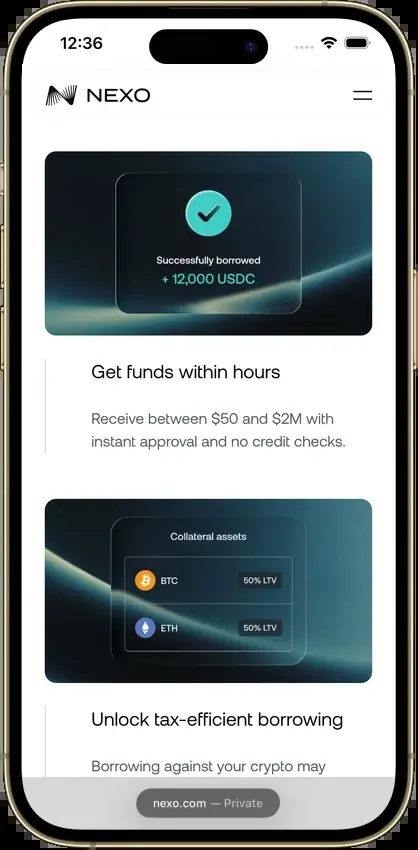
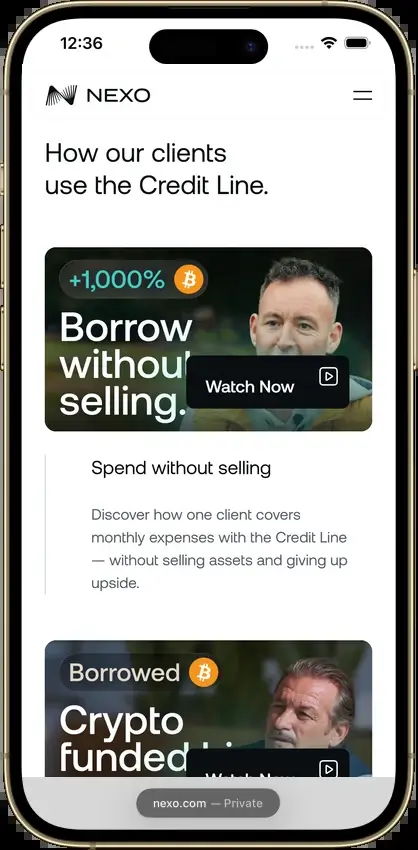
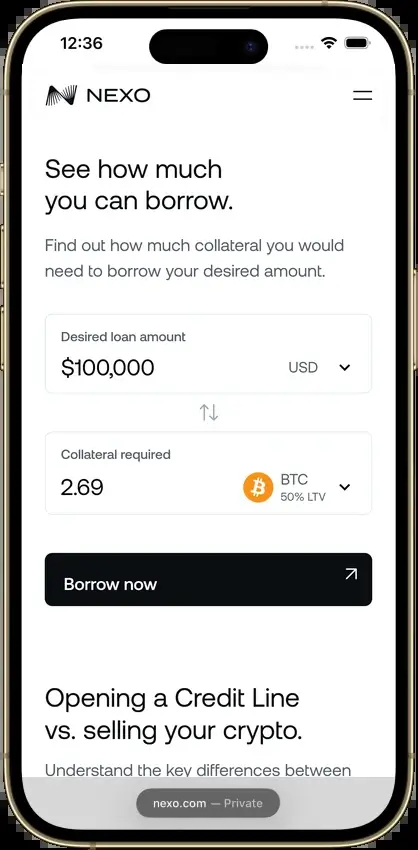
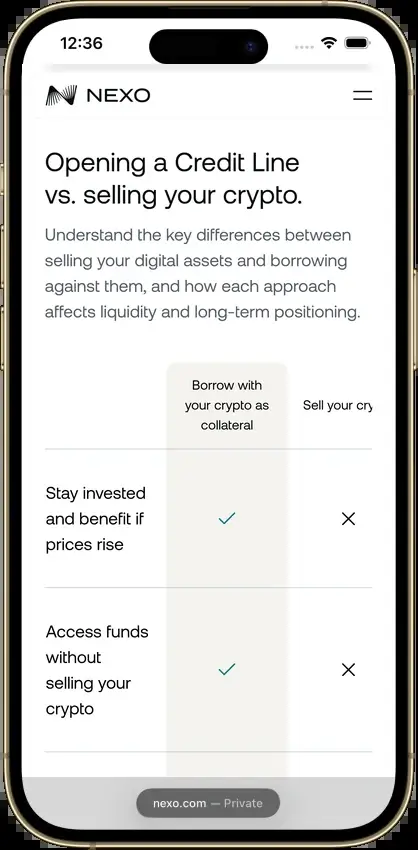
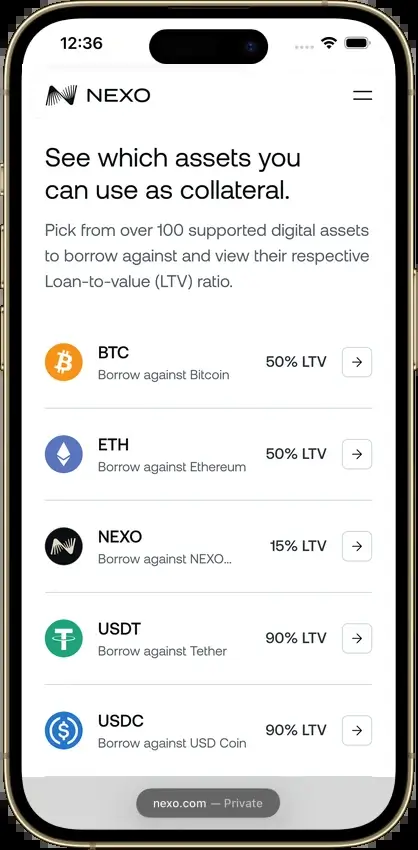
Screenshot 1 of 8
Nexo Credit Line Pros and Cons
Pros
- Per-line collateral transfer settings
- Repay the balance in stages
- Borrow against several collateral assets
Cons
- Extra interest on early repayments
- Lowest rate needs NEXO tokens and low LTV
- Collateral can be lent or re-pledged
Rates and Fees
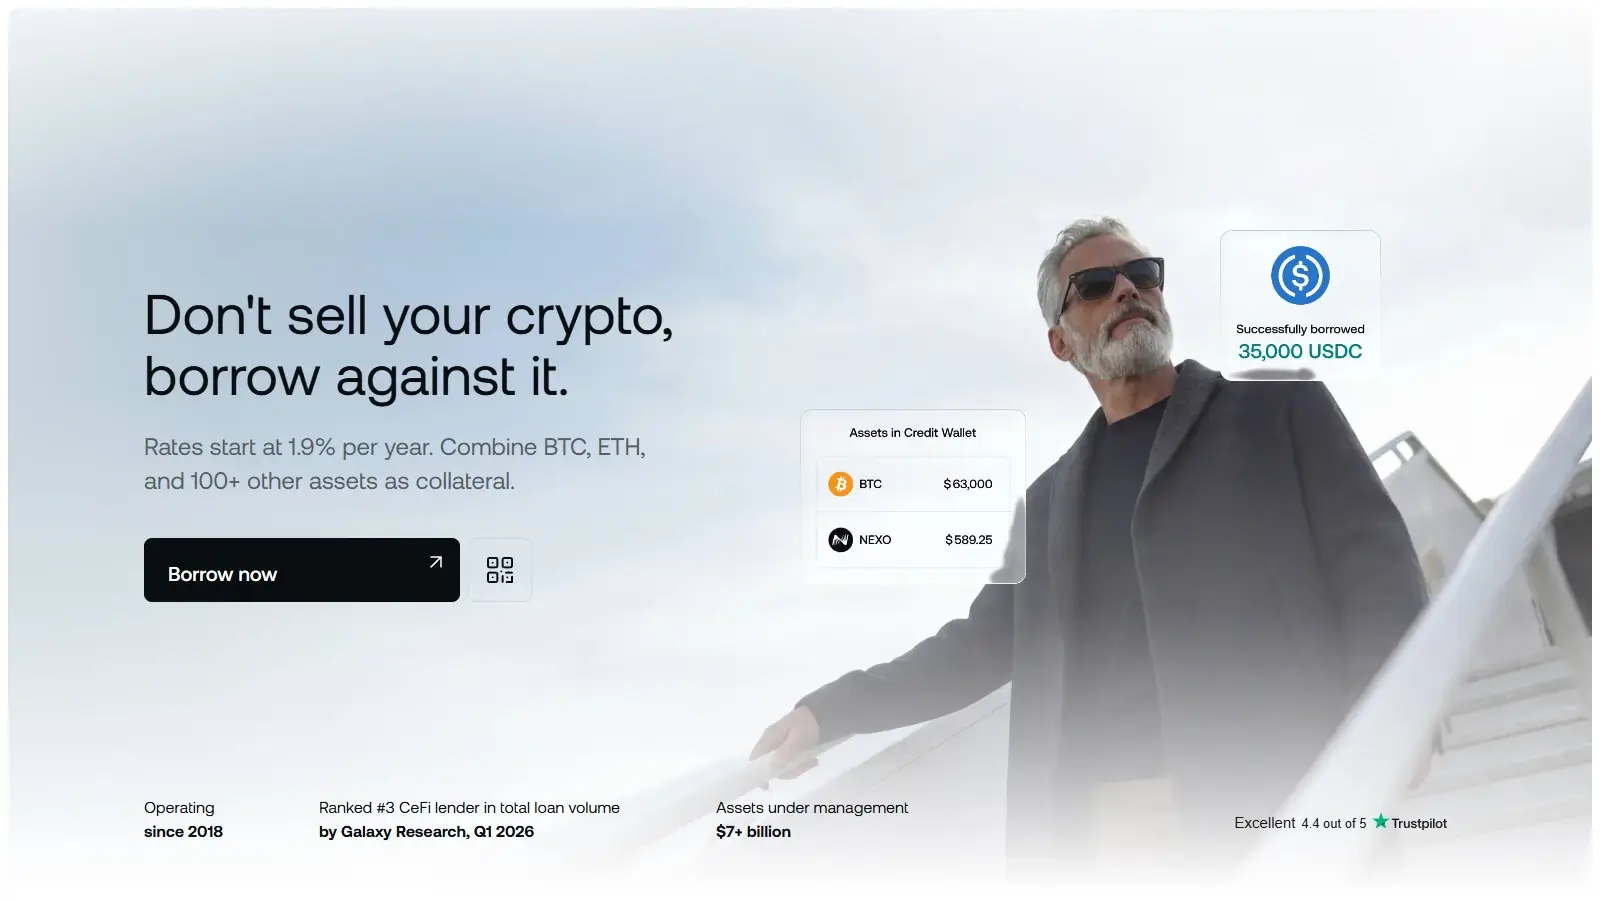
Nexo’s Classic interest rate changes with your Loyalty tier, portfolio balance, and Credit Wallet loan-to-value (LTV) ratio. Its lowest advertised annual rate of 1.9% requires Platinum status, the qualifying portfolio balance, and LTV below 20%. The portfolio requirement is $5,000, while Platinum requires holdings of Nexo’s own NEXO token worth at least 10% of the rest of the portfolio. Without the low-LTV discount, standard annual rates range from 9.9% at Platinum to 17.9% at Base, the tier with no NEXO holdings.
Those conditions make the lowest rate a poor guide for a BTC-only borrower using the full borrowing limit. Holding NEXO introduces another asset exposure, and maintaining lower LTV ties up more collateral. Gold and Platinum clients can turn on a Low-interest borrowing setting, which moves assets from Flexible Savings into the credit line’s collateral wallet when LTV goes above 20%. Interest can rise when a tier or LTV condition changes.
Repaying in crypto costs 0.26%, with stablecoins and FIATx exempt. FIATx represents fiat-linked account balances. Crypto and stablecoin repayments are also converted at an exchange price that includes Nexo’s spread, which FIATx repayments avoid. The asset used to repay therefore changes the total cost.
Repayment within 45 days of the latest credit draw adds interest at a 17.9% annual rate on the repaid amount for the days remaining in that window.
For example, a repayment 15 days after the latest credit draw leaves 30 days in the early-repayment window. A new draw resets the reference date, though credit drawn through the Nexo Card does not start or extend the window. For a short borrowing period, this extra charge can outweigh the benefit of a low ongoing rate.
Collateral, Loan Amounts, and LTV
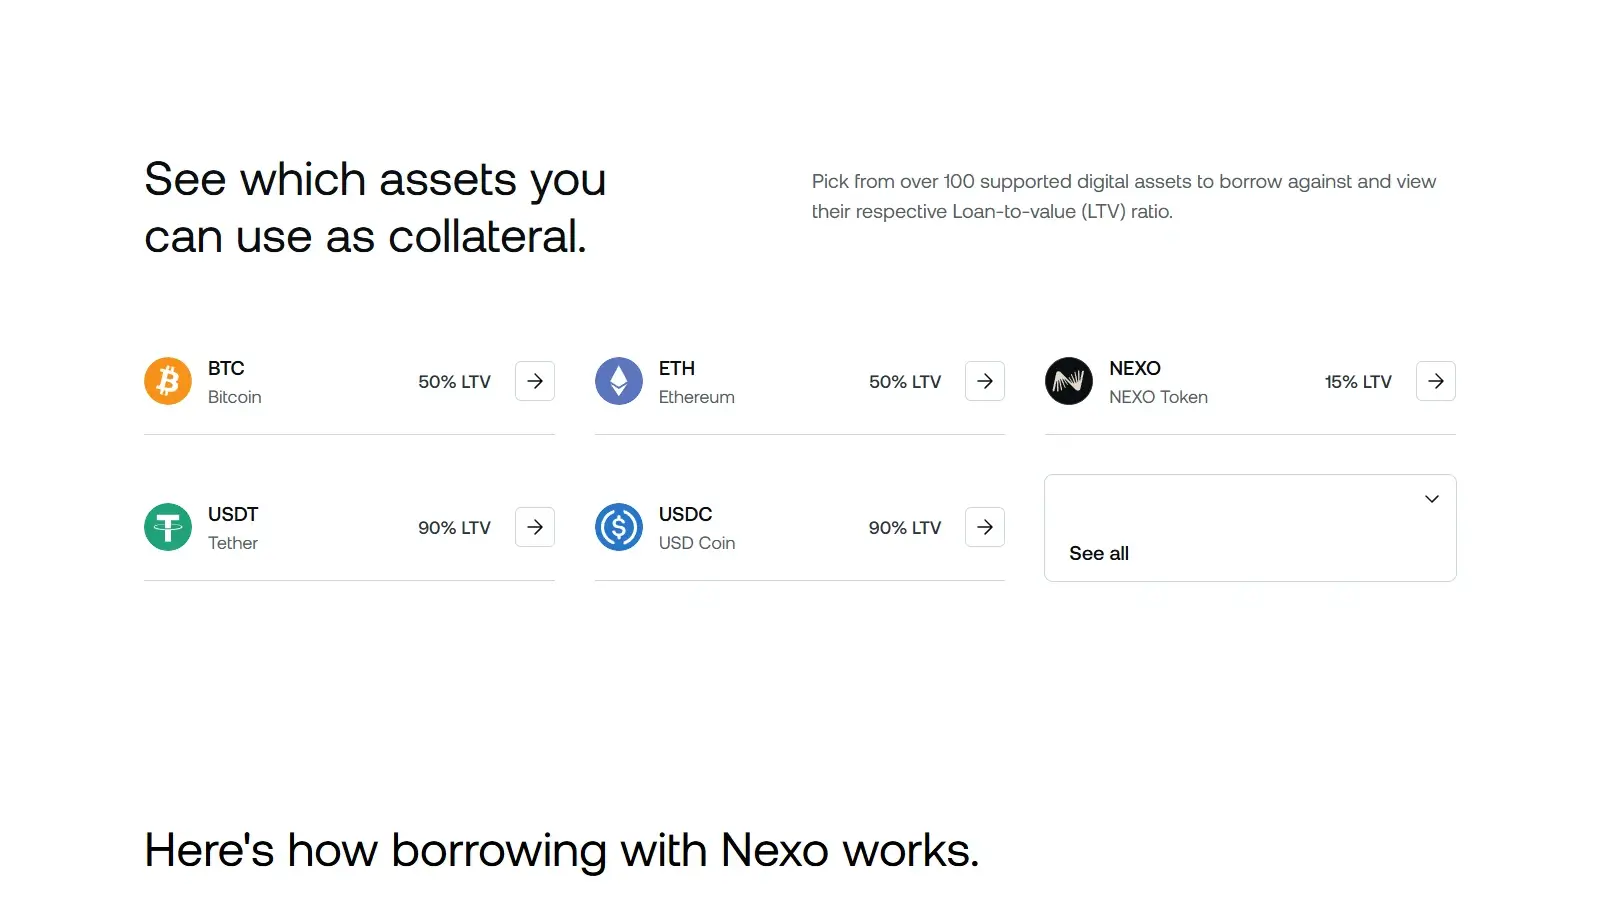
The Bitcoin (BTC) borrowing limit is 50% LTV. Other accepted assets have different limits, and a mixed collateral balance changes the loan’s risk profile.
For illustration, $10,000 of debt against $20,000 of BTC gives 50% LTV. The same debt needs more than $50,000 of collateral value to bring LTV below 20%, assuming no accrued interest. Qualifying for the lowest rate therefore means borrowing well below the maximum ratio.
The minimum draw is $50 equivalent for an internal payout and $500 equivalent for a bank transfer. Draws are limited to $2 million equivalent per day. That is a daily limit on new borrowing, rather than a limit on how much can be owed in total.
Nexo displays debt in xUSD, its in-app dollar unit, whichever payout is chosen. Eligible routes include stablecoins and bank transfers in supported currencies, so the money received can differ in currency from the displayed debt.
Liquidation and Collateral Management
For crypto-only collateral, the automatic-repayment threshold is 83.33% LTV. Nexo sells collateral to reduce the debt when that level is reached. Stablecoin-only and mixed balances use different thresholds. Nexo can also sell collateral in other circumstances defined by the rest-of-world contract, without guaranteed advance notice.
Nexo may send warning emails at 71.4%, 74.1%, and 76.9% LTV for a crypto-only balance. These alerts provide no guaranteed pause before a sale. Fast price drops can increase the amount of collateral Nexo sells to reduce the loan’s LTV. Each automatic sale also carries a liquidation fee of 2% to 3.5% on crypto collateral, or 1% on stablecoins, plus the exchange spread.
After a warning, adding collateral or repaying part of the balance lowers LTV. Repaying to avoid a sale can still incur the 45-day early-repayment interest.
Automatic Collateral Transfer can move eligible assets from savings into the relevant credit wallet. Allowing transfers from fixed-term savings adds another source of collateral, but ending a term this way forfeits its accrued savings interest. The setting can protect the credit line at a cost elsewhere in the account.
These controls apply separately to each credit line, so assets in another collateral wallet are not an automatic reserve for Classic. The funded balance and selected transfer settings determine which assets can support the position.
Custody, Collateral Use, and Security
Under the rest-of-world contract, Nexo can lend, pledge, and transfer collateral in other transactions. Return therefore depends on Nexo and the parties using those assets, even if Bitcoin’s price keeps the loan healthy.
You hold no private keys to the collateral. Through your Nexo account, you can add collateral, remove part of it while the line is healthy, or swap assets, but Nexo controls the assets throughout. Access still depends on Nexo and the parties handling the collateral, including when your account is restricted.
The credit line uses the custodial account covered in our Nexo wallet review, with additional contractual permissions over assets pledged for borrowing.
Availability, KYC, and Credit Checks
The rest-of-world agreement excludes the US, UK, EEA, and several other markets, including Canada, Switzerland, Australia, New Zealand, and the UAE. Nexo markets separate regional products in some of those locations, including the US and UK.
The US tier-based pricing program has its own rules. The UK offer pays out digital assets, with conversion to bank funds as a separate step. Those regional agreements and pricing programs determine the borrower’s interest rate and settlement costs.
Nexo advertises no credit check but requires know-your-customer (KYC) identity and compliance checks. Country and state eligibility requirements apply separately.
Application, Payout, and Timing
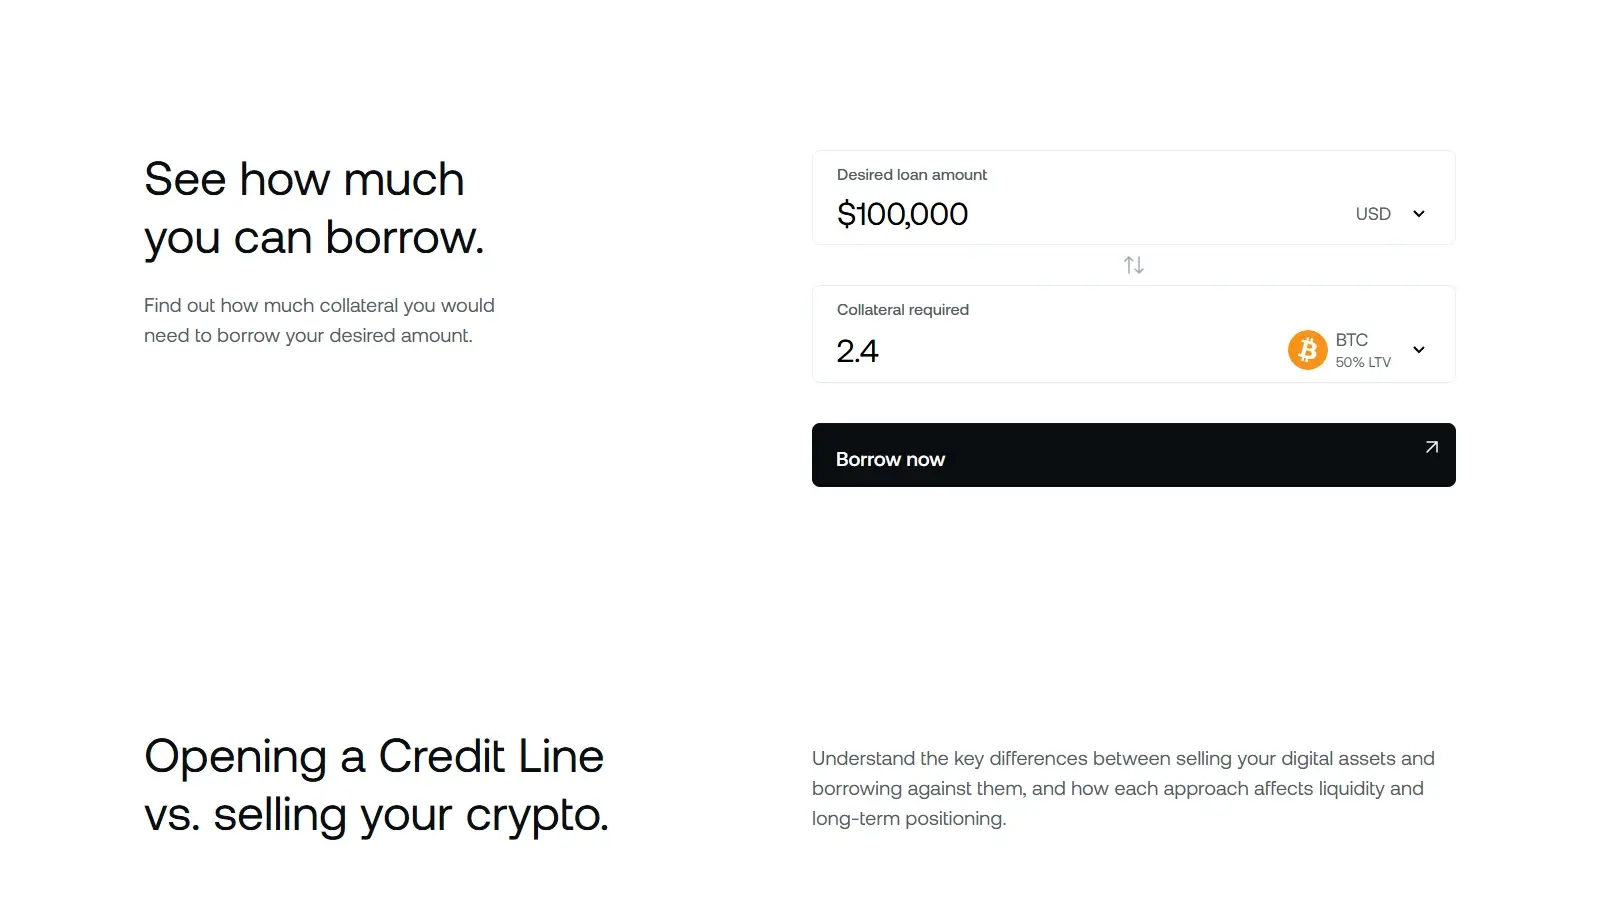
A Classic draw uses eligible collateral already held in the Nexo account. The asset, amount, and payout route determine how much can leave the account, so the displayed credit limit alone does not establish how much reaches an external wallet or bank.
Nexo estimates minutes for an internal payout, the same or next business day for a local bank transfer, and one to five business days for an international transfer.
Compliance review can add time before approval, and an internal stablecoin payout still needs a withdrawal to reach an external wallet. Someone paying an external expense needs to allow for both stages after choosing the faster internal route.
Repayment, Renewal, and Collateral Return
You can repay the Classic line in parts or in full. Supported balances include eligible crypto, stablecoins, and FIATx. Payments clear fees first, then interest, then principal.
Ordinary interest compounds daily, using the actual elapsed days and a 360-day year under the rest-of-world terms. Applicable early-repayment interest is also added to the outstanding balance. Because payments clear fees and interest first, repaying only the original draw can leave principal outstanding, with further interest accruing on that remaining debt.
The contractual term is 12 months, with annual extension unless terminated under the agreement. Each new draw restarts that 12-month maturity. The revolving structure allows further draws within the available limit, but the agreement’s term and termination rules determine how long the line stays open.
After full settlement, remaining collateral is released from that credit obligation within the Nexo account. An external withdrawal remains subject to the account’s transfer rules and fees.
Account Controls and Support
The Credit Hub shows each line’s balance, collateral wallet, and settings. New borrowing through Nexo’s leveraged-purchase Booster feature or its card stays on Classic unless the customer opens a dedicated line for that activity. Earlier balances remain on Classic, so opening a separate line does not move existing debt.
The repayment screen shows the payment asset, credited amount, and charges, allowing the customer to distinguish the amount spent from the debt reduced. Nexo advertises 24/7 client support, but LTV continues moving while a ticket is open. A position needing more collateral or repayment still needs that action before the sale trigger.
Alternatives
-

Ledn
Ledn’s Dollar Loan uses a 12-month term and allows early repayment without a prepayment penalty. Its 2% administration fee applies outside the US and Canada and is included in the annual percentage rate (APR). Ledn’s custody policy permits funding pledges while prohibiting lending BTC for yield, changing the collateral-use permissions compared with Classic. The offer still needs to be available in the borrower’s country.
-
Coinbase Borrow
Coinbase Borrow serves eligible US customers outside New York, with limited UK and Canadian access under separate regional rules. A comparison in those countries needs a local Nexo offer because Classic’s rest-of-world contract excludes them. Coinbase’s US BTC-backed variable loan pays out USD Coin (USDC) through Morpho on Base, adds processing fees to debt, and has no scheduled maturity.
Pillar Scores
- Cost and pricing clarity 20% weight Interest, mandatory fees, pricing conditions, and the cost of early repayment.5.0 / 10
- Collateral control and counterparty risk 25% weight Custody, permitted collateral use, and recovery rights.3.0 / 10
- Liquidation rules and risk controls 20% weight Sale triggers, warnings, penalties, and tools for managing collateral.6.0 / 10
- Repayment and flexibility 15% weight Partial payments, maturity, renewal, and collateral return.7.0 / 10
- Access and funding 10% weight Eligibility, verification, payout routes, and usable funds.6.0 / 10
- Account controls and support 10% weight Security controls, loan records, monitoring tools, and customer support.7.0 / 10
Final Verdict
Nexo Credit Line fits eligible borrowers who want to draw again after repaying and can leave enough time between a new draw and repayment to avoid the extra interest. They must also accept keeping collateral on a custodial platform. Each new draw restarts the 45-day count, making repayments within that window more expensive. The lowest advertised rate requires both token holdings and substantial collateral headroom. The permission to lend and re-pledge collateral adds counterparty risk. A borrower expecting a quick payoff or requiring tight limits on collateral use has good reasons to compare alternatives.
Best For
Eligible crypto holders who need repeated credit draws and can keep a collateral buffer
Avoid If
- Borrowers planning a quick payoff after a new draw or requiring strict limits on collateral reuse
CryptoSlate may earn a commission when you use partner links, at no extra cost to you. Our reviews, ratings, and editorial decisions remain independent of advertisers. Read How CryptoSlate Makes Money for funding details.