Quick Take
- A House panel approved the Digital Asset Tax Certainty Act 38-5, advancing the broadest federal crypto tax framework yet.
- The bill would ease treatment for payments, lending and some business activity while extending wash-sale and other anti-abuse rules to digital assets.
- Crypto groups are already pressing Congress to widen everyday-payment relief and change when staking and mining rewards become taxable.


Crypto groups are pressing Congress to broaden tax relief after a House panel advanced the first digital-asset tax framework.
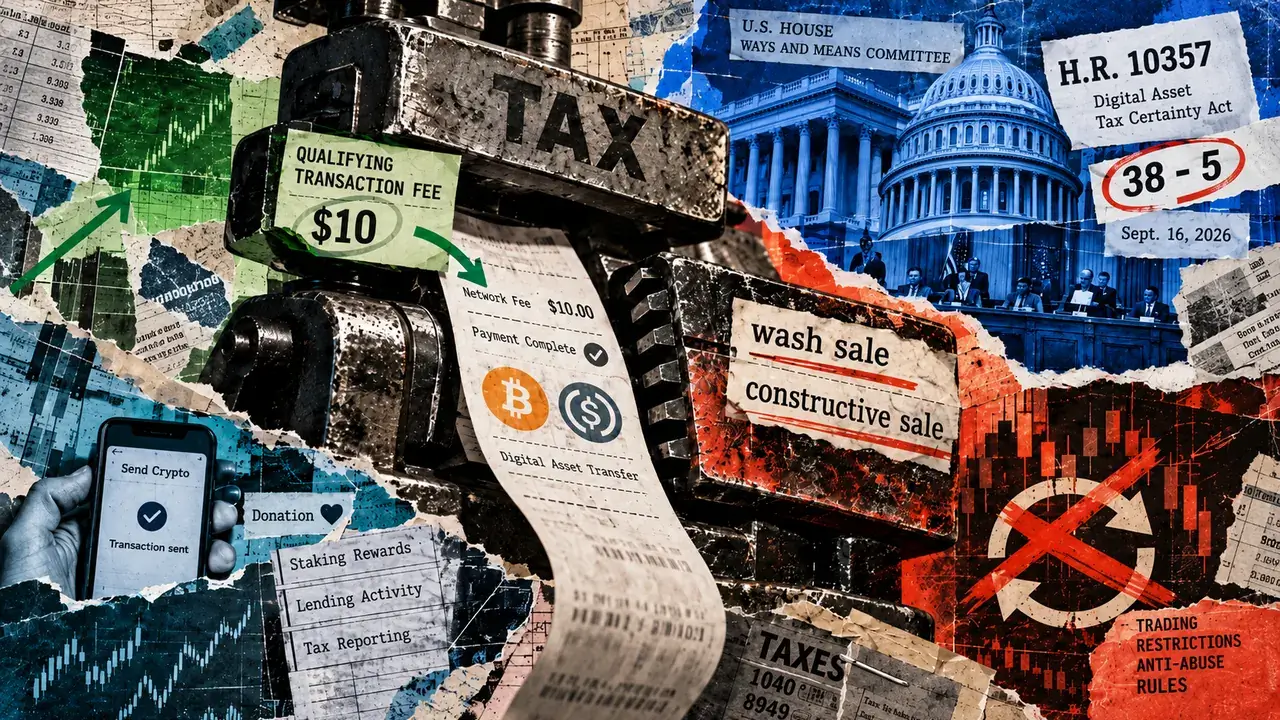
The House Ways and Means Committee approved H.R. 10357, the Digital Asset Tax Certainty Act, by 38-5 on Sept. 16, sending a package covering crypto payments, stablecoins, trading, lending, staking and mining toward the full House. The committee ordered the amended bill favorably reported after adopting Chairman Jason Smith’s substitute.
Industry groups welcomed the vote while signaling that the legislation remains short of several priorities they want addressed before final passage. Those include broader relief for everyday crypto transactions and changes to when staking and mining rewards become taxable.
Alison Mangiero, chief strategy officer and head of US policy at the Crypto Council for Innovation, called the committee vote a historic step but said lawmakers still have room to refine the timing of income recognition for staking and mining rewards and expand de minimis treatment for ordinary digital-asset transactions. CCI had raised similar issues with lawmakers before the markup.
That leaves the industry trying to build on a bill that grants several long-sought tax concessions while stopping short of removing some of the frictions crypto advocates say make digital assets difficult to use for payments and network participation.
Industry wants payment relief to go further
The bill would eliminate gain-or-loss recognition when digital assets are used to pay qualifying network and transaction fees of no more than $10, beginning with dispositions after Dec. 31, 2027. For transaction fees, the asset used to pay the charge generally must be the same type as the asset involved in the underlying transfer.
That addresses a narrow consequence of the Internal Revenue Service treating digital assets as property: spending crypto to cover a blockchain fee can itself create a taxable disposition.
CCI wants Congress to go further by providing broader de minimis relief for everyday digital-asset transactions. The distinction is significant because H.R. 10357’s $10 provision covers qualifying fees rather than creating a blanket exemption for small purchases made with crypto.
The package separately provides special treatment for qualifying US dollar stablecoins and creates a simplified accounting election for widely traded digital assets.
It would also extend existing financial-market treatment to other parts of the industry, including lending safe harbors, mark-to-market accounting for eligible dealers and traders, and streamlined rules for certain charitable donations. The committee describes those provisions as an effort to bring digital assets closer to comparable traditional financial instruments.
The concessions come alongside tighter rules for investors. H.R. 10357 would extend wash-sale and constructive-sale provisions to digital assets, closing tax strategies that have remained available because cryptocurrencies generally fell outside rules already applied to securities and other financial instruments.
Staking leaves a key industry request unresolved
Mining and staking represent a more consequential unfinished issue for the industry.
The legislation would explicitly treat income from digital-asset validation activities as ordinary income and establish sourcing rules based on where the taxpayer or relevant business operation is located. It would also allow qualifying investment trusts to stake assets without losing their trust status solely because of that activity.
What it does not provide is the optional deferral sought in earlier proposals that would have allowed some miners and stakers to delay recognizing newly created tokens as income until they were sold. The current package establishes the character of validation income while leaving the timing question that CCI wants Congress to revisit.
That issue can affect operators that receive token rewards without receiving cash at the same time. Immediate recognition can create a tax liability before the underlying tokens have been sold, leaving miners and validators exposed to price movements between receipt and liquidation.
The industry did secure another provision aimed at crypto organizations established outside the US. The bill directs Treasury to issue guidance within 12 months on the tax treatment of foreign entities associated with decentralized autonomous organizations, including methods for qualifying foundations to reorganize as domestic corporations and potential temporary safe harbors for entities formed before Sept. 14.
Miles Jennings, head of policy and general counsel at a16z crypto, said the legislation could provide clearer rules for entrepreneurs while creating a route for crypto foundations to return to the US under a domestic tax structure.
CCI’s Mangiero similarly cited the DAO provision as one that could encourage innovation and jobs to move back to the US, while arguing that the broader package still requires technical changes.
Editorial credits