
Quick Take
- Michael Saylor declared a new Bitcoin bull market as Strategy reported record third-quarter operating income of $20.9 billion.
- Despite increasing its Bitcoin holdings by 26% this year, Strategy's BTC yield fell to negative 3.7% amid substantial fundraising.
- K33 questions whether STRC's costly financing justifies its Bitcoin gains, while Bitwise argues investors are overpricing the risks.

Strategy posted a record $20.9 billion in third-quarter operating income as Michael Saylor declared a new Bitcoin bull market.
The company's Oct. 29 financial results showed net income of $19.5 billion, compared with roughly $2.8 billion a year earlier. The record operating income came almost entirely from a $20.9 billion gain from changes in the fair value of its Bitcoin holdings.
The results reinforced Saylor's optimism about Bitcoin's prospects. He said banks were increasingly embracing the cryptocurrency, institutional demand had returned, and Bitcoin was trading 21% above its 200-week moving average.
Saylor declared:
“We're at the beginning of the next Bitcoin bull market.”
His assessment comes as Strategy has expanded its Bitcoin holdings by 26% this year to 848,517 BTC, worth approximately $68.9 billion at the company's Oct. 23 reference price.
However, that accumulation has not translated into stronger Bitcoin exposure per share, raising questions about the effectiveness of its increasingly complex financing strategy.
Strategy's Bitcoin-per-share yield reverses despite record profits
Despite its record earnings, Strategy reported a -3.7% year-to-date BTC yield as of Oct. 25, a sharp reversal from the 4.5% reported in July.
The 8.2-percentage-point deterioration occurred even as its Bitcoin holdings increased from 843,775 BTC in late July to 848,517 BTC in October.
Strategy's BTC yield measures the percentage change in Bitcoin holdings per assumed diluted share, assessing whether its accumulation is outpacing potential dilution rather than tracking actual shareholder investment returns.
The deterioration also showed up in Strategy's other performance indicators. Its BTC Gain metric fell to -24,947 BTC, while its corresponding BTC dollar gain stood at -$2.03 billion, based on Bitcoin's price of $81,200 on Oct. 23.
The divergence is particularly notable given Strategy's aggressive fundraising.
The company raised approximately $21.2 billion through capital markets transactions during the first 10 months of 2026. During the third quarter alone, it generated $5.4 billion in net proceeds from common stock sales but used just $588.1 million of those proceeds to purchase Bitcoin.
Meanwhile, Strategy's Bitcoin treasury increased by only 1,666 BTC during the quarter, after the company purchased 7,218 BTC and sold 5,552 BTC.
Its financial performance also remained heavily exposed to Bitcoin's price fluctuations. Despite the extraordinary third-quarter recovery, Strategy recorded a net loss of $1.23 billion for the first nine months of 2026, reflecting the impact of earlier declines in its cryptocurrency holdings.
Nevertheless, its stock market performance followed a different trajectory. MSTR shares appreciated 76% during the third quarter, outperforming Bitcoin's 43% gain over the same period.
Strategy's costly STRC financing divides analysts
Strategy's expanding preferred-stock financing model has drawn contrasting assessments from analysts over its costs and financial sustainability.
Central to the debate is STRC, a variable-rate perpetual preferred security that allows Strategy to raise capital for Bitcoin purchases without immediately issuing additional common shares.
However, its 12% annualized dividend rate creates recurring obligations that must be funded alongside further Bitcoin accumulation.
Those costs have become increasingly visible.
Strategy disclosed that it had sold approximately $431.8 million worth of Bitcoin in 2026 to help finance preferred stock dividends and STRC repurchases.
The company also spent over $2 billion repurchasing approximately 20.98 million STRC shares, while cumulative preferred dividends paid reached nearly $1.5 billion.
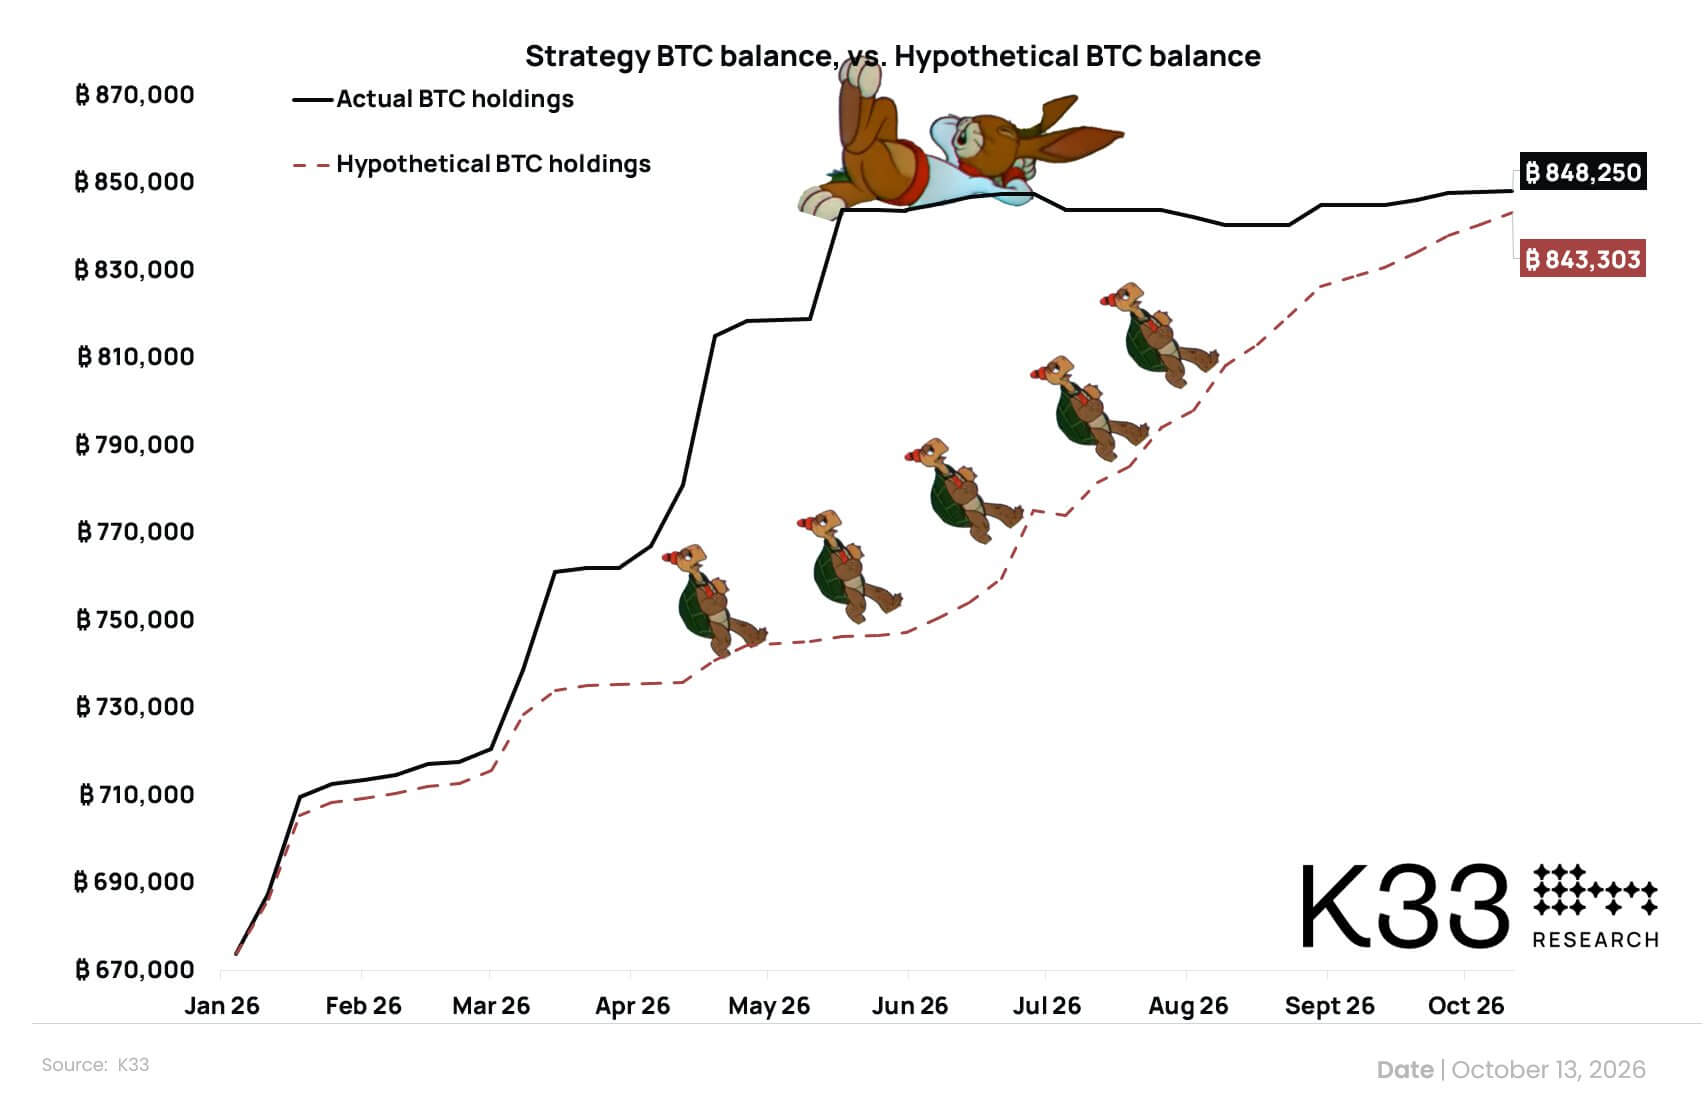
Vetle Lunde, head of research at K33, argued that Strategy could have achieved nearly the same Bitcoin accumulation without relying so heavily on STRC.
His hypothetical model assumed that funds allocated to building dollar reserves, repurchasing STRC and paying most STRC dividends were instead used to purchase Bitcoin.
Under those assumptions, Strategy would have held approximately 843,303 BTC as of Oct. 12, compared with its actual holdings of 848,250 BTC.
The difference of just 4,947 BTC came with approximately $725 million in additional annual dividend obligations tied to STRC's expansion, according to K33's estimates.
 Strategy’s actual versus hypothetical Bitcoin holdings
Approximate values digitized from the published chart. Historical balances are rounded to the nearest 1,000 BTC; weekly dates are estimated within about two days. The Oct. 12 endpoints use K33’s printed values. K33’s hypothetical path redirects dollar reserves, STRC buybacks and most STRC dividends into Bitcoin.
 CryptoSlate
“The tortoise wins,” Lunde concluded, favoring a more straightforward Bitcoin accumulation strategy over the additional financing costs.
However, André Dragosch, Bitwise's European head of research, offered a substantially more favorable assessment of Strategy's financial position.
In an Oct. 29 commentary, Dragosch challenged Strategy's B- credit rating, arguing that its financial strength compared favorably with that of highly rated corporate borrowers. He stated:
“Strategy‘s credit instruments are yielding like a junk bond with an investment grade credit quality.”
Based on traditional corporate credit metrics, he suggested Strategy could justify a rating closer to AA or AAA, potentially bringing STRC's yield toward 6% instead of its current level near 12%.
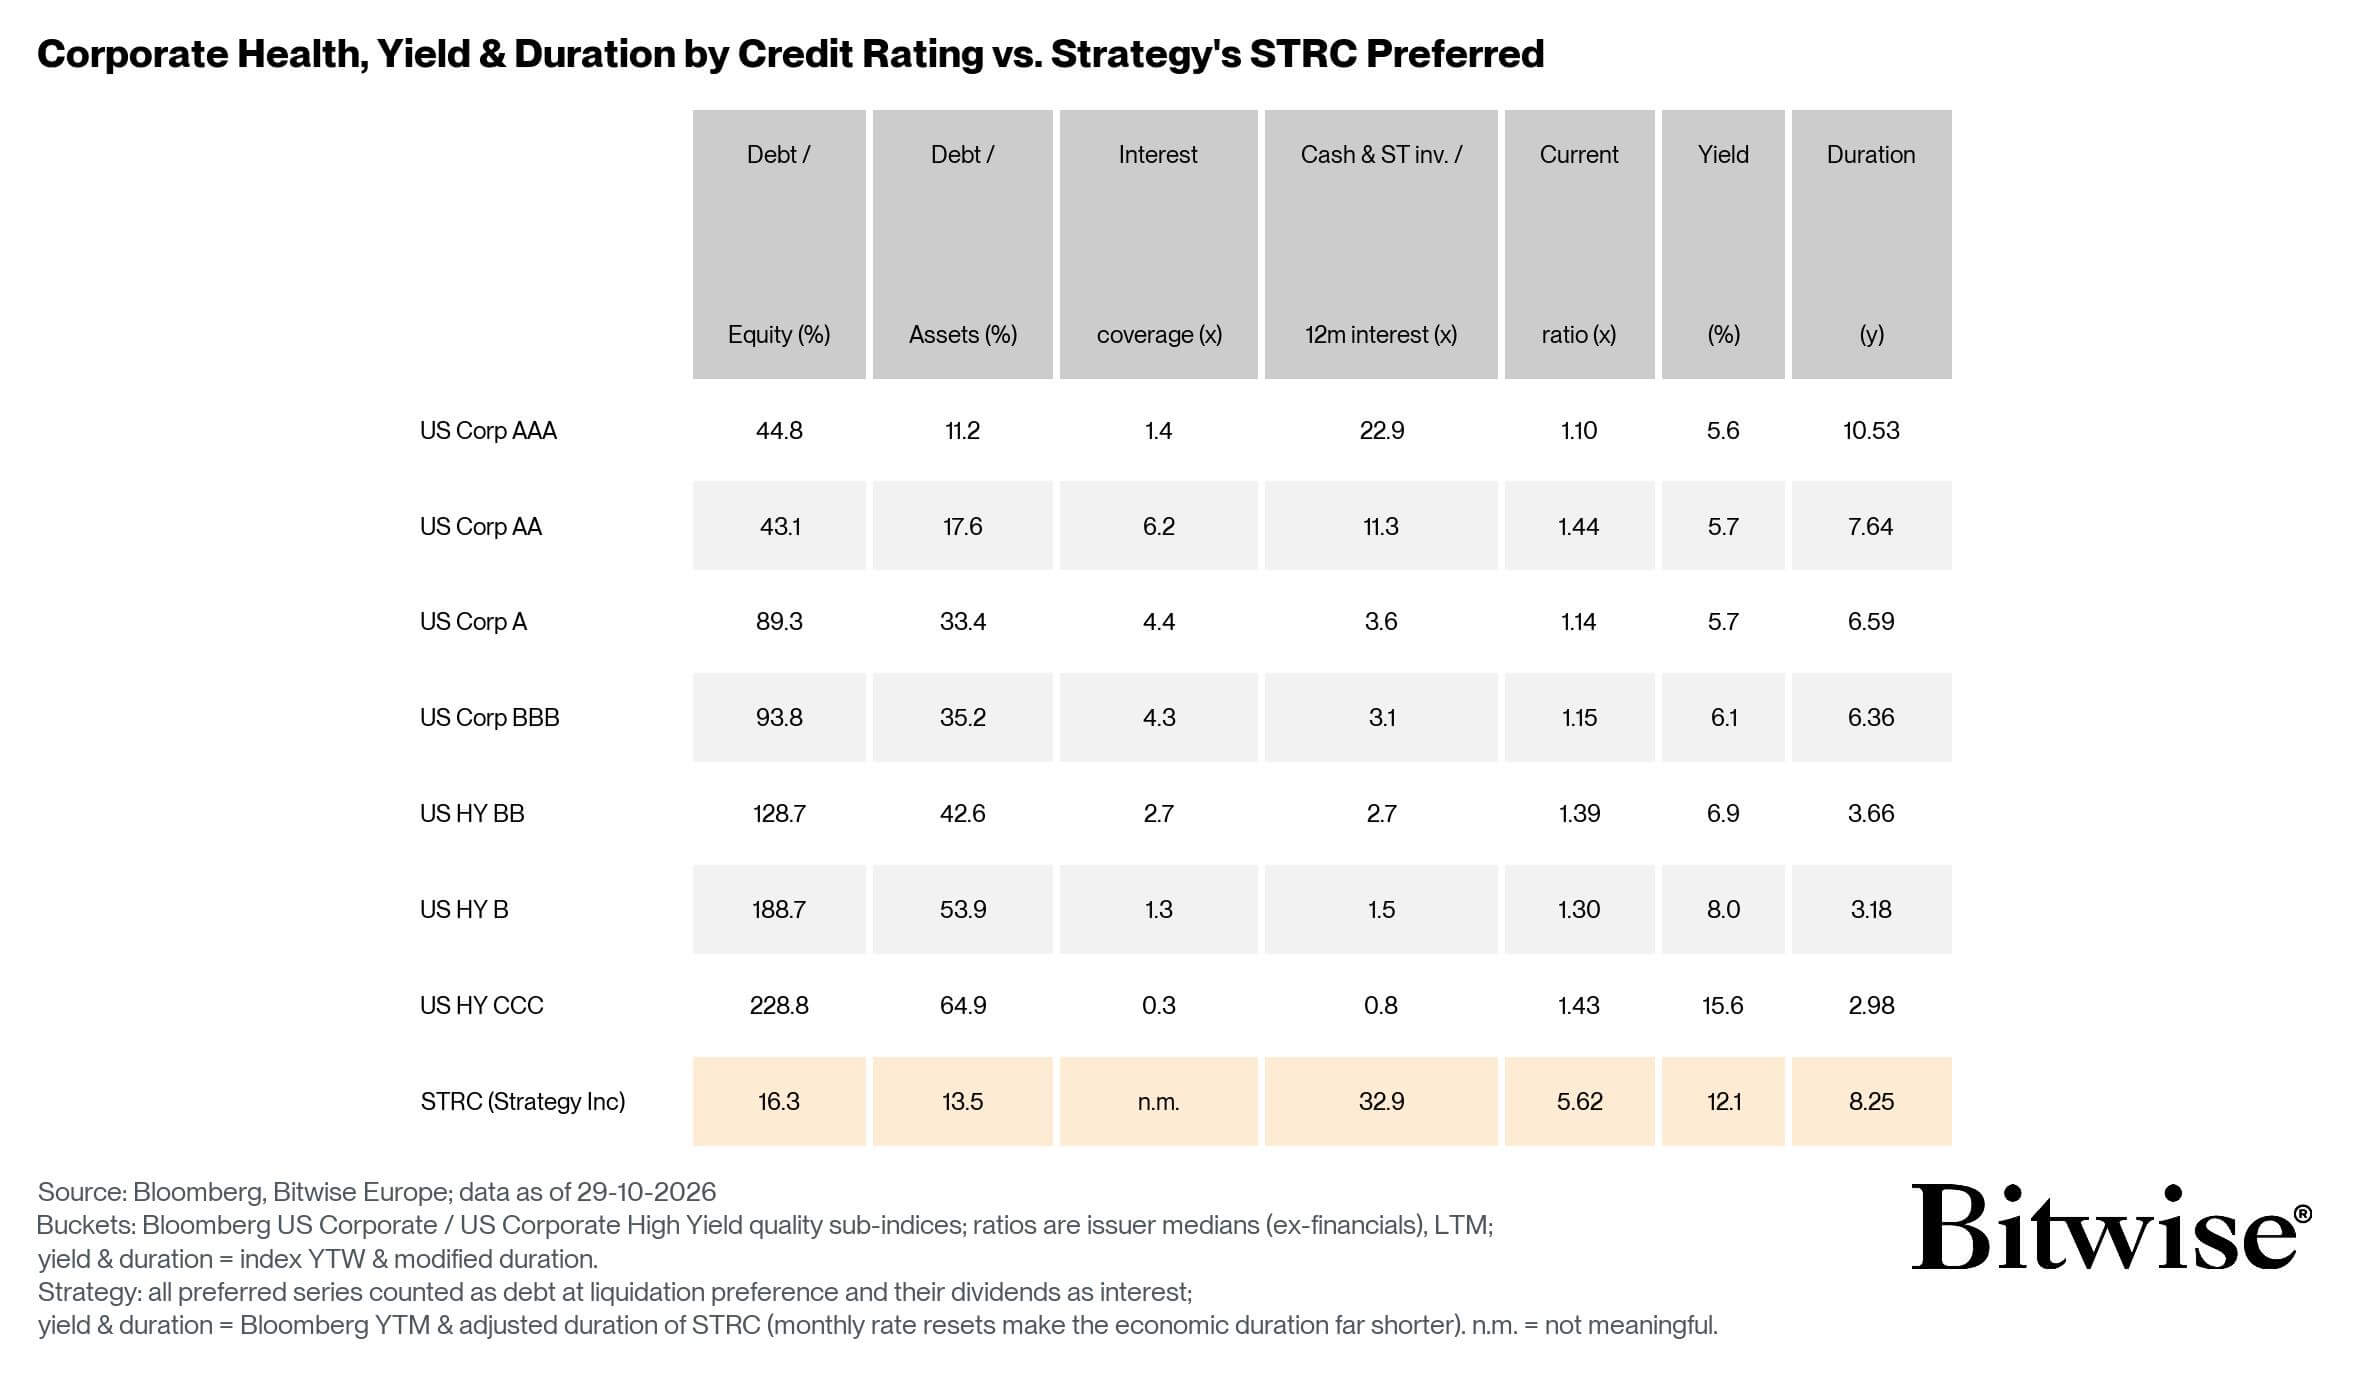
However, the comparison has limitations. STRC is a perpetual preferred security rather than a conventional corporate bond, while Strategy's Bitcoin exposure introduces price volatility and capital-structure risks that traditional liquidity ratios do not fully capture.
K33 questions whether STRC's recurring dividend costs justify its contribution to Bitcoin accumulation, while Bitwise argues that investors may be demanding excessive compensation for the financial risks of holding the security.
Meanwhile, Strategy has strengthened its liquidity position to support its expanding financial obligations.
The company reported approximately $5 billion in designated dollar assets, which it estimates could cover 3.4 years of preferred dividend and interest payments at current rates.
CEO Phong Le said the company had also undertaken substantial STRC repurchases to support the security's financial health.
Following shareholder approval on Oct. 28, Strategy will introduce daily dividend accrual for STRC in November, with similar arrangements scheduled for its other preferred securities in January 2027.
Mentioned in this article


Editorial credits