Quick Take
- Aave implemented a lower 92% USDT rate threshold on Oct. 21, bringing steeper borrowing costs forward.
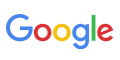
- At identical hypothetical 94% utilization, the new curve gives 7% borrowing APR against 4.5% under the published prior curve.
- The modeled 57.8 million USDT buffer increment creates no cash.

Aave has lowered the utilization threshold at which borrowing rates for Tether’s USDT rise sharply on its Ethereum Core market, making loans more expensive sooner as pool liquidity tightens.
Using the supply balance in an Oct. 20 recommendation by DeFi risk service provider LlamaRisk, the shift corresponds to roughly 57.8 million USDT more modeled unborrowed liquidity at the threshold.
The change was executed on Oct. 21 in Ethereum block 26,241,799. The threshold fell from 94% utilization, the share of borrowed pool liquidity, to 92%. Borrowers can still go beyond that point, but the rate climbs more sharply once they do.
The trade-off for lenders is earlier pressure on borrowers to preserve withdrawal headroom. The intended cushion remains available to be borrowed or withdrawn.
The price of earlier withdrawal headroom
Aave’s two-slope model increases borrowing rates gradually up to an optimal utilization point, often called the kink, then more sharply between that point and full utilization. Lowering the kink moves the more expensive part of the curve earlier.
The deployed USDT parameters at the Oct. 23 block were a 92% optimal usage ratio, a zero base rate, a 4.5% first slope, and a 10% second slope. Those settings leave the rate at the kink at 4.5% APR and the rate at 100% utilization at 14.5%.
Comparing the curves at the same utilization reveals the cost difference. At a hypothetical 94% utilization, the published prior curve is exactly at its kink and charges 4.5% APR. Under the implemented curve, that same utilization is 2% into the eight-point range above the new kink.
The calculation is 4.5% plus 10% points multiplied by two-eighths, giving 7% APR. That is a conditional comparison at identical utilization, separate from the observed 4.23% borrowing APR on Oct. 23.
For a constant 1 million USDT loan, a 2.5% gap would amount to 25,000 USDT of additional simple annual interest if both modeled rates and the principal stayed unchanged for a full year.
The 92% threshold does not ban borrowing above that level, and the curve’s 14.5% endpoint does not establish that lenders will always have cash available.
LlamaRisk reported 2,892.2 million USDT supplied in its Oct. 20 recommendation. Keeping that supply fixed, a reserve operating at 94% utilization would leave 6% unborrowed, while 92% utilization would leave 8% unborrowed.
Those percentages correspond to 173.53 million and 231.38 million USDT, respectively, for a difference of 57.84 million USDT. It is the difference between two modeled operating points on the same supplied balance.
LlamaRisk separately reported about 417 million USDT already idle in its recommendation, when utilization was below either kink.
The rate update changes the terms under which borrowers consume liquidity. For the larger modeled buffer to emerge as actual cash, users must respond through the pool’s cash flows.
As funding becomes more expensive, a borrower may repay, while a supplier may find a higher interest rate attractive enough to add USDT. Borrowers can also accept the cost, and suppliers can withdraw before an inflow arrives. The curve encourages a response without fixing its size or timing.
Cash still controls a supplier’s exit
At block 26,254,517, timestamped Oct. 23 at 09:45:59 UTC, the reserve had about 2.9 billion USDT in outstanding supplier claims and 2.5 billion USDT in variable debt. Physical USDT held at the aToken contract stood at approximately 391.4 million.
The table separates supplier claims from the reserve’s physical token balance and its virtual accounting balance.
| Measure | USDT at the October 23 snapshot |
|---|---|
| aEthUSDT total supply | 2,888,069,680.855421 |
| Variable debt | 2,496,678,159.334926 |
| Physical underlying cash | 391,396,023.726517 |
| Virtual underlying accounting balance | 391,394,502.001385 |
The virtual balance is a separate accounting input used by the interest-rate strategy. Dividing debt by debt plus that balance puts borrow utilization at about 86.45%, below the new 92% threshold. Physical cash measures the tokens held, while the virtual figure enters the pricing calculation.
The same snapshot recorded a variable borrowing APR of about 4.23% and a supplier liquidity APR of 3.29%.
The Oct. 23 cash balance is a later observation, separate from LlamaRisk’s Oct. 20 model. It does not establish a causal effect of the rate change on deposits, repayments, or withdrawals.
The strategy calculates the supplier liquidity rate from the borrowing rate and the share of liquidity being used, after the reserve factor. At the Oct. 23 snapshot, that reserve factor was 10%, allocating part of borrowing interest to the protocol treasury.
A higher borrowing rate can consequently improve the return offered to suppliers, helping compensate them for leaving funds in the pool. However, accrued interest is distinct from underlying tokens becoming available for immediate withdrawal. Cash must still be present when a supplier exits.
Aave’s withdrawal guidance makes that condition explicit: suppliers can withdraw only against liquidity that is available and unborrowed. A supplier using deposits as collateral may also need to repay borrowings or add collateral to preserve the position's health before withdrawing.
Lending-pool cash serves a different purpose than the GHO conversion inventory and Umbrella deficit backstops.
The operational test is how deposits and repayments compare with borrowing and withdrawals as utilization changes.
Moving the kink to 92% makes the price respond earlier to tighter liquidity. Whether suppliers can exit immediately still depends on the cash left in the pool and, where their deposits secure borrowing, on the health of their own positions.

Tether is +0.01% over the past 24 hours and currently sits at rank #3 by market cap.
Mentioned in this article

Editorial credits