Quick Take
- Aave’s Core GHO borrow APR is indexed at 4.5%, matching the savings rate TokenLogic reported on Oct. 2.
- Repayments replenish GSM stablecoin inventory only when borrowers bring USDC or USDT into the modules to acquire GHO.
- Aave’s documented sGHO redemption returns GHO, while obtaining USDC requires a separate conversion with available inventory and liquidity.


Aave’s Ethereum Core market lists a 4.5% borrowing rate for GHO, aligning the stablecoin’s borrowing cost with the savings rate TokenLogic reported on Oct. 2.
The next test is whether the change brings USDC or USDT into the reserves available to savers who choose to convert withdrawn GHO into USDC or USDT.
Aave describes its savings token (sGHO) as redeemable instantly into GHO, so a holder who wants USDC needs a separate conversion. A higher borrowing rate can change the incentive to repay, but the route used to acquire that repayment GHO determines whether stablecoins enter the reserves.
The DAO service provider reported a depleted USDC GHO Stability Module (GSM) on Oct. 2, and said the rate increase should help replenish reserves if borrowers obtain repayment GHO through the modules.
The effect on reserves depends on borrowers bringing stablecoins into those modules, and the new rate alone does not demonstrate improved USDC conversion liquidity.
Aavescan’s Core GHO data dated Oct. 5 displays a 4.5% borrow APR. Its daily snapshots show 4.25% at midnight UTC on Oct. 3 and 4.5% at midnight on Oct. 4 and Oct. 5, locating the change between daily readings.
TokenLogic’s Oct. 2 notice proposed moving Core from 4.25% to 4.5%. It said borrowers could previously pay 4.25% to acquire GHO on Core and earn 4.5% in sGHO, leaving the DAO to fund the 25-basis-point difference. At an unchanged savings rate, the new Core rate eliminates that stated gap.
That alignment is specific to Core and the 4.5% savings rate reported on Oct. 2.
TokenLogic proposed a 3% base rate, up from 2.75%, and a 4.25% APR at optimal utilization, up from 4%. Aavescan’s Prime page displayed 4.17% on Oct. 5 at 86.35% utilization, versus 4.22% in its midnight snapshot.
Repayment replenishes reserves only through the right route
TokenLogic describes two ways a borrower needing GHO can acquire it: buy on the secondary market, or exchange USDC or USDT through a GSM.
Buying GHO can support its market price, while bringing stablecoins into a GSM adds the inventory that another GHO holder can later redeem against.
That makes a fall in outstanding debt an incomplete measure of conversion liquidity, since repayment can occur without USDC reaching a module. Improved conversion liquidity requires stablecoins entering the reserve, beyond any change in GHO debt.
Core’s midnight snapshots recorded 116 million GHO borrowed on Oct. 2 and 115.8 million on Oct. 5.
Aave’s native sGHO documentation says users deposit GHO, receive vault shares, and redeem those shares for GHO without a cooldown. It also says deposited funds are not rehypothecated.
Aave also documents a pause state and user-specific withdrawal limits. Those conditions affect live vault availability, separately from the inventory and liquidity needed to exchange the resulting GHO.
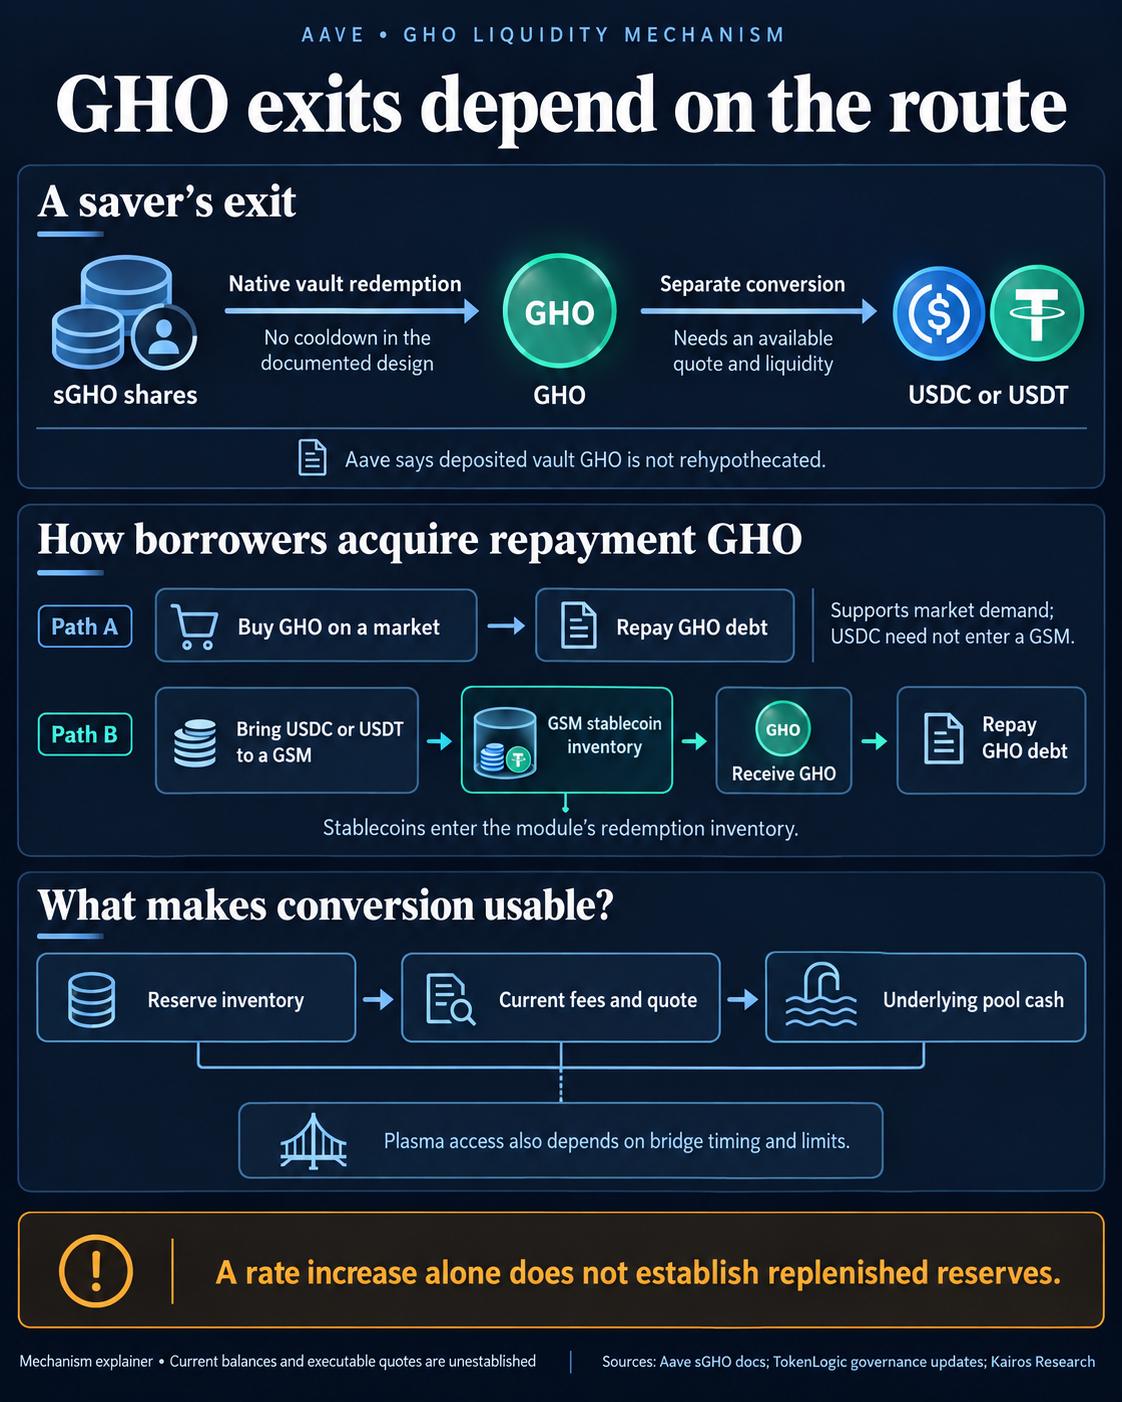
The RemoteGSM architecture, described by TokenLogic in March, makes the inventory distinction explicit. Governance-approved facilitators supply preminted GHO to a GhoReserve, and GSMs draw and restore it under assigned limits.
Room to distribute GHO is separate from the stablecoin inventory available for redemption. A higher limit can permit incoming swaps, but users still have to deliver the USDC or USDT.
Aave Labs’ institutional proposal reported 19.2 million USDT on Ethereum and 40.7 million on Plasma as of Sept. 24, totaling 59.9 million USDT. It excluded USDC instances because their redeemable balances were negligible.
TokenLogic’s Oct. 2 update reported approximately 22.5 million USDT in a USDT GSM without labeling the network scope. Comparing that figure with the earlier Ethereum-plus-Plasma total would not establish an aggregate decline. Neither statement supplies matched Oct. 5 balances.
Plasma provides a potential route to USDT inventory beyond Ethereum through Chainlink CCIP. Its usefulness depends on the time needed to bridge GHO and turn the module’s assets into usable stablecoins.
Kairos Research’s September analysis, using Sept. 8 readings, reported 40.6 million in nominal Plasma GSM redemption inventory against 38.6 million in underlying lending-pool cash.
Kairos also estimated at least 9.7 hours of rate-limit time to move 40 million GHO to Plasma under the bridge settings it measured. That assumed a full initial bucket and no competing traffic, and excluded message delivery and subsequent conversion steps.
Fees require the same care. TokenLogic’s September parameter notice proposed 15-basis-point USDC redemption fees on Ethereum, Monad and Arbitrum, a 10-basis-point Ethereum USDT fee and zero mint fees.
Its implementation language does not establish current executed fees. A usable exit depends on the current quote, inventory, and underlying liquidity together.
Institutional funding adds a duration test
Aave Labs seeks a 25-million-GHO facilitator and a separate route borrowing up to $25 million of USDC or USDT against DAO balance sheet assets. The planned initial balance-sheet route would use no GSM conversion inventory, and Aave Labs said on Oct. 1 that the proposal had advanced to Snapshot.
For the GHO route, the proposal prioritizes matched sGHO inflows, then secondary-market liquidity, then GSM reserves. TokenLogic’s Sept. 30 response adds a condition: matched inflows must last at least as long as the borrower’s draw.
That condition connects the rate story to the exit story. A matched inflow can provide lending currency while preserving GSM inventory at conversion, but TokenLogic argues that the funding must persist for the loan’s duration to resolve the liquidity pressure.
The duration condition applies to the proposed funding arrangement, while Aave describes deposited GHO in the native savings vault as held without rehypothecation.
Evidence of success would be stablecoin inventory arriving and remaining available for conversion, with executable routes that account for fees, pool cash, and cross-chain access.
Larger reserves or durable matched inflows could make exits easier. The higher Core APR establishes a change in borrowing cost, while its liquidity benefit depends on where the repayments and new deposits send the money.
GHO is -0.02% over the past 24 hours and currently sits at rank #212 by market cap.
Mentioned in this article


Editorial credits