 Released in 2018
- Daily fees for actual borrowing days
- Take Profit automatic price-based closure
- Fiat and crypto payout options
YouHodler Crypto-Backed Loan Overview
Key facts
- Product Name
- YouHodler Crypto-Backed Loan
- Release Date
- 2018
- Service model
- centralized
- Product status
- available
- Collateral & debt
- BTC, ETH · Other supported crypto; Debt currency: USD · EUR · GBP · CHF · Crypto
- Borrowing rate
- Individual quote required; individual quote; Daily fee on the borrowed amount, shown in the loan form · Higher when added to debt than when paid from the wallet
Additional details
- Offer scope
- YouHodler Get Cash; Get Cash crypto-backed loan under YouHodler SA’s Swiss terms. Residents of the US and Canada are excluded, along with China, India, Hungary, and other restricted regions. The Get Cash page presents the tariff as a crypto value ratio, so the loan form and individual agreement confirm the final terms.
- Amount & term
- $100 minimum · Up to 90 days · Conditional extension; Loan structure: Term loan; Minimum: USD · EUR · GBP · CHF · Crypto 100; Maximum: Not disclosed; $100 minimum · Maximum total borrowed amount varies
- LTV & liquidation
- Individual Price Down Limit closes the loan and sells collateral · UK offer up to 90% LTV · Other regions quoted · Overdue loans close after a 14-day period
- Fees
- Close Now 1% of the overdraft amount · Extend PDL 1.5% of added collateral · Increase LTV 1.5% of the increased amount · Conversion and withdrawal charges
- Repayment
- Full or partial · Wallet or external funding
- Availability
- US and Canada excluded · Regional restrictions; KYC: Required; Credit check: Unknown
- Payout
- Wallet first · Bank or crypto withdrawal
- Custody
- Custodial · Pledged collateral
YouHodler Crypto-Backed Loan Screenshots
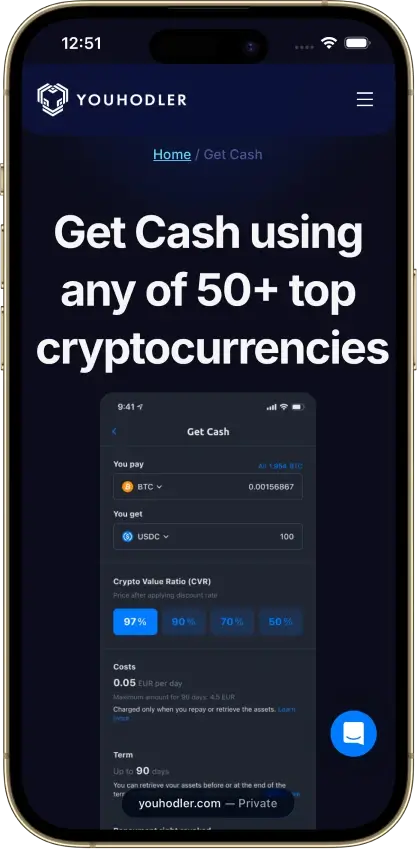
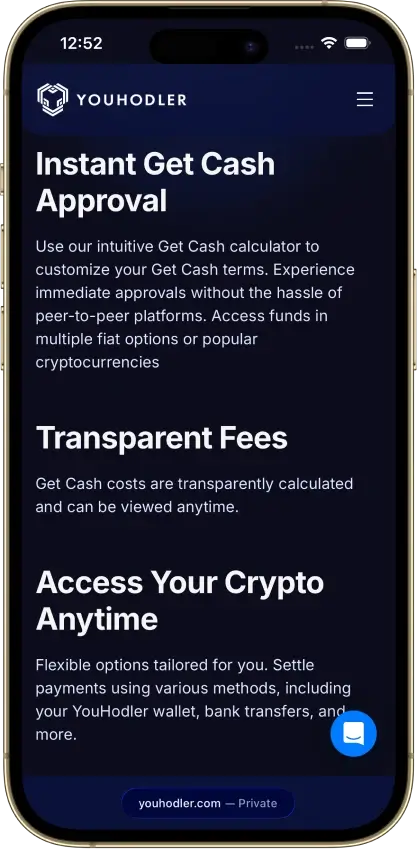
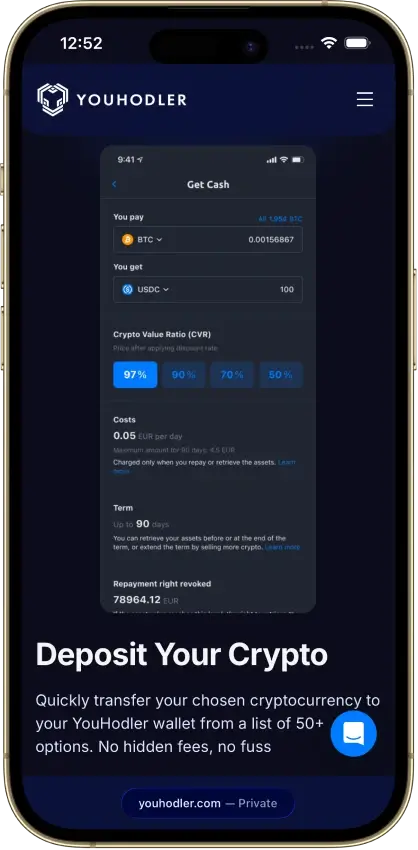
Screenshot 1 of 8
YouHodler Crypto-Backed Loan Pros and Cons
Pros
- Partial wallet repayments supported
- Collateral top-ups where offered
- Several loan-management controls
Cons
- Debt-funded daily fees cost more
- Collateral adjustments can incur fees
- US and Canadian residents excluded
Rates and Fees
YouHodler calculates its classic loan fee as a daily percentage of the borrowed amount, in the loan currency. The first charge falls 24 hours after opening, followed by daily charges at the same time. The fee applies to the days the loan remains open, with the exact percentage shown in the loan form.
If enough of the borrowed currency is available in the wallet, YouHodler collects the fee there. Otherwise, it adds the fee to the repayment balance at a higher rate. The calculation uses the borrowed amount without including accumulated charges in that base. Maintaining a wallet balance can therefore change the cost of the same underlying loan.
A displayed daily percentage cannot be read as an annual percentage. Multiplying it by 365 produces a simple annualized figure only under an unchanged daily fee and amount originally borrowed. Conversion charges, withdrawal fees, and paid loan controls are additional costs outside that annualized percentage.
Use the daily percentage from the loan form to estimate the cost for the days you expect to borrow. The total will be higher for any days when the wallet cannot cover the fee.
Optional action
- Close Now
1% of the overdraft amount
- Extend PDL
1.5% of additional collateral
- Increase LTV
1.5% of the increased amount
- Repay from a fiat wallet
0% repayment commission
Close Now displays its charge before confirmation, while Increase LTV and Extend PDL show revised loan terms. The Close Now charge uses the “overdraft amount,” the total debt shown as the actual loan balance, which can exceed the original amount borrowed. Currency conversions, bank withdrawals, and some deposit methods, such as Apple Pay, have separate charges.
The bank-withdrawal schedule charges 1.5% for a dollar SWIFT international wire, with an $85 minimum. A $1,000 withdrawal would therefore incur the $85 minimum under that schedule, or 8.5% of the withdrawal amount, before loan fees or any other bank charges. Small bank payouts can be substantially more expensive than their 1.5% rate suggests.
Collateral, Loan Amounts, and LTV
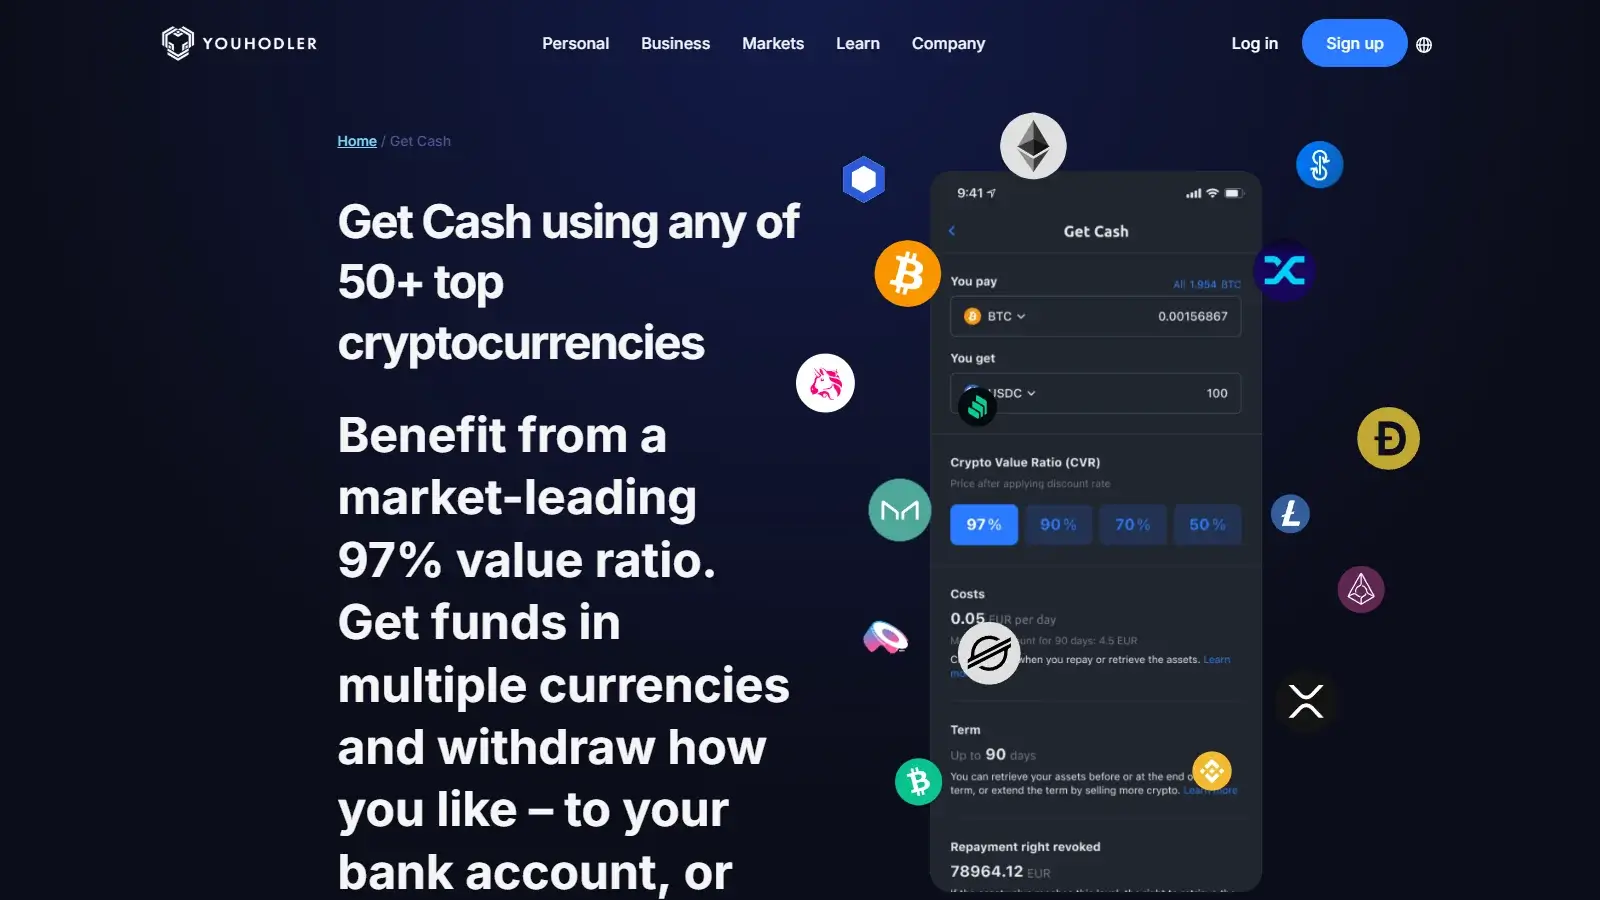
The classic loan form lets the borrower choose collateral, the amount to borrow, and a loan-to-value (LTV) tariff. Borrowers can use Bitcoin (BTC), alongside Ether (ETH) and other supported assets. Only the pairs available for the selected loan establish which assets can secure it. The minimum loan is $100, while the maximum total borrowed amount varies.
UK crypto-backed loans offer up to 90% LTV, subject to the borrower’s asset and quote. Outside that regional offer, the ceiling depends on the loan available locally. The Get Cash page also advertises a 97% “value ratio.” The LTV offered in the individual loan form sets the actual ceiling for the selected loan.
For illustration, at 90% initial LTV, a $9,000 loan against $10,000 of collateral leaves $1,000 between the debt and the collateral’s initial value. A 5% collateral-price decline raises LTV to about 94.74%, before fees. The actual liquidation point is set separately by the loan’s Price Down Limit.
Borrowing more through Increase LTV increases the debt without adding collateral. The platform offers that control only when the loan tariff and market conditions allow it, and shows revised loan terms before confirmation.
Liquidation and Collateral Management
Each classic loan has a Price Down Limit (PDL), a collateral price set in the individual agreement and loan details. When that price is reached, YouHodler closes the loan and sells the collateral, whether or not a warning has arrived. The PDL is a price, not the initial LTV percentage.
YouHodler sends advance notifications, but its help pages give conflicting warning points, so the PDL in the loan details is the figure to follow. After a PDL closure, YouHodler says no further payment is due and the borrower keeps the funds already received. The agreement determines whether any leftover collateral is returned.
Extend PDL adds collateral and recalculates the loan parameters. Availability depends on both the tariff and market conditions. Its fee is 1.5% of the additional collateral, so topping up changes both the amount at risk and the borrowing cost.
Take Profit closes the loan automatically at a price the borrower sets. Once set, it can be edited but not canceled.
Close Now sells collateral on request to repay the loan. That sale executes on crypto exchanges, so its final price and timing can differ from the preview. Both features use collateral and credit any remainder to the wallet.
YouHodler SA can also cancel services for security, compliance, or fraud reasons. With a loan open, the loan becomes immediately repayable or the company can retain collateral as repayment. The Swiss contract also allows cancellation of a Get Cash agreement affected by force majeure without an obligation to return collateral. These are contractual triggers beyond a price-based PDL.
Custody, Collateral Use, and Security
Under the Swiss Get Cash contract, the borrower pledges crypto to support the loan. YouHodler SA promises to keep client assets separate from company assets and off its balance sheet, while outsourcing custody and administration to YouHodler Italy S.r.l. SA remains contractually responsible, but another company holds the assets.
YouHodler SA’s general terms do not say whether pledged collateral can be lent or re-pledged. They point to separate Get Cash terms and an individual agreement issued after the loan opens. The permissions in those documents determine what use of collateral the borrower accepts.
YouHodler Italy S.r.l., the subsidiary that holds the crypto, became an authorized crypto-asset service provider in Italy under the EU’s Markets in Crypto-Assets (MiCA) rules on Oct. 8, 2026. That authorization covers custody, exchange, order execution, and transfers, with no lending, and YouHodler’s EU site does not offer Get Cash.
YouHodler describes a mixture of hot and cold storage and the use of Ledger Vault technology. The Ledger Vault pooled crime-insurance program it cites covers specified theft risks, leaving market losses and liquidation outside that protection. The program’s pooled limit of up to $150 million is shared across Ledger Vault clients. It does not insure each customer’s full balance.
After a company failure, recovering the pledged assets still depends on the agreement and insolvency process. The segregation promise gives the borrower no direct control over the crypto.
Availability, KYC, and Credit Checks
YouHodler excludes residents of the US and Canada, along with other restricted countries and territories. The restricted list also includes China, India, and Hungary. YouHodler SA also excludes US citizens and green-card holders wherever they live, as well as residents or citizens of China, including Macao. Customers must be adults and may hold only one account.
The regional rules distinguish access to the platform from access to particular services. UK access includes crypto-backed lending but excludes several rewards and yield products. Swiss customers can use crypto-backed loans. Singapore customers can use supported crypto services, including loans, but cannot make fiat deposits or withdrawals, leaving crypto or stablecoins as the payout options there.
YouHodler SA’s Swiss terms describe services for residents of Switzerland and EU member states, while the help center also covers UK and Singapore customers. The applicable regional offer and contracting entity therefore need to cover the borrower’s residence, even if it is absent from the restricted list.
Know-your-customer (KYC) identity checks and anti-money-laundering (AML) checks are required under the Swiss terms. Source-of-funds information can also be requested. Bank-wire access requires address verification. Clearing identity checks does not tell the borrower whether YouHodler also runs a credit check on the loan.
YouHodler is not authorized by the UK Financial Conduct Authority (FCA). Its Swiss contract identifies PolyReg affiliation without direct supervision by the Swiss Financial Market Supervisory Authority (FINMA). Neither status guarantees recovery of collateral, which remains subject to the applicable agreement and counterparty risk.
Application, Payout, and Timing
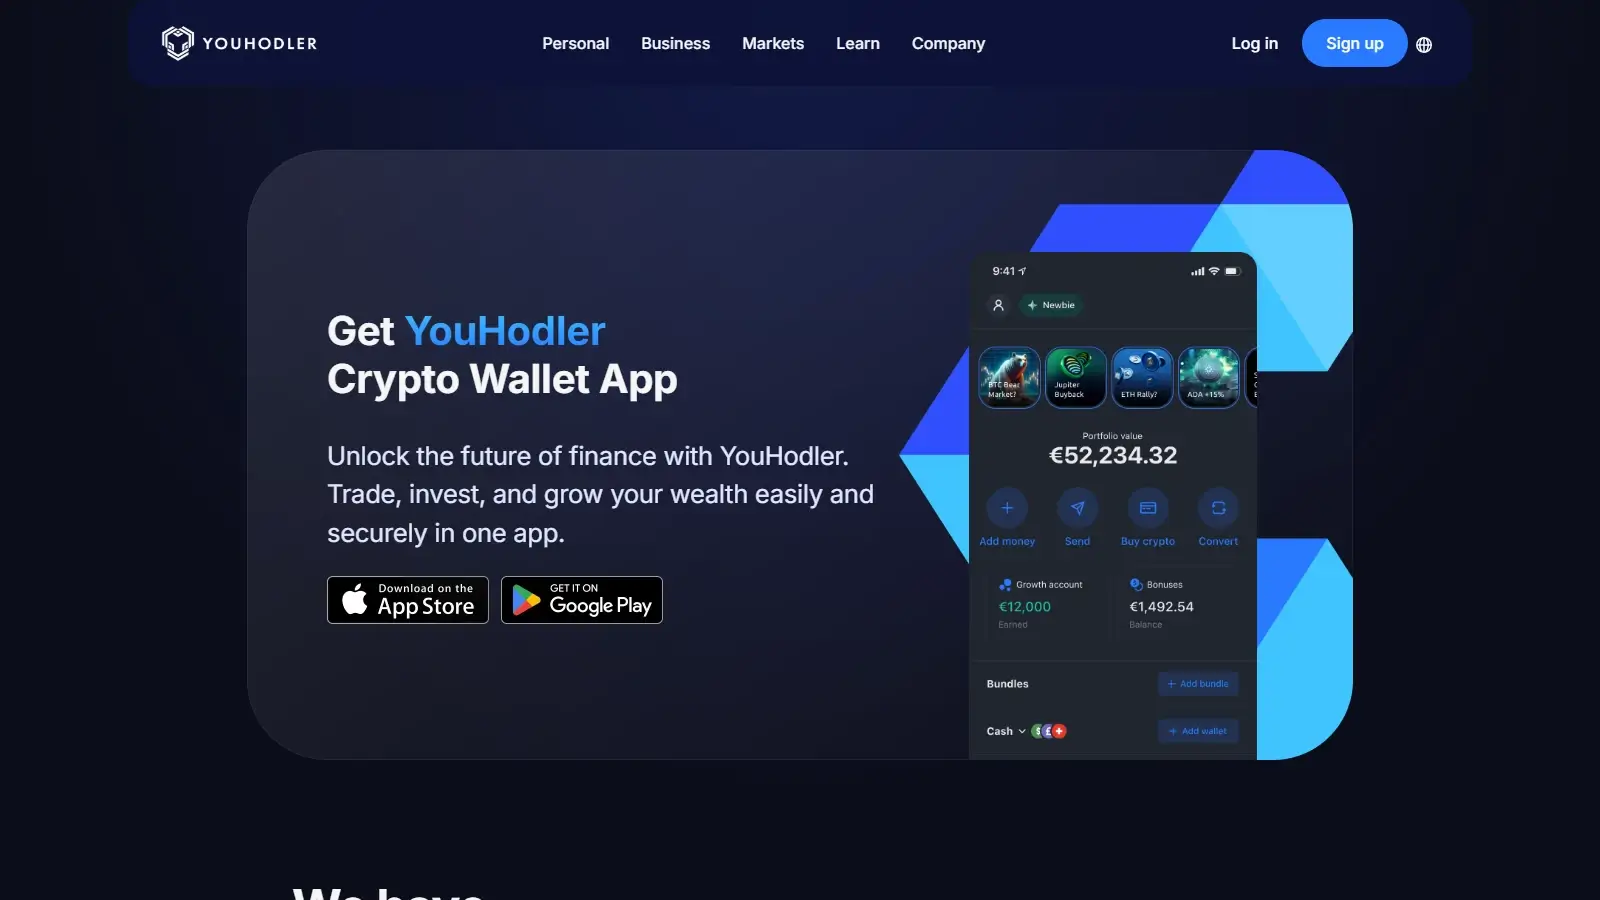
After account verification and funding, the borrower selects the collateral, loan currency, borrowing amount, and LTV tariff. The loan form calculates the required collateral and shows the terms for acceptance. Once the loan opens, the borrowed amount appears in the YouHodler wallet.
Receiving that wallet balance is only the first stage of a bank payout. A borrower then requests a withdrawal from the relevant fiat wallet, supplies bank details, and meets address-verification requirements. A currency conversion is also needed if the withdrawal currency differs from the available balance.
Bank-transfer approvals depend on the 10:00–17:00 Central European Time (CET) banking schedule, and dollar or euro SWIFT withdrawals require at least $500 or €500 respectively. YouHodler’s bank guide estimates up to two business days for euro Single Euro Payments Area (SEPA) withdrawals and up to five days for dollar Society for Worldwide Interbank Financial Telecommunication (SWIFT) withdrawals. It gives up to three days for British pound and Swiss franc transfers. These are provider estimates for the banking stage, and the applicable withdrawal minimum and fee depend on the route.
Repayment, Renewal, and Collateral Return
The From My Wallet option supports repayment of the full balance or a fraction of it using available dollar, euro, or stablecoin balances. Repayments from fiat wallets incur no repayment commission, but a British pound or Swiss franc balance needs conversion into an accepted repayment currency. Full repayment closes the loan and stops further daily loan fees.
It remains unclear whether a partial payment changes the daily-fee base or PDL. Reducing the debt therefore does not establish that either the daily charge or the sale trigger improves. Crypto can also be converted to fund a repayment, adding the conversion cost to the transaction.
Bank repayment requires the correct reference, including the email address and loan ID, and involves contacting support about the transfer. A transfer sent close to expiry may still be in transit when the loan reaches its deadline.
A new loan has a term of up to 90 days. For loans opened after Mar. 21, 2025, the Extend feature requires acceptance of updated conditions and applies new rates after confirmation. An extension therefore needs a fresh cost calculation.
If a classic loan is not repaid by its deadline, YouHodler keeps it open for up to 14 more days. This overdue period is separate from the paid Extend feature. Each day, 1% of the total debt shown as the actual loan balance is converted at the opening exchange rate and deducted from collateral. The loan closes earlier if the remaining collateral, valued at that rate, falls below the debt.
If the debt is still unpaid when the period ends, YouHodler sells part of the collateral to cover it and credits the rest to the platform balance.
Ordinary full repayment releases the collateral to the platform wallet. Close Now uses collateral to repay the balance and credits what remains. Withdrawing released crypto to an external wallet is a further transaction with its own network and platform conditions.
Account Controls and Support
The loan details include the borrowed amount, accumulated fees, actual repayment balance, PDL, opening time, and repayment deadline. The individual agreement is downloadable as a PDF, and the loan ID gives support a reference for investigating a particular position.
Extend PDL changes the loan’s Price Down Limit by adding collateral for a 1.5% fee. The separate Extend feature lengthens the term at new rates. Neither takes effect until the borrower accepts the revised terms.
Account security includes two-factor authentication. Accounts holding more than the equivalent of $100 can request a block on crypto withdrawals, with extra identity verification required to re-enable them. The block leaves fiat withdrawals unaffected, so it does not protect loan proceeds held in a fiat wallet.
In-app and website support are available, with 24/7 service in the UK. The company provides an email contact for loan and bank-transfer queries.
Alternatives
-

Ledn
Ledn’s Bitcoin-Backed Dollar Loan uses BTC collateral and a 12-month term, with an annual percentage rate (APR) that includes its applicable administration fee. YouHodler quotes a daily loan fee that costs more when added to debt, so the comparison over a planned borrowing period must account for how those daily fees will be paid. Both products still need to cover the borrower’s location and payout method.
-
Nexo Credit Line
Nexo’s international Classic Credit Line has a 45-day early-repayment interest window after the latest draw, while YouHodler’s daily loan fees stop at full repayment. YouHodler’s paid controls add a different cost when adding collateral or increasing debt. For an eligible borrower planning a quick payoff or frequent changes, those charging rules can outweigh a lower advertised starting rate.
Pillar Scores
- Cost and pricing clarity 20% weight Interest, mandatory fees, pricing conditions, and the cost of early repayment.5.0 / 10
- Collateral control and counterparty risk 25% weight Custody, permitted collateral use, and recovery rights.5.0 / 10
- Liquidation rules and risk controls 20% weight Sale triggers, warnings, penalties, and tools for managing collateral.5.0 / 10
- Repayment and flexibility 15% weight Partial payments, maturity, renewal, and collateral return.6.0 / 10
- Access and funding 10% weight Eligibility, verification, payout routes, and usable funds.6.0 / 10
- Account controls and support 10% weight Security controls, loan records, monitoring tools, and customer support.7.0 / 10
Final Verdict
YouHodler’s classic loan can suit an eligible borrower who keeps enough of the loan currency in the wallet to pay the lower daily fee and plans to manage the debt actively. Partial repayments and the loan controls, when offered, provide ways to adjust it as cash needs change. The paid loan controls can add fees, so the management plan needs a budget for each action as well as daily borrowing charges. Anyone needing a single fixed annual borrowing cost has less reason to choose YouHodler.
Best For
Eligible borrowers who can keep wallet funds for daily fees and actively manage their collateral
Avoid If
- Borrowers needing a fixed annual borrowing cost or certainty that collateral cannot be reused
CryptoSlate may earn a commission when you use partner links, at no extra cost to you. Our reviews, ratings, and editorial decisions remain independent of advertisers. Read How CryptoSlate Makes Money for funding details.