 Released in 2018
- 12-month Bitcoin-backed loans
- No early-repayment penalty
- No traditional credit check
Ledn Overview
Key facts
- Product Name
- Ledn
- Release Date
- 2018
- Service model
- centralized
- Product status
- available
- Collateral & debt
- Bitcoin (BTC); Debt currency: USD
- Borrowing rate
- Individual quote required; individual quote; Tiered APR · Quote required. Lower APRs apply to larger loans, and the 2% administration fee is included in the APR where charged (US/Canada exempt).
Additional details
- Offer scope
- Ledn Bitcoin-Backed Dollar Loan; 12-month US dollar loan against BTC for eligible borrowers. Unavailable in California, Connecticut, Hawaii, Nevada, North Dakota, South Dakota, Tennessee, Washington, and Washington, D.C. Other states and countries can carry conditions on amount, APR, or purpose.
- Amount & term
- $500 general minimum · 12 months · Conditional renewal; Loan structure: Term loan; Minimum: USD 500; Maximum: Not disclosed; $500 general minimum · At least $1,000 in BTC to apply · Varies by country/state; Term: 12 months
- LTV & liquidation
- Partial sale to 65% at ≥80% LTV · Maturity triggers. Warnings at 70% and 75% LTV. At maturity, an eligible loan at or above 65% LTV is sold down to 64% before renewal.
- Fees
- 2% admin included in APR (US/Canada exempt) · Partial-wire bank charge
- Repayment
- At maturity · Early/partial allowed
- Availability
- Country/state restrictions · Nine US jurisdictions unavailable; KYC: Required; Credit check: Not required
- Payout
- Bank / stablecoins · Timing varies
- Custody
- Custodial · Funding pledges · No yield lending
Ledn Screenshots
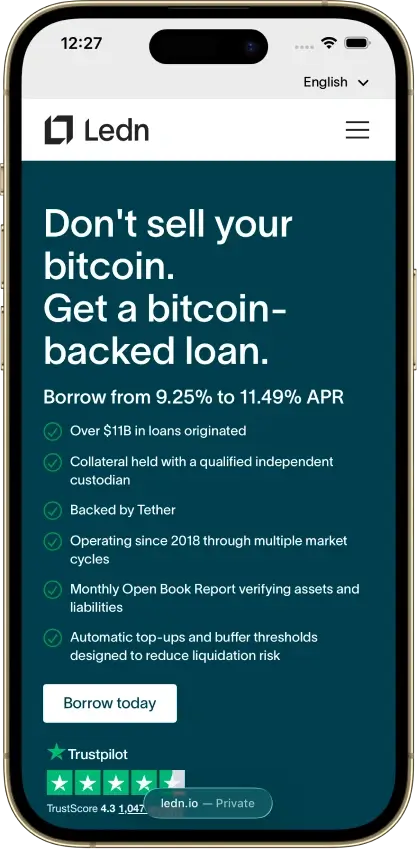
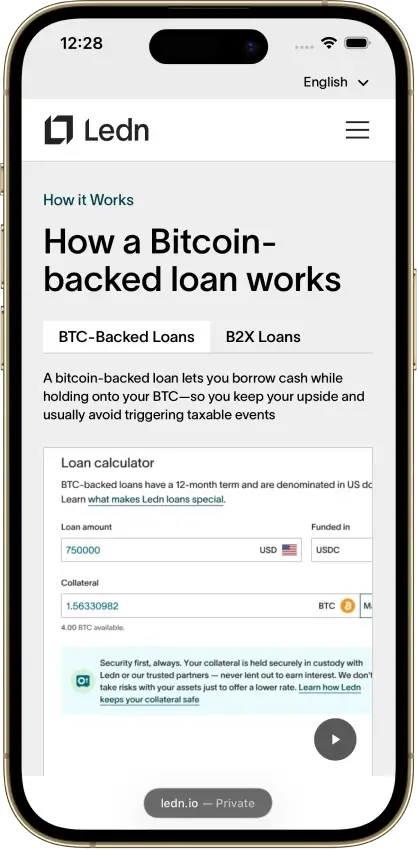
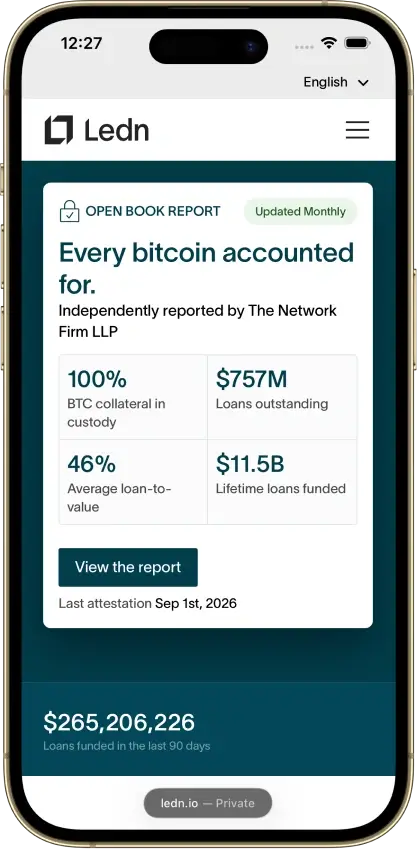
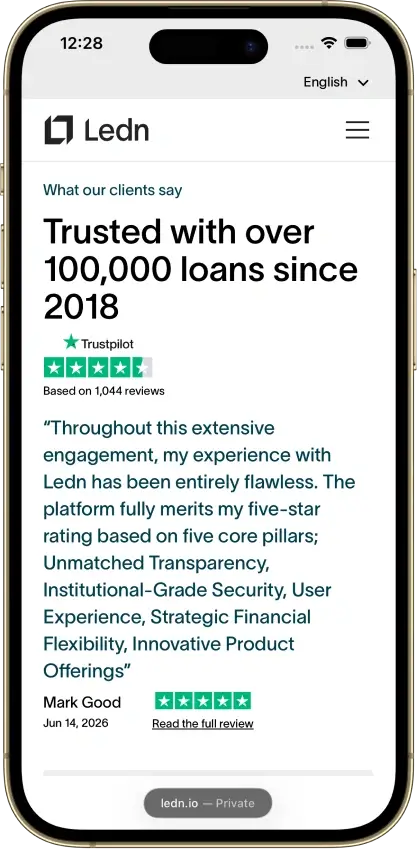
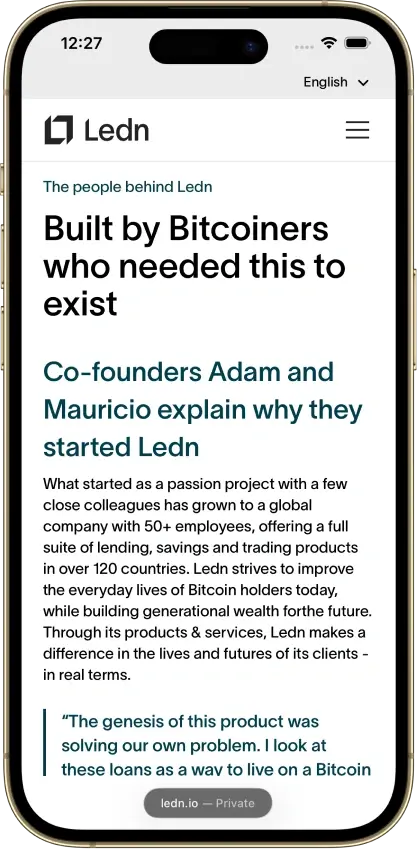
Screenshot 1 of 8
Ledn Pros and Cons
Pros
- Partial repayments supported
- Collateral not lent for yield
- LTV history and downloadable loan records
Cons
- Maturity can force BTC sales
- Collateral can be pledged for funding
- Bank payments and manual top-ups take time
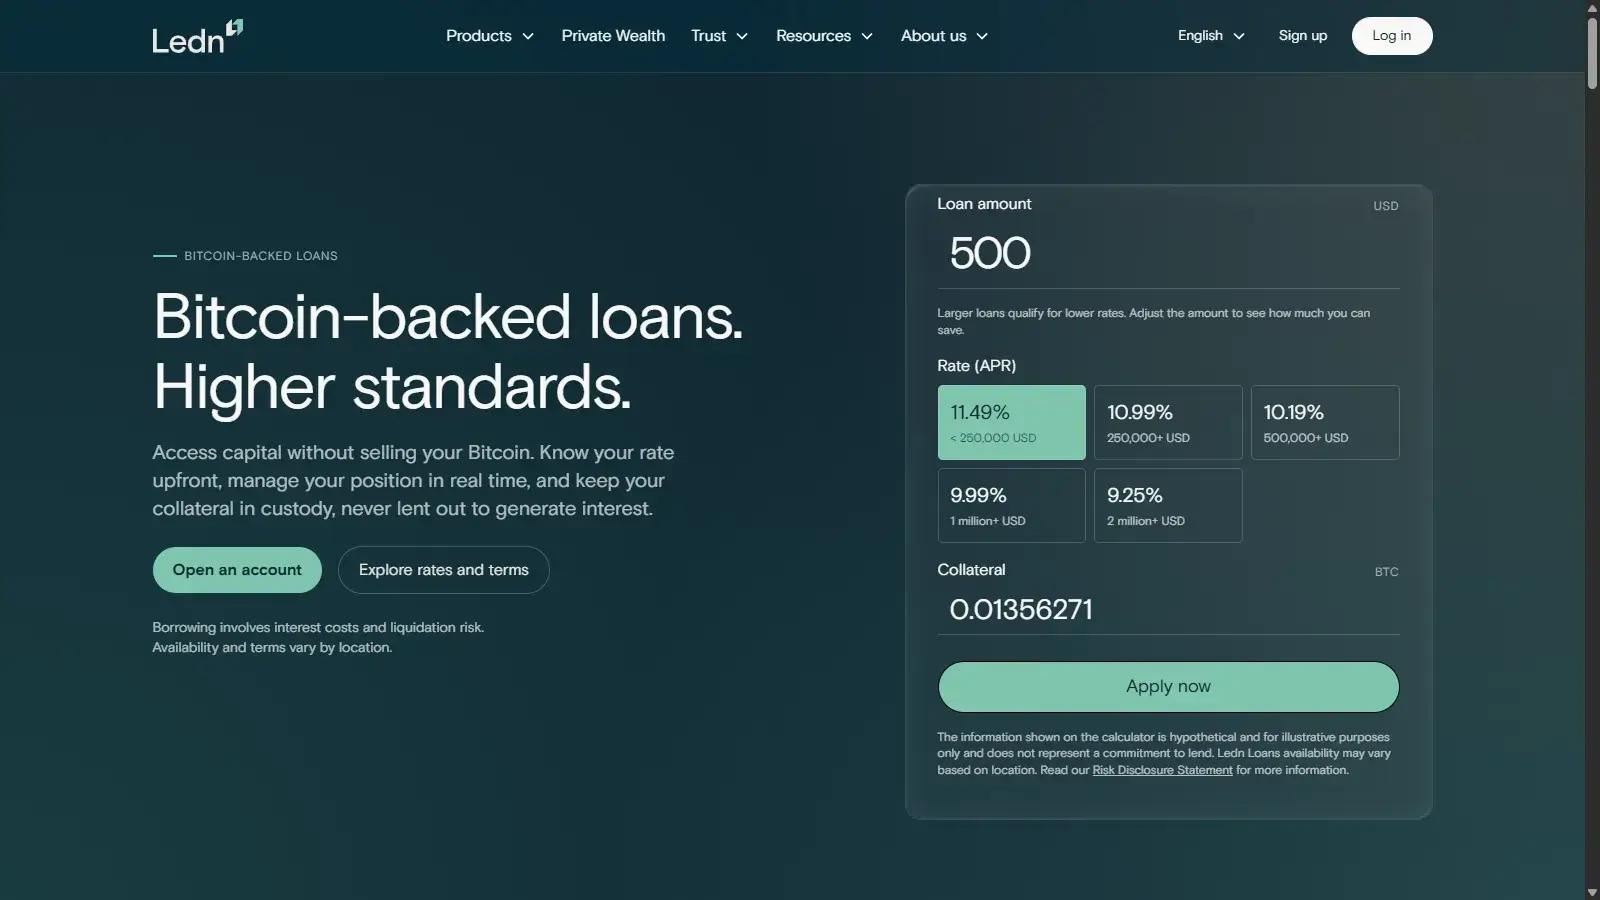
Rates and Fees
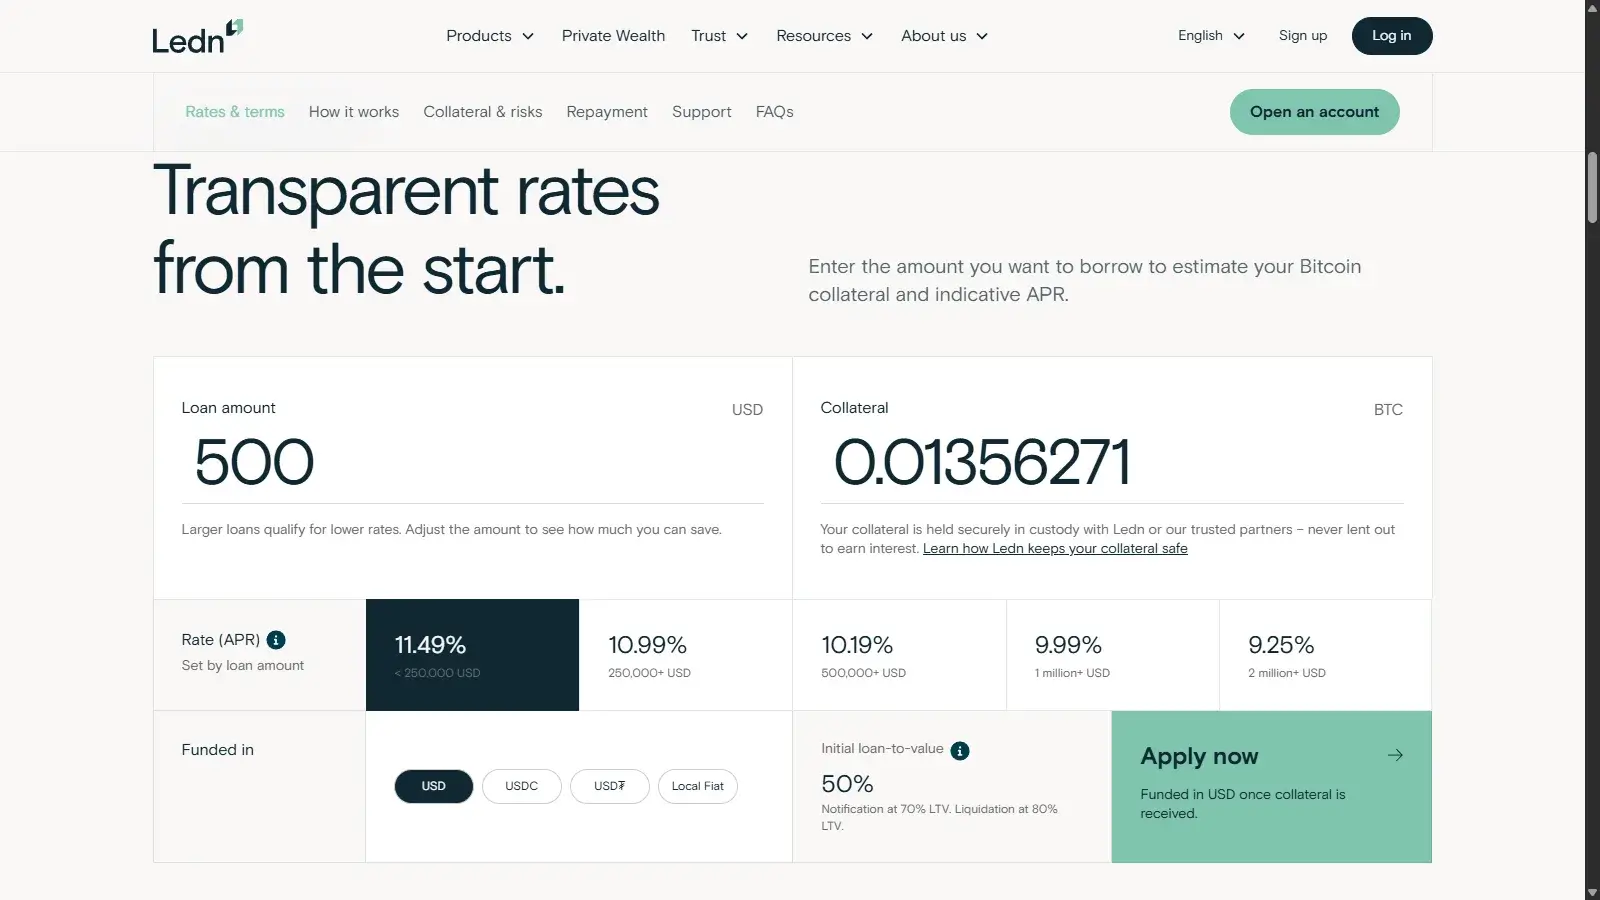
Ledn quotes the annual percentage rate (APR) according to amount and jurisdiction, with existing loans keeping their rate until maturity. Renewal or refinancing uses the tier then available, so a borrower planning more than 12 months cannot treat the original rate as the cost of the full borrowing period.
The 2% administration fee is included in APR where charged, with US and Canadian residents exempt. Comparing an APR with another lender’s interest rate alone would therefore omit part of the price difference.
Early repayment has no prepayment penalty, but paying in stages can still incur payment costs. Each partial repayment by US dollar wire has a $6.11 receiving-bank charge deducted before the loan is credited. Other bank charges can also apply, so the amount sent may exceed the amount that reduces the balance.
Collateral, Loan Amounts, and LTV
The Dollar Loan uses Bitcoin as collateral and has a general $500 minimum, subject to regional limits. Applicants need at least $1,000 worth of BTC to apply. A typical loan starts at 50% loan-to-value (LTV), meaning debt equals half the assessed BTC value. Each loan’s agreement sets the collateral it requires.
Debt stays in US dollars whether proceeds arrive by bank wire or stablecoin. Because the collateral is BTC, a fall in Bitcoin’s dollar price raises LTV even when the amount owed has not changed.
Ledn calculates LTV from outstanding debt and collateral value after deducting a 0.50% trading spread from the BTC market price. The displayed ratio already includes that spread, leaving slightly less assessed collateral than a calculation using the unadjusted market price.
Liquidation and Collateral Management
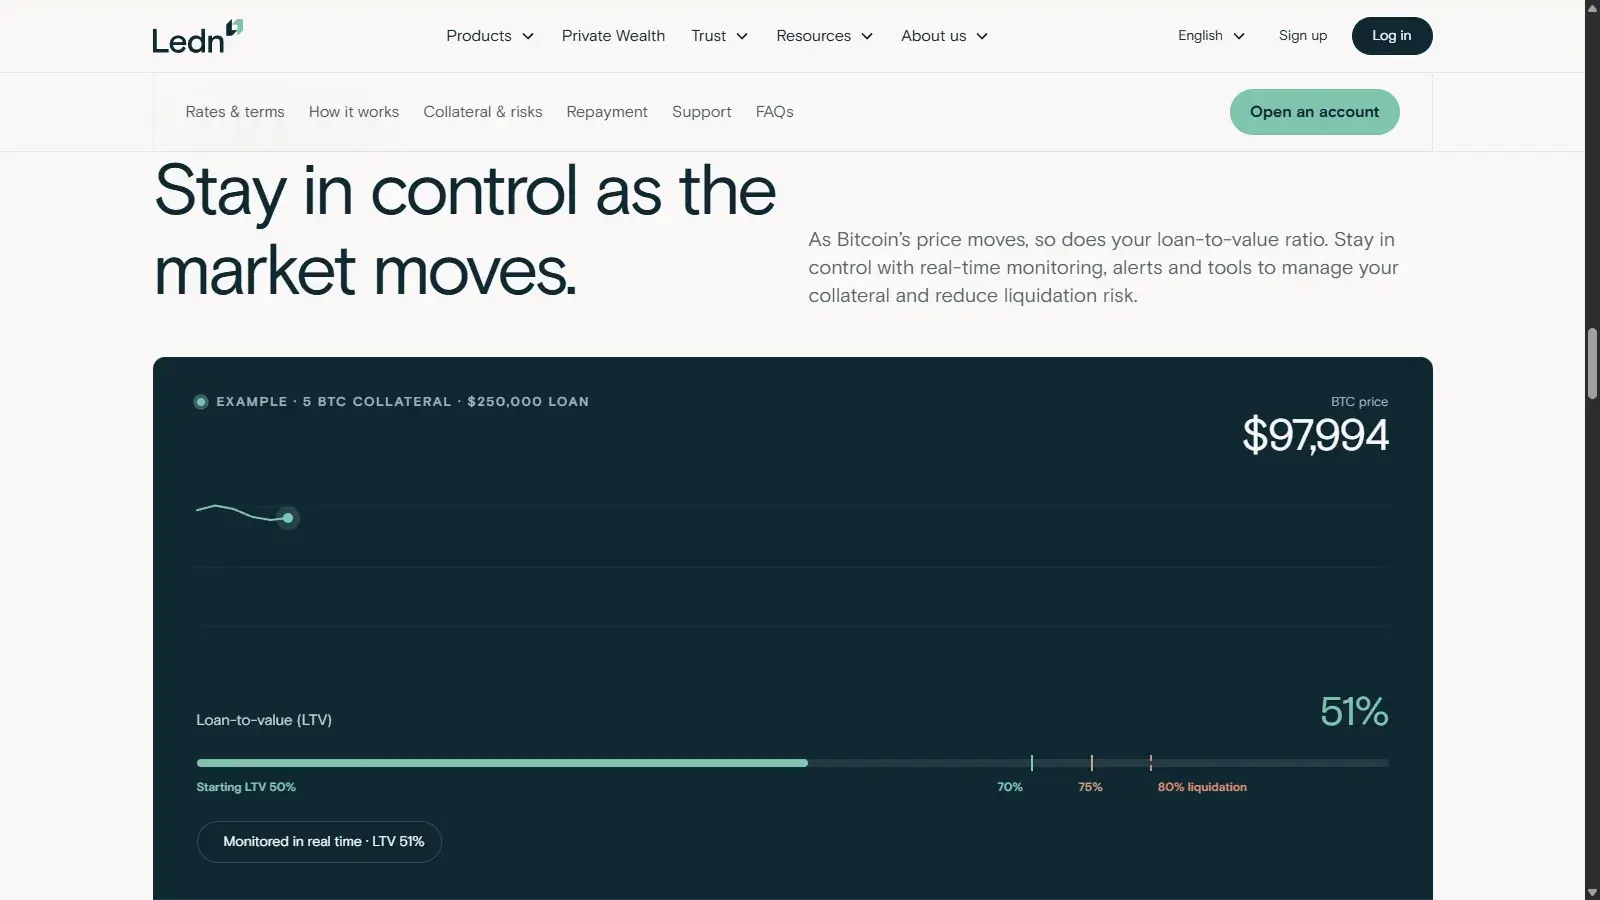
Ledn sends LTV warnings at 70% and 75%. At or above 80%, it automatically sells only enough BTC to bring the loan back to 65% LTV. The loan stays open, interest continues on the reduced principal, and the rule also covers loans opened before it took effect. Once a sale starts, it cannot be stopped or reversed.
Sale proceeds go first to any administration fee, then to accrued interest, and then to principal. Partial sales can repeat on the same loan with no limit, and Ledn emails a record after each one. If the collateral is too small to restore 65% LTV, Ledn sells it and applies the proceeds to the balance. Another default under the loan agreement can also lead to a wider sale.
For a loan with $10,000 debt and 0.2 BTC collateral, a hypothetical $100,000 Bitcoin price produces the following position. This simplified example holds debt constant, applies Ledn’s valuation spread, and excludes later interest, fees, top-ups, and sale-price variation.
Illustrative Position
- Starting LTV at BTC $100,000
50.25%
- BTC market price corresponding to 70% LTV
$71,787.51
- BTC market price corresponding to 80% LTV
$62,814.07
In this example, the loan reaches the 80% trigger well before Bitcoin loses half its value. A partial sale at that price would sell about 0.086 BTC, leaving roughly $4,643 of debt against about 0.114 BTC at 65% LTV. Interest increases the outstanding debt, so a smaller price drop can reach the trigger.
Ledn’s Auto Top-Up moves available BTC from the Transaction Account into collateral at 70% LTV. It requires a funded balance and regional access to the feature. Manual top-ups also need blockchain confirmations before reducing LTV. Both routes therefore depend on funds arriving in time, and a rapid price move can still lead to liquidation.
Custody, Collateral Use, and Security
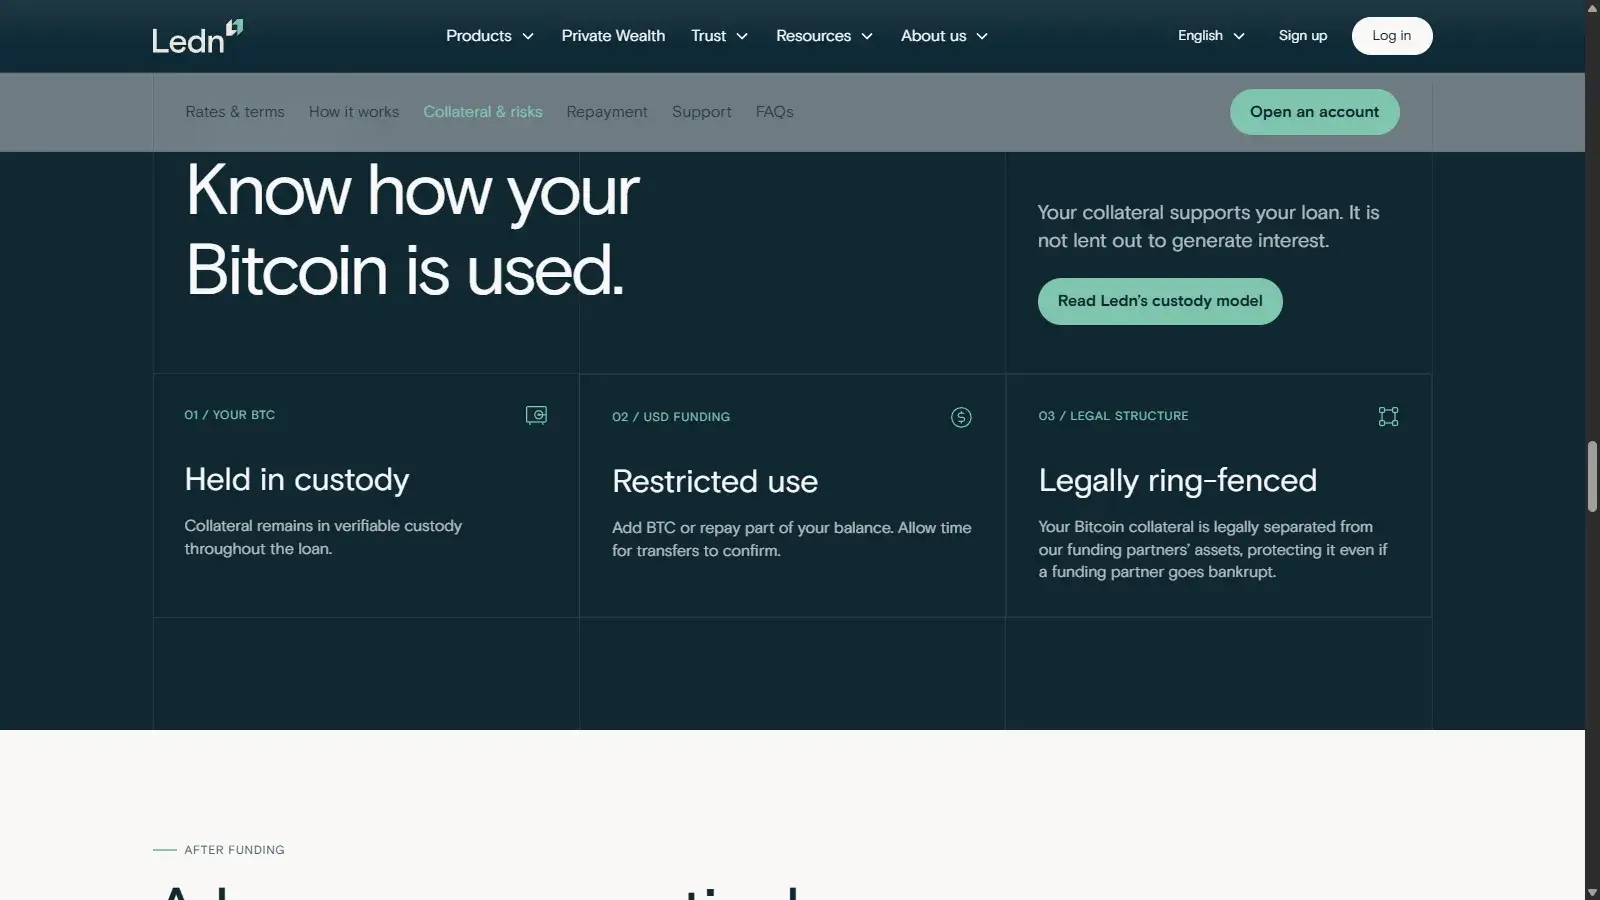
Ledn’s Custodied Loan policy permits BTC to be pledged to an institutional dollar funding partner or a Ledn-sponsored financing vehicle, while prohibiting those parties from lending it for yield. The BTC can still serve as security for the money supplied by funding partners.
Ledn describes those arrangements as legally separated from a funding partner’s assets or held in bankruptcy-remote financing vehicles. Those protections address a funding partner’s bankruptcy, with their effect depending on the agreement and legal process. They leave the borrower relying on a legal claim while the Bitcoin remains outside their control.
US accounts moving to Ledn US LLC use that entity for loans originated after the move. Existing loans remain with Ledn Cayman until closure or renewal under Ledn’s US account-migration rules, so renewing can change the party responsible for the loan. Ledn US LLC’s Financial Crimes Enforcement Network (FinCEN) registration covers money transmission, not authorization for a particular state’s loan or government endorsement.
Ledn’s monthly Open Book metrics have no independent audit or assurance. It also lists a proof-of-reserves assessment as of Sept. 30, 2026. Neither the loan metrics nor a point-in-time reserves assessment guarantees what an individual borrower would recover after a funding or custody failure.
Availability, KYC, and Credit Checks
Loans are unavailable in California, Connecticut, Hawaii, Nevada, North Dakota, South Dakota, Tennessee, Washington, and Washington, D.C. In other US states, Dollar Loans can carry conditions on loan amount, APR, or borrowing purpose. UK applicants are directed to Client Success for eligibility guidance. Location and loan purpose decide which rate quote is relevant to the borrower.
Ledn skips a traditional credit check but requires identity documents and proof of address. Know-your-customer (KYC) checks can also ask where funds or wealth came from and request income information, adding time before the borrower can post collateral.
During the move to Ledn US LLC, an existing US account can have functions restricted until refreshed information is approved. An existing US borrower may have to complete that update to open another loan.
Application, Payout, and Timing
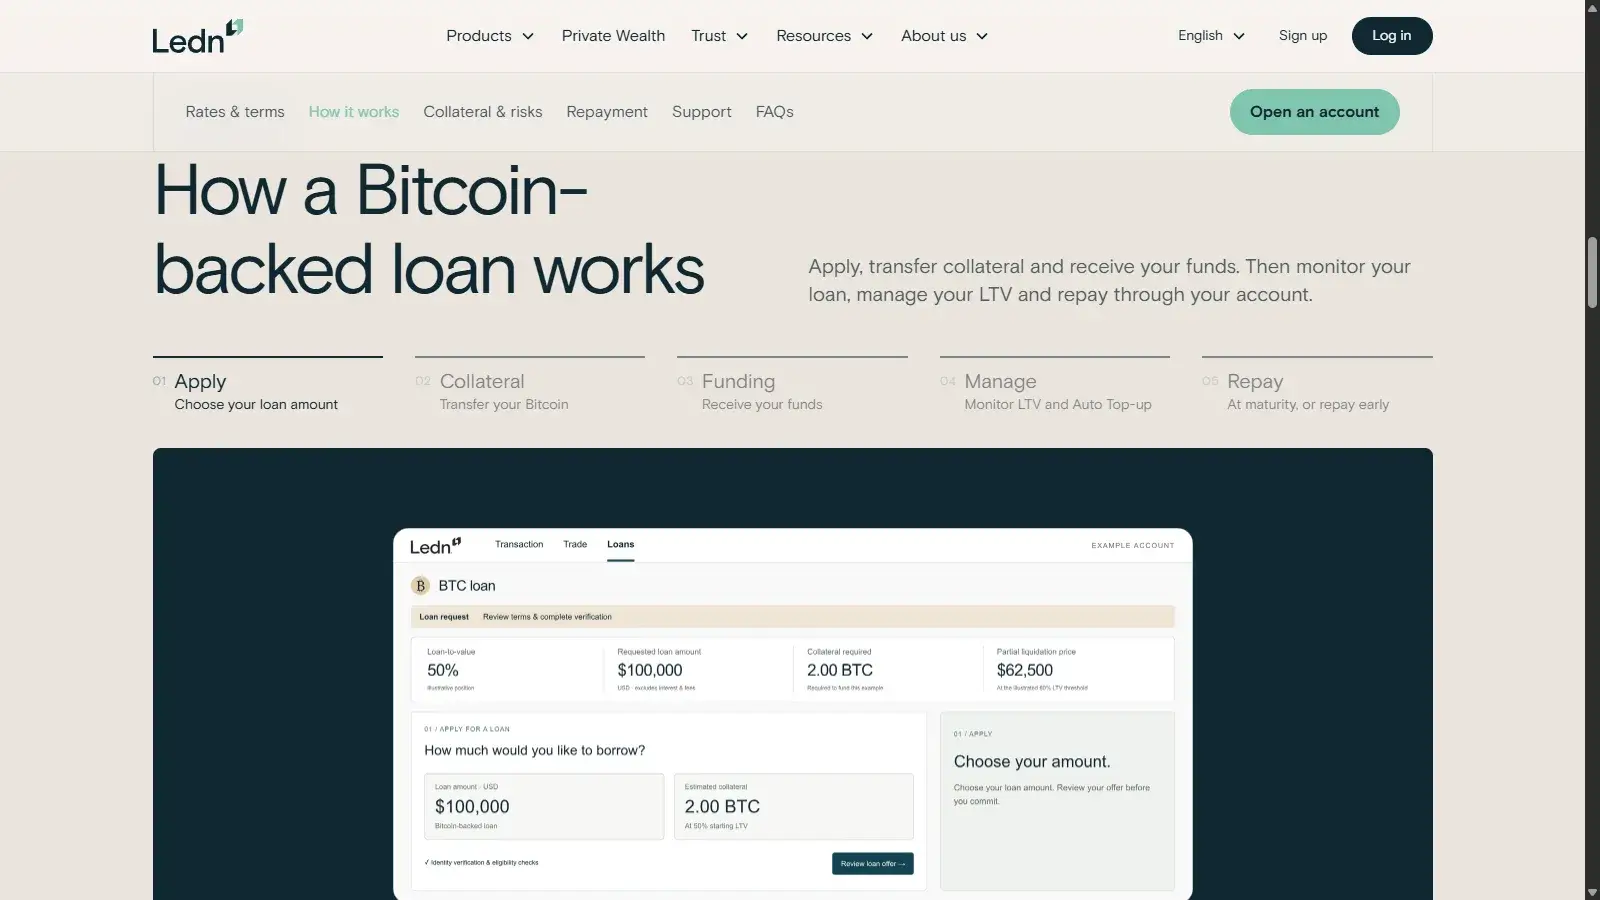
The application starts with account verification. The borrower then completes the application, reviews its terms, and transfers BTC collateral. Ledn disburses the loan after collateral verification. The individual agreement remains available in the account.
Ledn estimates up to two business days for manual identity verification, with more time possible if further checks are needed. Collateral verification and payout processing add to that wait.
After collateral verification, Ledn’s estimated processing times are up to 12 business hours for a bank wire and a few minutes for a stablecoin payout, where available. Receiving-bank processing, weekends, and holidays can extend the time before cash reaches the bank account.
The receiving bank account must be in the borrower’s legal name. Third-party, brokerage, investment, exchange, and “For Further Credit” destinations are excluded. Individual borrowers use personal accounts and corporate borrowers use business accounts, so the payout destination must match the verified borrower.
Repayment, Renewal, and Collateral Return
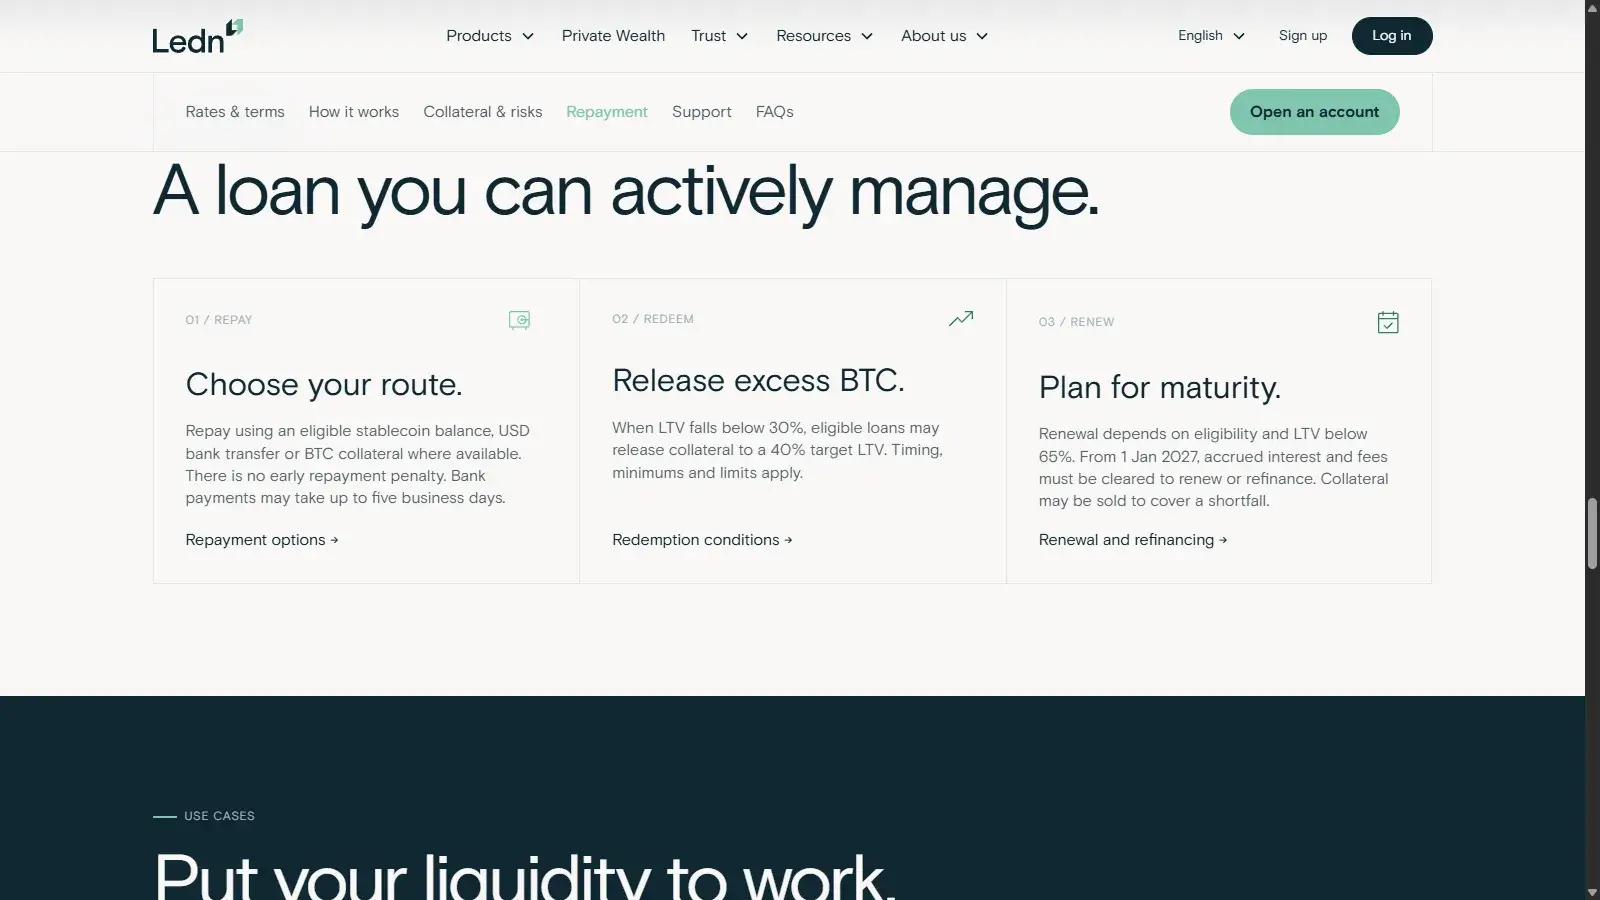
Repayment options include eligible stablecoin balances, dollar bank payments, and BTC collateral where that method is available. Using collateral to settle the debt reduces the Bitcoin you keep. Bank repayments can take up to five business days to process, leaving the loan exposed to price changes while payment is pending.
Each partial payment clears accrued interest and fees first, with only the remainder reducing principal and the daily interest charged on it. The minimum is 100 units of an eligible stablecoin, $1,000 by wire, or $100 equivalent from collateral. Because no partial payment may leave less than $500 outstanding, taking the balance below that means repaying in full.
Renewal Conditions and the 2027 Change
Automatic renewal without a collateral sale requires an eligible location and LTV below 65%. Renewals and refinancing on or after Jan. 1, 2027, also require clearing all accrued interest and fees. Interest accrues daily with no required monthly payments, so those charges can build up until maturity.
At maturity, Ledn’s renewal policy describes a backstop sale that brings an eligible loan at or above 65% LTV down to 64% before the remaining principal renews. The renewal page treats exactly 65% as needing that sale, while the 2027 guide has described renewal eligibility as “at or below 65%.” The two pages therefore disagree on whether a loan at exactly 65% is sold.
From Jan. 1, 2027, the backstop also clears unpaid accrued interest and fees, using available stablecoins first and then selling the minimum BTC needed. Maturity can force a sale even before the loan reaches its price-based liquidation threshold.
A loan outside an eligible location does not renew automatically, and Ledn can sell its collateral at maturity if it remains unpaid.
Releasing Bitcoin
Ledn’s excess-collateral feature can release BTC when LTV falls below 30%, returning the loan toward a 40% target. The loan must be more than 60 days into the term, with no release in the previous 60 days, and outside the final 30 days before maturity. Those timing rules limit withdrawals even after Bitcoin’s price rises.
After full repayment using collateral, remaining BTC returns to the Transaction Account. Moving it to an external wallet requires a separate withdrawal.
Account Controls and Support
Two-factor authentication supports text messages, passkeys, and hardware security keys, with authenticator codes retained for existing setups. Changing a safelisted withdrawal address requires extra authentication and starts a 48-hour external-withdrawal restriction. Internal loan paydowns remain available, so the restriction can delay moving returned BTC without preventing an internal debt reduction.
LTV history, repayment previews, and CSV/PDF exports show how the loan’s ratio has moved and what it would take to repay. Payment and disbursement questions go to Client Success, Ledn’s support team.
Alternatives
-

Nexo Credit Line
Under its international terms, Nexo’s revolving Credit Line can suit borrowers who want to borrow against several collateral assets and draw again after repaying. Each Ledn loan is a 12-month agreement whose amount cannot be increased, so extra borrowing requires another loan with its own collateral and terms. Keeping that particular loan open past maturity depends on renewal, while the choice between structures turns on how often funds are needed and which assets can secure them.
-
Coinbase Borrow
Coinbase Borrow connects fixed- and variable-rate USD Coin (USDC) borrowing to Morpho on Base. Using that decentralized finance (DeFi) market adds protocol and market dependencies to collateral-price exposure. Coinbase adds its processing fee to the loan balance, while its fixed and variable options have different maturity and early-repayment rules. An eligible borrower needs to match the available variant to the desired term and payout before comparing cost.
Pillar Scores
- Cost and pricing clarity 20% weight Interest, mandatory fees, pricing conditions, and the cost of early repayment.7.0 / 10
- Collateral control and counterparty risk 25% weight Custody, permitted collateral use, and recovery rights.7.0 / 10
- Liquidation rules and risk controls 20% weight Sale triggers, warnings, penalties, and tools for managing collateral.8.0 / 10
- Repayment and flexibility 15% weight Partial payments, maturity, renewal, and collateral return.7.0 / 10
- Access and funding 10% weight Eligibility, verification, payout routes, and usable funds.7.0 / 10
- Account controls and support 10% weight Security controls, loan records, monitoring tools, and customer support.8.0 / 10
Final Verdict
Ledn fits eligible Bitcoin holders who want a 12-month loan and flexibility to repay early or in stages. The main costs are the quoted APR, which includes any applicable administration fee, plus payment-method charges. Ledn can pledge BTC to its funding partners, and both price movements and unpaid maturity obligations can trigger a sale. That makes the loan a poor fit for borrowers who need unrestricted access to their Bitcoin or cannot clear accrued charges and meet the renewal LTV conditions at maturity.
Best For
Eligible Bitcoin holders seeking a 12-month loan with the option to repay early or in stages
Avoid If
- Borrowers needing unrestricted Bitcoin access or unable to meet renewal costs and collateral requirements
CryptoSlate may earn a commission when you use partner links, at no extra cost to you. Our reviews, ratings, and editorial decisions remain independent of advertisers. Read How CryptoSlate Makes Money for funding details.