Quick Take
- Multicoin Capital proposes turning AI computing hardware, future GPU capacity and customer revenues into collateral for stablecoin loans.
- The plan targets AI's $419 billion borrowing boom, as GPU lender USD.AI reports $26.5 billion in financing requests from computing operators.
- However, falling GPU values, borrower defaults and delayed withdrawals could expose DeFi investors to losses despite collateral protections.

Multicoin Capital partner Shayon Sengupta wants AI companies to borrow stablecoins against GPUs and future computing revenue.
In an Oct. 8 research note, Sengupta proposed creating blockchain-based markets where ownership claims on computing hardware, future data center capacity, and customer payments could be traded or pledged as collateral.
The proposal comes as AI infrastructure borrowing accelerates, creating opportunities for decentralized finance (DeFi) protocols to provide capital to companies struggling to fund expensive computing equipment.
AI financing booms
The rapid expansion of artificial intelligence has triggered unprecedented borrowing as technology companies race to build data centers and acquire the powerful chips needed to operate AI models.
According to The Kobeissi Letter, US dollar-denominated corporate bond issuance linked to AI reached a record $419 billion in 2026 as of Oct. 21.
That represents a 90% increase from the entire 2025 total and a 437% increase from 2024.
Major technology companies, including Alphabet, Amazon, Meta, Microsoft and Oracle, accounted for $157 billion of the borrowing, while investment-grade and high-yield data center and computing companies raised another $103 billion.
However, smaller AI infrastructure operators face a different financing environment.
Many have secured customer contracts and ordered computing equipment but lack the balance sheets and financing relationships that let tech giants raise billions through conventional debt markets.
David Choi, co-founder of GPU financing platform USD.AI, highlighted the scale of this unmet demand.
He said the platform has received more than 700 financing requests totaling $26.5 billion since its launch, with about $8.7 billion moving through different stages of evaluation.
Most requests come from operators seeking between $10 million and $300 million to expand their computing capacity.
Choi argued that traditional financing, which often requires lenders to negotiate individual agreements, struggles to accommodate that volume of transactions.
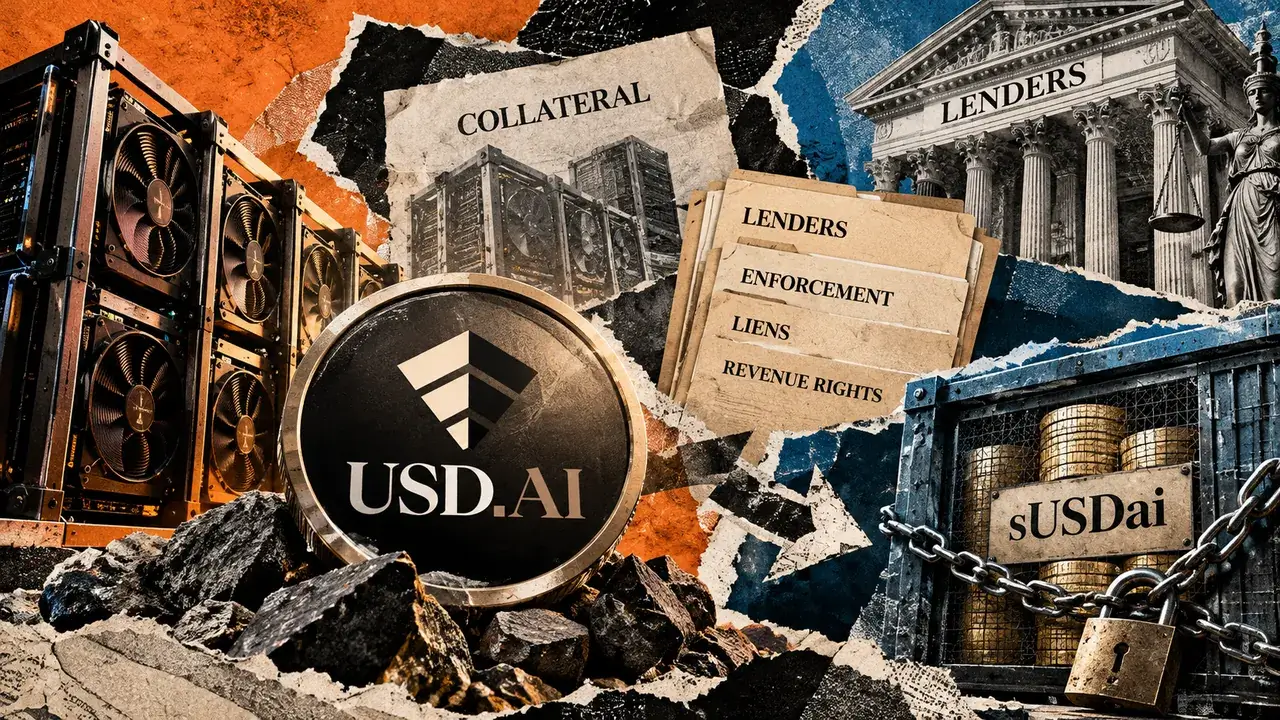
USD.AI is trying to close the gap with standardized loans secured by GPU equipment, connecting borrowers with stablecoin capital and institutional lenders.
The company reported more than $420 million in lifetime deployed capital and $659 million in total value locked as of Oct. 2, illustrating the difference between financing demand and loans already deployed.
Meanwhile, Sengupta envisions a broader market where AI companies could raise money against assets beyond physical hardware.
Under his proposal, a data center operator could issue a transferable digital claim representing access to a GPU cluster during a future period.
That claim could be sold to another customer or pledged to secure a stablecoin loan, letting the operator finance computing capacity it has yet to deliver.
Similarly, companies could borrow against payments expected from existing customer contracts, potentially reducing their dependence on traditional lenders.
Sengupta believes blockchain networks could support these transactions by allowing lenders to verify pledged assets, monitor existing debt obligations and automate payments as computing services are delivered.
He also proposed specialized intermediaries that could connect compute buyers and sellers while managing collateral, financing and price risks across multiple operators.
Such a market could help smaller providers obtain capital against verified computing capacity rather than depending solely on long-term customer contracts.
GPU collateral risks
However, financing physical AI infrastructure through DeFi creates challenges involving collateral ownership, loan defaults, and investor liquidity.
USD.AI's existing lending structure illustrates how these risks are managed.
The protocol allows investors to stake its USDai stablecoin and receive sUSDai, a yield-bearing token that provides exposure to financing activities, including loans secured by GPU infrastructure.
While USDai itself is backed by PayPal's PYUSD stablecoin, sUSDai holders earn returns linked to the underlying lending portfolio.
USD.AI reported a 6.9% net annualized yield for sUSDai in its September update.
The loans are secured by physical computing equipment, providing lenders with assets they can potentially recover or sell if borrowers fail to repay.
However, individual sUSDai holders do not directly own those GPUs or control what happens to them following a default.
Under USD.AI's financing arrangements, dedicated legal entities hold the equipment, while lenders and appointed agents exercise rights to recover collateral.
If a borrower defaults, the agents can take control of relevant accounts, redirect customer payments, replace an operator, or arrange the sale of equipment to recover outstanding debts.
The proceeds ultimately flow through the lending structure, meaning sUSDai investors depend on the recovery process rather than exercising those rights individually.
Investors also face restrictions when withdrawing their money.
Unlike USDai, sUSDai cannot be redeemed immediately at a fixed dollar value. Its withdrawal system operates through 30-day cycles, with payments dependent on how much liquid capital the protocol has available.
If withdrawal requests exceed available funds, investors may receive partial payments and have to wait through additional cycles to recover the remainder.
The protocol does not automatically liquidate performing GPU loans to meet those requests, creating a potential mismatch between longer-term infrastructure financing and investors seeking liquidity.
Collateral values introduce another challenge.
GPU prices can decline as newer hardware becomes available, while computing operators depend on continued customer demand to generate the revenue needed to repay their loans.
Even when lenders have enforceable claims over the equipment, selling it after a default may not recover the full outstanding balance.
USD.AI has introduced additional protections, including residual-value warranties on certain loans that cover part of the shortfall when equipment sells below agreed levels. The warranties remain subject to contractual conditions.
The underlying risk also affects conventional AI financing.
For example, CoreWeave secured a $2.6 billion credit facility with a roughly five-year maturity, backed by customer contracts averaging about three years.
That arrangement leaves lenders exposed to whether the company can renew contracts or find new customers after the initial agreements expire.
Sengupta's proposal seeks to address some financing constraints through transferable claims, transparent collateral records and broader access to stablecoin lenders.
However, he acknowledged that digital claims must be supported by enforceable legal rights, since blockchain records alone cannot guarantee ownership or recovery of physical assets.
Mentioned in this article
Editorial credits