
Quick Take
- Solana activated Alpenglow, targeting 150ms finality and merging confirmed and finalized into one state.
- Faster finality speeds settlement’s last step, but custody, compliance and funding delays can dominate the cycle.
- NSCC cuts obligations 98%, while atomic settlement may raise liquidity needs.

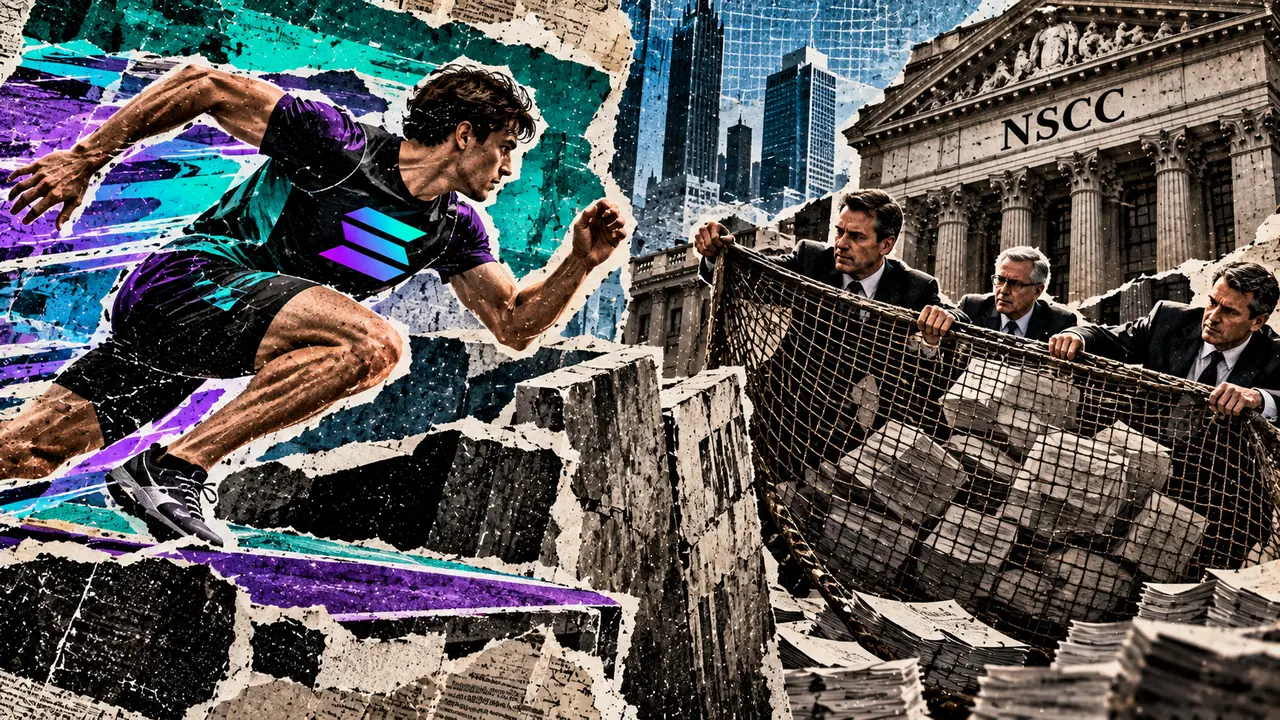
Solana activated Alpenglow on mainnet on Oct. 21 at slot 459,653,000, replacing TowerBFT with a consensus design that targets about 150 milliseconds to finality. Under the new protocol, confirmed and finalized become the same state.
At the National Securities Clearing Corporation (NSCC), multilateral netting cuts the value of equities payment obligations by an average of 98%.
Alpenglow shortens the time until a transaction becomes irreversible, and netting reduces the amount of money participants must move to complete trades.
What Solana's Alpenglow changes
The first phase of Solana’s Alpenglow upgrade, Votor, has validators exchange votes directly and aggregate them into certificates, which allows finalization in one or two voting rounds. Transaction execution, the Solana Virtual Machine, and fee mechanics stay as they were.
The second phase, Rotor, handles block propagation and remains unscheduled.
Solana's documentation says production applications read mostly at the confirmed level, and that every confirmed block has historically finalized.
The gain concentrates in workflows that wait for full finality before releasing assets or recognizing settlement.
Solana's documentation cites 12.8 seconds for TowerBFT finality at the older 400-millisecond slot time. Solana cut slots to 200 milliseconds on Oct. 9. Applying TowerBFT’s documented 32-slot finalization rule to that slot time gives a nominal 6.4-second baseline, rather than a measured end-to-end settlement time.
The 98% figure
NSCC acts as central counterparty for eligible equities trades, guaranteeing qualifying obligations and offsetting purchases and sales among participants so residual payments settle.
The Depository Trust & Clearing Corporation (DTCC) reports the 98% average reduction in payment value and $608 trillion of equity transactions processed in 2025.
The figure covers payment obligations and is separate from margin, regulatory capital, and peak intraday funding. It also reflects a market structure with central clearing, participant agreements, and risk management.
NSCC settles on T+1, the gap between trade date and settlement date, which differs from the time a system takes to process a payment.
Solana's delivery-versus-payment program shows that both parties fund separate escrow accounts, a settlement authority signs the exchange, and both legs execute atomically.
Applications are told to recognize settlement when the transaction is finalized, and the documentation separates network finality from finality under the parties' legal arrangements. Faster finality shortens the last step, and the parties must source and commit the assets beforehand.
The capital-reuse math
A sensitivity model assumes strictly sequential settlements, identical transactions, and instant reuse of funds, isolating latency as a measure separate from institutional savings.
From the nominal 6.4-second baseline to 0.15 seconds, the theoretical turnover multiplier is 42.7 times when consensus time is the full cycle and 10.6 times with half a second of other processing. It falls to 3.9 times with two seconds and 2.2 times with five, and to about 1.1 times with 60 seconds.
Against the 12.8-second baseline, the same steps give 85.3, 20.5, 6.9, 3.5 and 1.2 times.
Custody checks, funding transfers, compliance reviews and signatures are the usual sources of non-consensus delay, so the value of faster consensus depends on what holds capital back.
A turnover multiplier measures how often funds can cycle through serial settlements. It is separate from reductions in broker collateral or clearinghouse margin.
BIS describes a liquidity problem
The Bank for International Settlements warned in its 2023 blueprint that atomic settlement can raise liquidity demands unless liquidity-saving mechanisms accompany it. Real-time gross settlement raised funding needs relative to deferred net settlement in the same way.
A December 2025 BIS working paper simulated an auction-based mechanism on payment-system data from Peru, South Africa, the Southern African regional system and Switzerland.
It found liquidity savings of 2.6% to 12.2%, with the auction succeeding on average 79% of the time.
Settling every trade the moment it executes can also leave fewer outstanding obligations to offset. A design that preserves netting might batch compatible transfers into short programmable windows and then finalize quickly, with the window length set by matching rates, intraday liquidity and tolerable delay.
Incumbents are testing tokens
DTCC announced on July 15 that tokenized DTC-held securities had moved through live production transactions with more than 30 firms, covering Treasury and equity delivery-versus-payment, securities lending, collateral pledging and central-counterparty margin workflows.
DTCC used Besu and Canton. Its Tokenization Hub describes a voluntary service for eligible DTC participants under a December 2025 SEC no-action authorization.
Solana's September data, with $18 billion in stablecoin supply, about $4 billion of tokenized-stock trading against $684 million of tokenized-equity supply, and $78 billion of DEX volume, predates Solana's Alpenglow.
The upgrade also removes validator votes from blocks, so transaction-count comparisons across Oct. 21 need to exclude votes on both sides.
What is next for testing Solana's Alpenglow
If on-chain markets add enforceable offsetting, intraday credit and settlement rules before the residual transfer, the combination becomes the point.
With a hypothetical $10 billion of gross obligations and 90% netting, $1 billion remains to settle, and two seconds of other processing yields a 6.9 times turnover ceiling against the older baseline.
The offset ratio is a design assumption that depends on two-way order flow, institutional credit, custody, and usable cash-equivalent settlement assets.
If institutions prefund each trade and settle it separately, with obligations unoffset, Solana's finality yields a theoretical gain of about 1.2 times against the older baseline once 60 seconds of other processing is counted.
Against the recent baseline, the gain is 1.1 times, and gross liquidity needs stay the same. Retail and crypto-native applications could grow in that case while institutional securities clearing adopts the technology more slowly.
Observed mainnet finality, end-to-end settlement times, residual obligations against gross flows, peak prefunded liquidity, and legal finality will show which path Solana follows.
Mentioned in this article

Editorial credits