
Quick Take
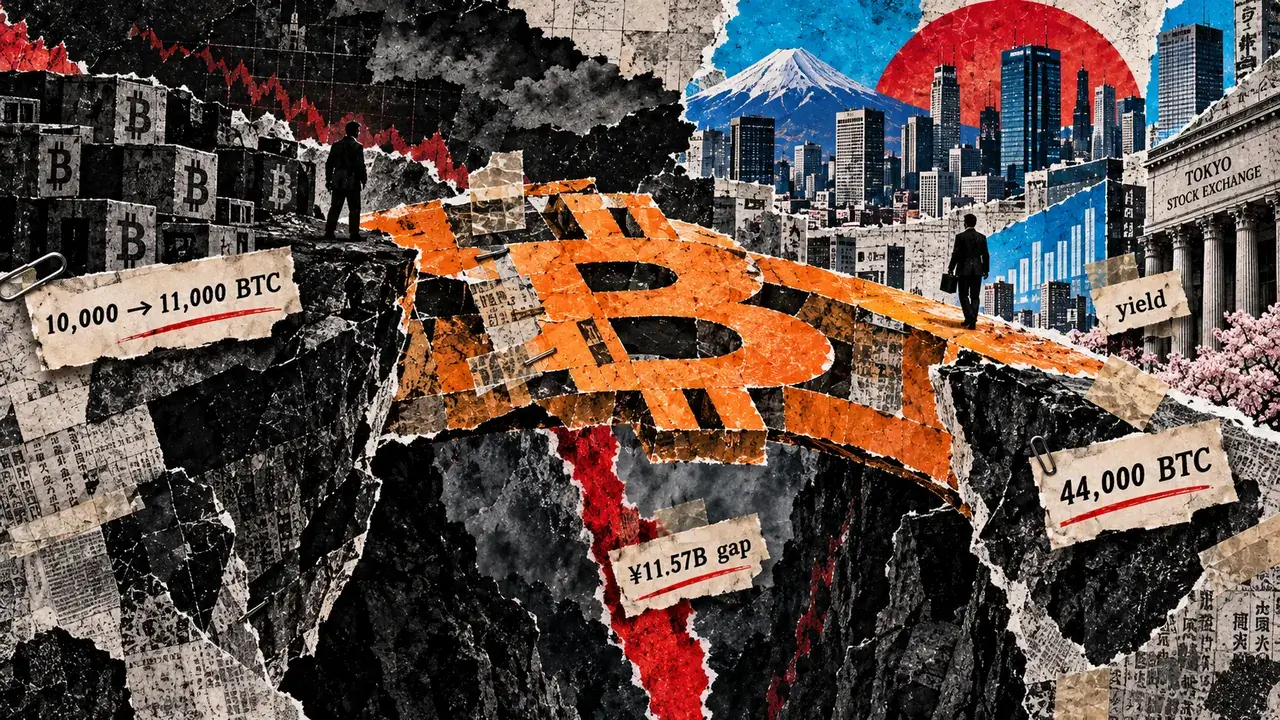
- Metaplanet sold 10,000 BTC and later bought 11,000 back, ending Q3 with 44,000 BTC.
- The move was designed to prove its Bitcoin could cover debt and support broader access to credit markets.
- Bitcoin rose before the repurchase, creating an ¥11.6 billion price gap as Metaplanet now seeks cheaper funding.


Metaplanet sold 10,000 Bitcoin and later bought back 11,000 BTC to strengthen its credit profile and expand beyond accumulation during the third quarter.
The Tokyo-listed company said it converted enough Bitcoin into cash during the third quarter to exceed the outstanding principal of its bonds, borrowings, and other interest-bearing debt. It subsequently rebuilt the position at a higher Bitcoin price, ending Sept. 30 with 44,000 BTC, up a net 1,000 for the quarter.
The transaction forms part of a broader attempt to convince rating agencies and fixed-income investors that Metaplanet's Bitcoin reserves can be monetized when obligations come due.
The company plans to seek a credit rating and use a stronger financing profile to support a new business that borrows through bonds, preferred stock and Bitcoin-backed facilities before investing in higher-yielding assets.
The liquidity demonstration came at a price
Bitcoin rose between Metaplanet's sale and repurchase, leaving the company paying substantially more to rebuild the position it had sold.
According to the preliminary, unaudited figures in its statement, Metaplanet disposed of 10,000 BTC at an average price of ¥12.47 million per coin, generating ¥124.7 billion in proceeds. It later purchased 11,000 BTC at an average price of ¥13.63 million per coin, spending ¥149.9 billion.
The roughly ¥1.16 million difference between the sale and repurchase prices implies an adverse price differential of about ¥11.57 billion on the 10,000 BTC needed to replace the original position. Metaplanet said the higher reacquisition price reflected Bitcoin's rise between the two transactions.
The company said it conducted the transactions separately rather than as a simultaneous exchange. It first sold the Bitcoin, held the proceeds in cash, and only later repurchased the asset, a sequence intended to demonstrate that its reserves could actually be converted into cash rather than merely pointing to Bitcoin's market liquidity.
That distinction is central to Metaplanet's push into credit markets. The company said rating agencies and fixed-income investors can discount Bitcoin's liquidity value if an issuer is unwilling to sell it when required. Metaplanet wants the Q3 transaction to show creditors that its long-term accumulation strategy does not prevent management from monetizing Bitcoin to meet financial obligations.
The sale also produced a US capital-loss carryforward. Metaplanet estimates subsidiaries of its US holding company could recognize a deferred tax asset of about $97 million, potentially available to offset future capital gains. The estimate remains subject to closing procedures and auditor review, and the company said the asset may ultimately be smaller or not recognized at all.
Metaplanet said the tax treatment could offset some or all of the effect of the gap between its sale and repurchase prices and transaction costs if it recognizes the deferred tax asset.
Metaplanet wants to turn cheaper funding into recurring income
The company plans to use any improvement in credit access for more than financing additional Bitcoin purchases.
Its newly announced Net Interest Income Strategy plans to raise capital through instruments including perpetual preferred stock, corporate bonds known as BitBonds and Bitcoin-collateralized credit facilities. Metaplanet would deploy that money into assets carrying yields above its all-in financing costs, retaining the difference as net interest income.
The company expects preferred securities issued by Bitcoin treasury companies and similar issuers to be among its principal investment targets. Those investments will sit inside a strategic allocation that Metaplanet expects to represent about 10% to 15% of total assets, with Bitcoin remaining about 85% to 90%.
That would move Metaplanet closer to a financial intermediary inside the growing Bitcoin treasury market. Rather than relying predominantly on rising Bitcoin holdings and equity issuance, the company wants to raise money at one cost, invest it at a higher yield, and recycle the resulting cash flow into debt service, preferred dividends, and further Bitcoin purchases.
Metaplanet sees Japan as one potential source of that funding advantage. It said yen-denominated financing generally carries lower interest rates than dollar funding, while Metaplanet Securities gives it direct distribution to Japanese investors seeking Bitcoin-linked yield products.
The company also expects its pending investment in Super League Enterprise to expand its access to US capital markets, potentially allowing it to choose between jurisdictions, maturities and financing structures depending on market conditions. The transaction has not yet closed and remains subject to conditions including regulatory procedures and shareholder approval.
Metaplanet's new income strategy keeps Bitcoin risk close
Metaplanet's attempt to diversify its earnings base could still leave much of the balance sheet exposed to the same underlying asset.
The company acknowledges that securities issued by Bitcoin treasury companies may move with Bitcoin, creating correlation between its core reserves and some investments intended to provide recurring income. Metaplanet said credit, issuer concentration, currency and leverage risks will be managed within limits approved by its board.
Its revised capital policy also distinguishes between borrowing used to acquire Bitcoin and leverage used for strategic investments. Bitcoin-related borrowings are generally targeted below about 10% of BTC net asset value, while financing attached to the strategic investment portfolio will be managed separately under an asset-liability framework.
Metaplanet expects the new net interest income strategy to have an immaterial effect on its 2026 consolidated results, leaving the credit-rating effort and future financing terms as the more immediate tests. The company has cautioned that it has no assurance it will receive a rating, what level it would receive, or whether it can issue future bonds and preferred shares on the terms it wants.
The next phase will therefore depend on whether creditors reward Metaplanet for proving it is willing to sell Bitcoin when necessary. A lower cost of capital would give the company room to scale its spread strategy; without it, the economics of borrowing to buy yield-bearing Bitcoin-linked securities become considerably tighter.
Mentioned in this article


Editorial credits